
What Labcorp Stock's Bladder Cancer Recurrence Study Means For Shareholders
- Labcorp announced a past collaboration with OHSU's Knight Cancer Institute on an investigator-led study using its Plasma Detect Genome MRD Ultra test to monitor molecular residual disease and potentially spot muscle invasive bladder cancer recurrence earlier through circulating tumor DNA in blood.
- The partnership deepens Labcorp's oncology footprint by pairing its whole genome MRD platform with a leading cancer center, generating clinical evidence that could influence how physicians tailor follow up care and treatment intensity for high risk bladder cancer patients.
- Next, the focus shifts to what this MRD collaboration could mean for Labcorp's broader investment narrative around diagnostics and clinical research.
Scan other diagnostics and clinical research stocks that are riding similar healthcare tailwinds by reviewing the list of solid balance sheet and fundamentals (23 results) alongside Labcorp Holdings' latest MRD and trial technology moves.
Labcorp Holdings Investment Narrative Recap
To own Labcorp Holdings, you need to believe its mix of Diagnostics Laboratories and Biopharma Laboratory Services can keep pulling in steady test volume while technology helps protect margins. The OHSU MRD study and Plasma Detect Genome MRD Ultra work speak to that thesis, but the near term picture still hinges more on day to day test demand and contract wins than on one trial.
The most important short term swing factor remains execution in core diagnostics and clinical trial services as tariffs, regulatory shifts such as PAMA and competitive pricing pressure play out. The recent MRD collaboration is directionally aligned with oncology and test innovation themes, although the financial impact from this single study alone looks limited for now.
Alongside MRD research, the recent upgrade to Labcorp Global Trial Connect feels more immediately tied to operational levers. The refreshed sponsor and investigator portals, with kit ordering embedded in the workflow and an oversight dashboard, target concrete frictions in clinical trial set up and monitoring that matter for the Biopharma Laboratory Services segment.
For catalysts, this digital platform work intersects directly with one of the key risks you are watching: the unpredictability and timing of trial starts. If customers find Global Trial Connect simplifies reporting, sample tracking and supply management, that can support Labcorp Holdings as a preferred partner when biopharma budgets are under scrutiny, while still leaving regulatory and funding risks firmly on the table.
Labcorp Holdings' narrative projects US$16.6b revenue and US$1.4b earnings by 2029. This implies 5.0% yearly revenue growth and an earnings increase of about US$0.4b from US$1.0b today.
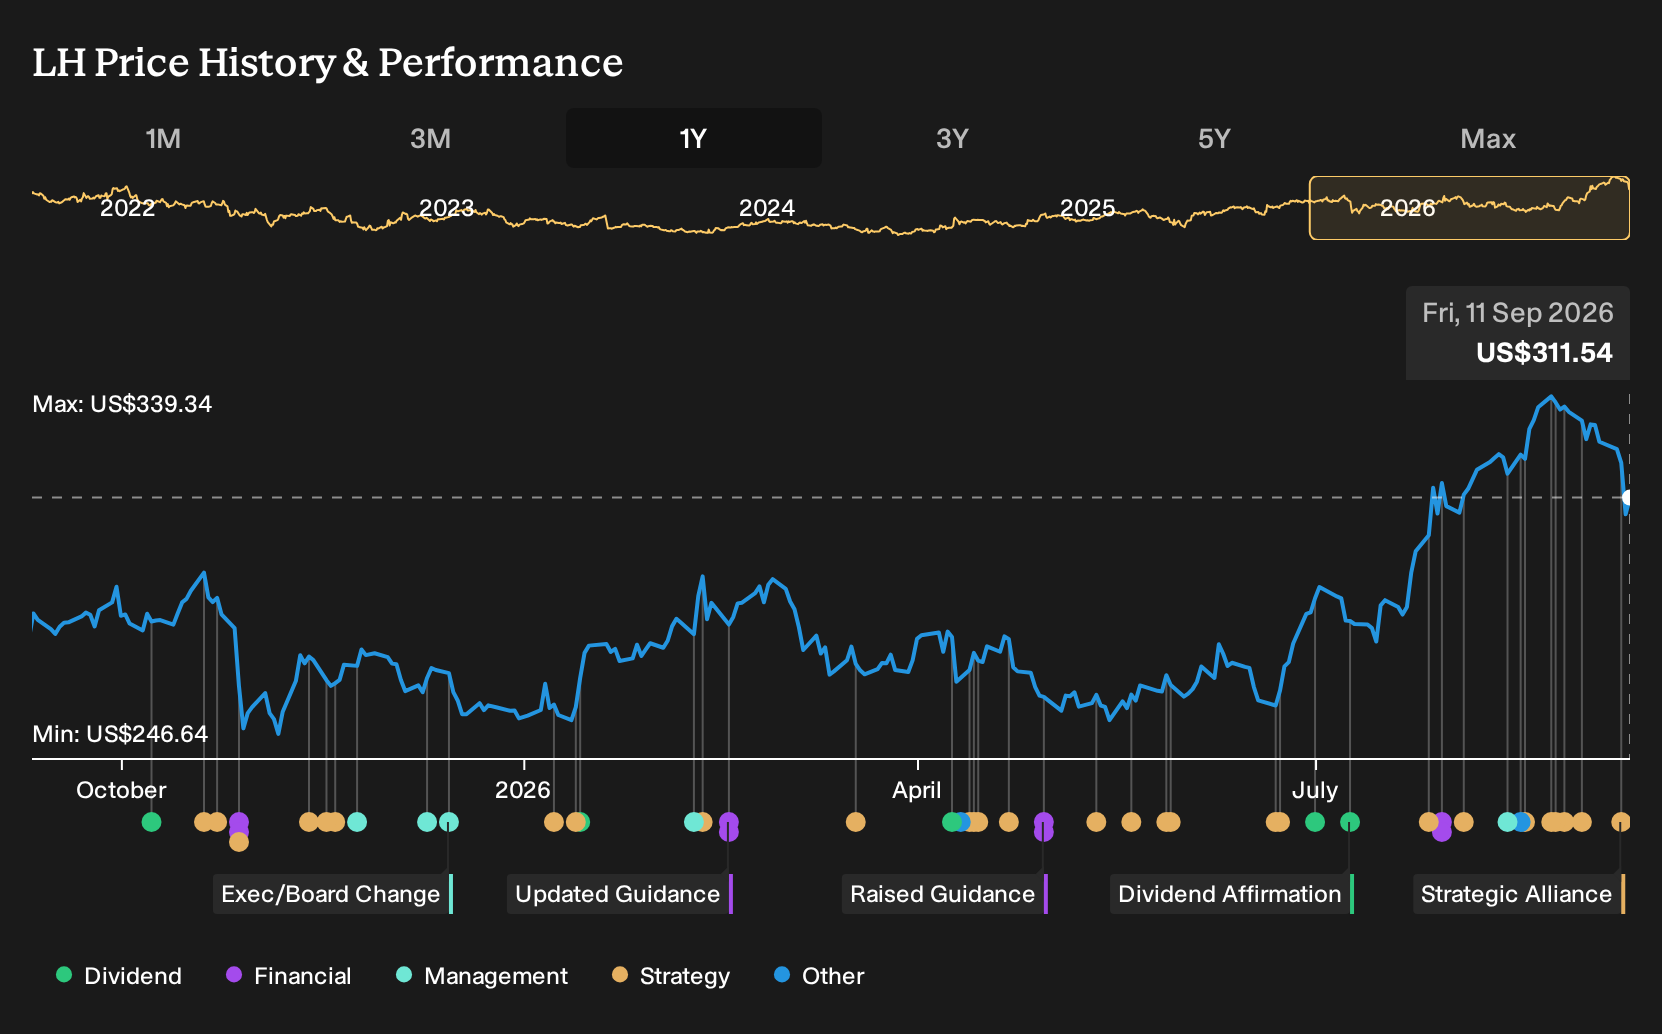
Uncover how Labcorp Holdings' fair value indicates an 8% potential upside to its current price that could narrow quickly as investors reassess Labcorp Holdings.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span roughly US$260 to US$337.75 for Labcorp Holdings, which already shows how far private views can stretch. When you set those rangebound opinions against tariff risks, PAMA uncertainty and clinical trial timing, you see why you should weigh several perspectives before acting.
Explore 2 other Labcorp Holdings fair value estimates, including one that suggests as much as 17% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Labcorp Holdings research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Labcorp Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easy to evaluate Labcorp Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond Labcorp Holdings?
Once you have a handle on Labcorp Holdings, it can help to widen the lens and compare it with other businesses that fit different risk and return profiles. The Simply Wall St Screener gives you a way to scan for stocks that match your preferred mix of balance sheet strength, income potential and upside optionality.
- If capital preservation comes first for you, start with a set of resilient businesses by reviewing 11 resilient stocks with low risk scores. These may better align with a steadier risk profile.
- Income focused investors can zero in on companies offering meaningful cash returns through 6 dividend fortresses and see which payouts fit their comfort level.
- For those hunting for mispriced opportunities, broaden your watchlist with 32 high quality undervalued stocks and compare their fundamentals with what you see at Labcorp Holdings.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com