
SES Stock and New Satellite Network Might Change The Case For Investing In SES (ENXTPA:SESG)
- SES has completed its O3b mPOWER second generation MEO constellation and launched SES CORE, a content orchestration platform that lets media customers manage delivery across satellite, fiber and IP from a single interface.
- The pairing of O3b mPOWER capacity with SES CORE’s automation and real time monitoring tools points to SES pushing harder on software driven, hybrid connectivity services for broadcasters, governments and enterprises.
- We will look at how SES's investment narrative is influenced by SES CORE’s hybrid delivery focus and the completed O3b mPOWER constellation.
SES Investment Narrative Recap
To own SES, you need to believe that multi orbit connectivity and software driven orchestration can offset pressure in legacy video and fixed data. The near term story leans heavily on executing O3b mPOWER, SES CORE and IRIS2, while keeping front loaded CapEx around €700 million in 2026 from squeezing free cash flow too hard.
The biggest short term swing factor is whether Networks, now over 66% of revenue, can absorb weaker Media and fixed data, while integration and cost measures support margins. The key risk remains an unprofitable profile with interest and dividend coverage stretched, so operational delivery matters more than this month’s headline.
The SES CORE announcement is most relevant because it links directly to how SES tries to turn expensive multi orbit assets into higher value services. A single control layer across satellite, fiber and IP aims to let broadcasters and media clients manage distribution more independently and with clearer visibility on performance and redundancy.
If SES executes well on SES CORE, it could make the O3b mPOWER build out more usable across government, mobility and media customers by simplifying service set up and monitoring. The risk is that uptake or pricing does not keep pace with investment, which would leave leverage, dividend coverage and earnings pressure unresolved.
SES’ current analyst narrative points to revenues of €3.4b and earnings of €81.6 million by 2029, based on assumed yearly top line growth of 5.1% and an earnings move of about €232.6 million from a loss of €151.0 million today into positive territory over that forecast period.
Uncover why SES' fair value indicates a 74% potential upside to its current price that could narrow quickly.
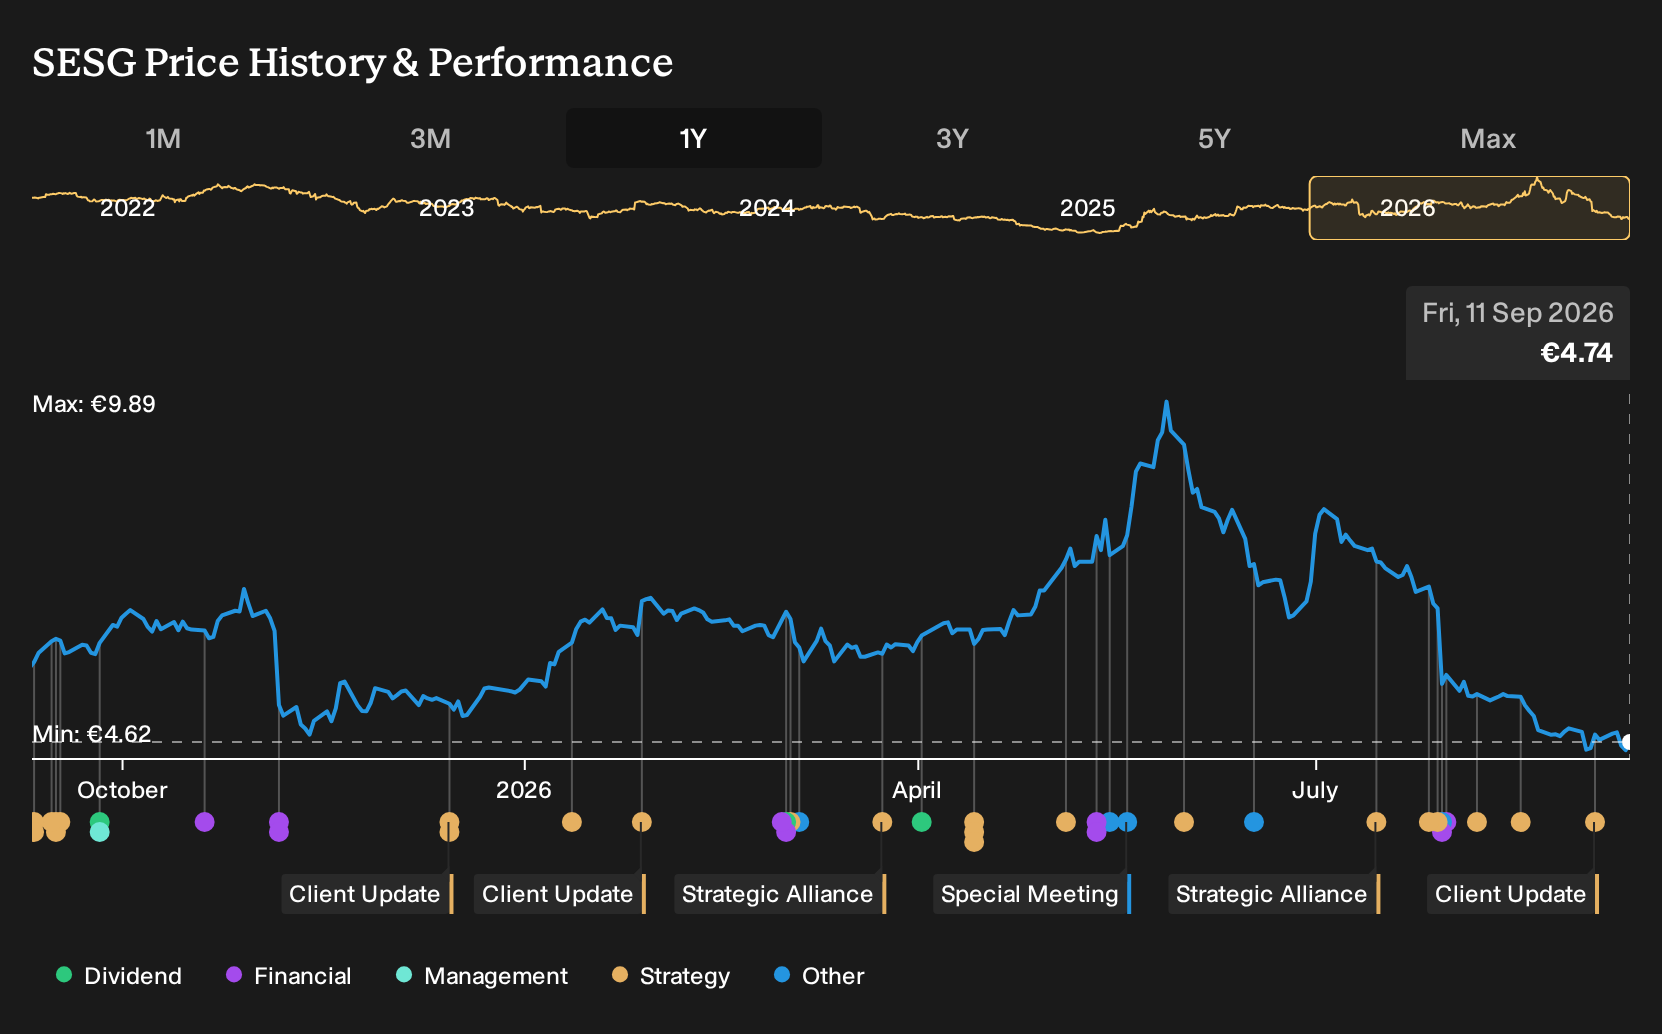
Exploring Other Perspectives
One alternate view focuses on SES CORE as a possible overbuild risk. The most cautious analysts were assuming revenue of about €3.1b and earnings of €144.1 million by 2029 before this news, with a much lower implied P/E. That group paints a tougher story, so consider using this launch as a trigger to compare several narratives yourself.
Explore 2 other SES fair value estimates, including one that suggests it could be worth just €8.06!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis.
- A great starting point for your SES research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for SES. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easy to evaluate SES' overall financial health at a glance.
Looking for more SES-sized investment ideas?
If SES has prompted fresh questions about where to allocate capital next, it can help to scan a broader field of opportunities that share some of the qualities you might be looking for in resilience, value or growth potential.
- For investors who want income to feel sturdier, consider reviewing a group of companies we see as income workhorses through the 162 dividend fortresses.
- If capital preservation is front of mind, you might prefer businesses that our models score as more resilient on risk factors, which you can filter using the 100 resilient stocks with low risk scores.
- Readers looking for a fresh idea outside the usual watchlists can cast a wider net across under followed opportunities by scanning the 617 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com