
Is New India Can Plant Altering The Investment Case For Crown Holdings (CCK)?
- Crown Holdings has broken ground on its first beverage can plant in India. The two-line Unnao facility is designed for about 2,200 million aluminum cans a year, following receipt of the official land allotment letter, with operations planned to start in the second half of 2027.
- The Unnao project signals a sizeable capacity build aimed at serving both alcoholic and non alcoholic brands in a fast expanding beverage market. The company plans to keep capital spending for the full year around US$550 million while deepening ties with the Uttar Pradesh government.
- We will explore how Crown Holdings' investment narrative intersects with this India capacity build, particularly the new Unnao beverage can facility.
Crown Holdings Investment Narrative Recap
Owning Crown Holdings means believing that demand for recyclable metal packaging and the firm’s capacity investments can offset regional softness, input cost swings, and its high debt load. The Unnao project fits that thesis, but it is unlikely to change the near term focus, which remains on keeping utilization healthy in existing beverage plants and managing aluminum costs.
The biggest near term swing factor still sits in volumes across Europe, the Americas, and Asia, where slower demand or tougher customer pricing could pressure margins that have recently improved. The main risk is that heavy capital spending, including Unnao, fails to translate into segment income and free cash flow strong enough to comfortably service leverage.
The Unnao groundbreaking ties directly into the existing catalyst around Crown Holdings investing in high growth packaging markets. Capacity additions in places like Europe and Brazil are already central to the story. India now extends that playbook into another large beverage region while management holds full year capital expenditure guidance at about US$550 million.
For shareholders, the key question is whether this extra spend supports future earnings without stretching the balance sheet. Execution on construction, customer commitments, and eventual utilization in India will matter for how effectively future cash flows cover debt and sustain buybacks and dividends that analysts currently expect to benefit from free cash flow generation.
Crown Holdings' current analyst narrative points to revenues of US$14.4b and earnings of US$937.0m by 2029, based on an assumed 2.9% yearly revenue growth rate and a move from US$784.0m of earnings today to that US$937.0m figure. This implies an earnings increase of about US$153.0m over the period.
Uncover how Crown Holdings' fair value indicates a 21% potential upside to its current price that could narrow quickly.
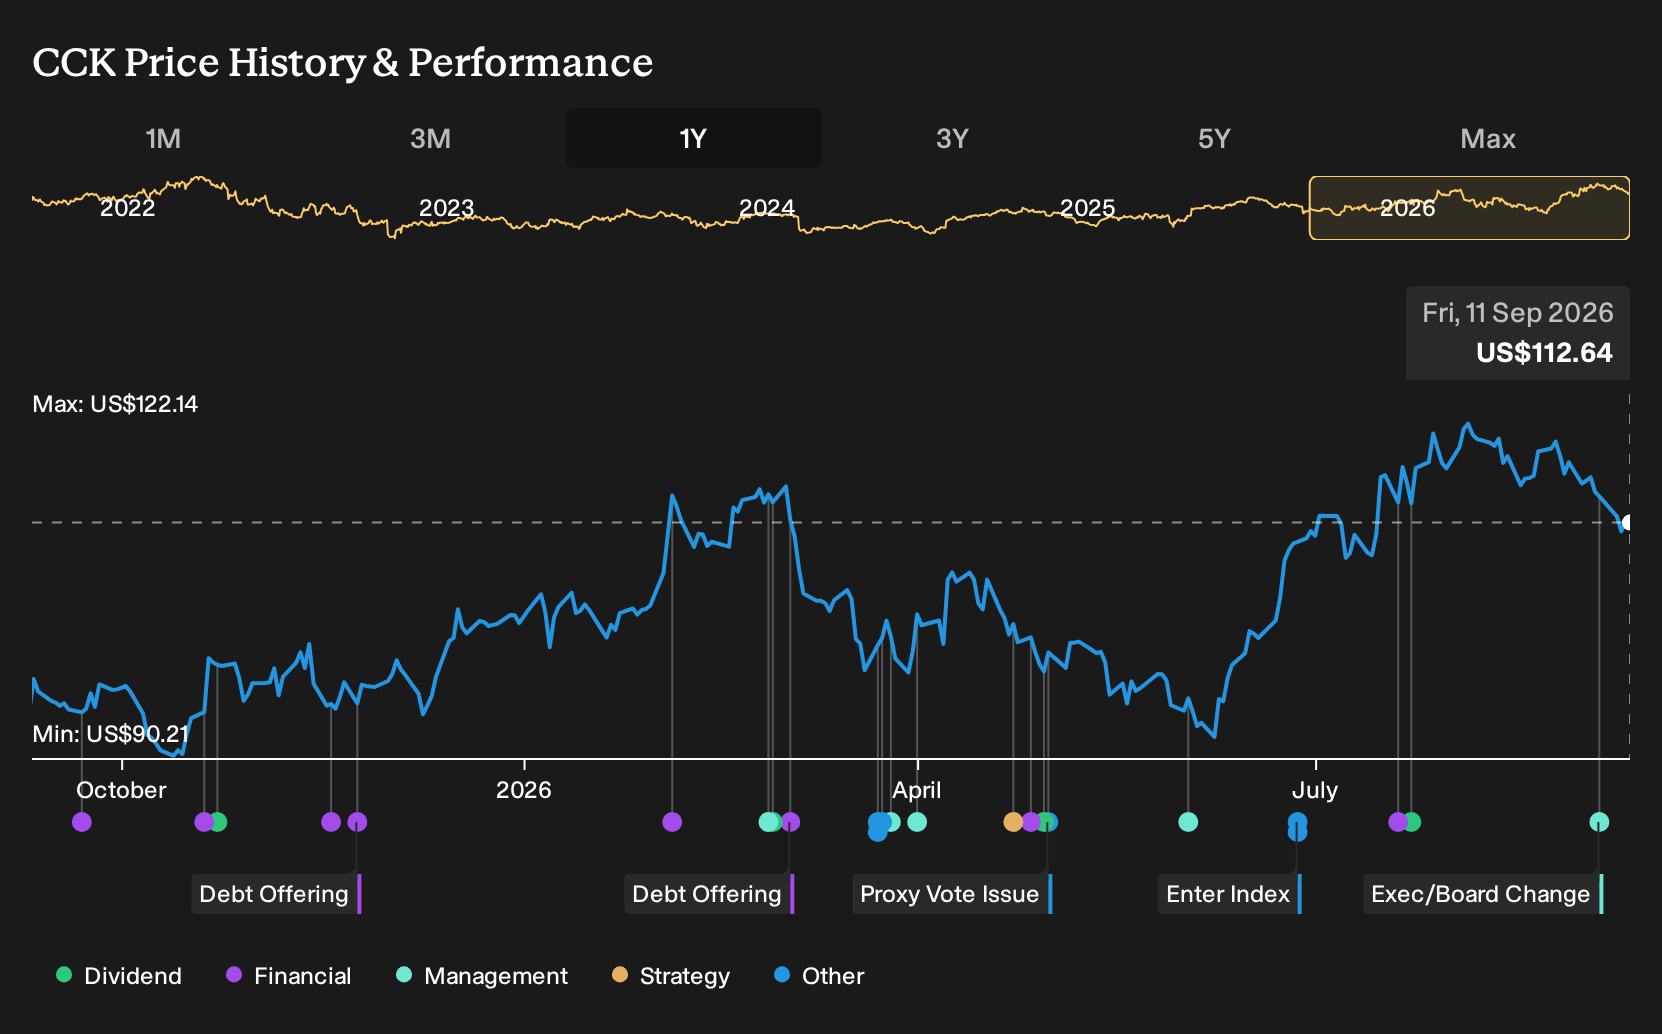
Exploring Other Perspectives
The four fair value estimates from the Simply Wall St Community range from just US$76 to about US$386.3b, so private investors clearly do not agree on what Crown Holdings is worth. Before the India expansion and upcoming general counsel retirement are fully reflected, consider how volume risk, input costs, and new capacity could reshape that debate.
Explore 3 other Crown Holdings fair value estimates, including one that suggests as much as 33% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Crown Holdings research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Crown Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Crown Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond Crown Holdings?
If Crown Holdings' India expansion has you thinking about where else capacity, balance sheet strength, and pricing power might quietly set up future returns, it can help to scan a wider set of listed businesses before making any decision.
- For investors who want quality at a sensible entry point, consider reviewing companies on the 32 high quality undervalued stocks that combine strong fundamentals with prices that analysts judge to be below their estimated worth.
- If resilience matters most for your portfolio, take a look at the 11 resilient stocks with low risk scores to focus on businesses that score well on financial stability and risk metrics.
- When the priority is financial strength and cleaner balance sheets, use the list of solid balance sheet and fundamentals (23 results) as a starting universe for companies with more robust capital structures.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com