
3 Oil And Gas Stocks With Cash Flows Tied To Global Energy Bottlenecks
Oil flows through the Strait of Hormuz have moved from background plumbing to front-page risk, and Brent crude trading above $108 per barrel has dragged the big integrated oil and gas stocks back under the spotlight. Disruptions, delayed talks and a rising geopolitical risk premium are reshaping where money may be exposed. This article walks through 3 majors from our screener that appear closely linked to this story.
The three stocks highlighted below are just a starter pack, while the full screen surfaced 26 more large integrated oil and gas majors with equally compelling narratives that are not covered here. To explore this group in greater depth, identify different risk profiles, and analyze income potential side by side, head straight to the Global Integrated Oil & Gas Majors screener.
Transportadora de Gas del Sur (BASE:TGSU2)
Transportadora de Gas del Sur plugs the screener theme from a gas angle, pairing regulated pipeline transport with liquids processing and export that tie its earnings to broader hydrocarbon pricing rather than just local Argentine demand.
Transportadora de Gas del Sur runs Argentina focused gas transportation pipelines, midstream services and a sizeable natural gas liquids export operation, with liquids and transport contributing about ARS 788 billion and ARS 725 billion respectively out of roughly ARS 1.9 trillion segment revenue, and the stock carries a market value near ARS 7.2 trillion.
"Execution of the 14 million cubic meters per day Perito Moreno expansion, with dollar-denominated, unregulated tariffs over a 15-year period, is expected to structurally lift transportation revenue and reduce earnings volatility."
What really matters for Transportadora de Gas del Sur from here is how one quiet shift in its earnings mix reshapes future pricing power and cash flow resilience.
That shift in mix is the real story. Read the full narrative for Transportadora de Gas del Sur to see how Transportadora de Gas del Sur’s tariff structure, export linkages, and risk profile are evolving.
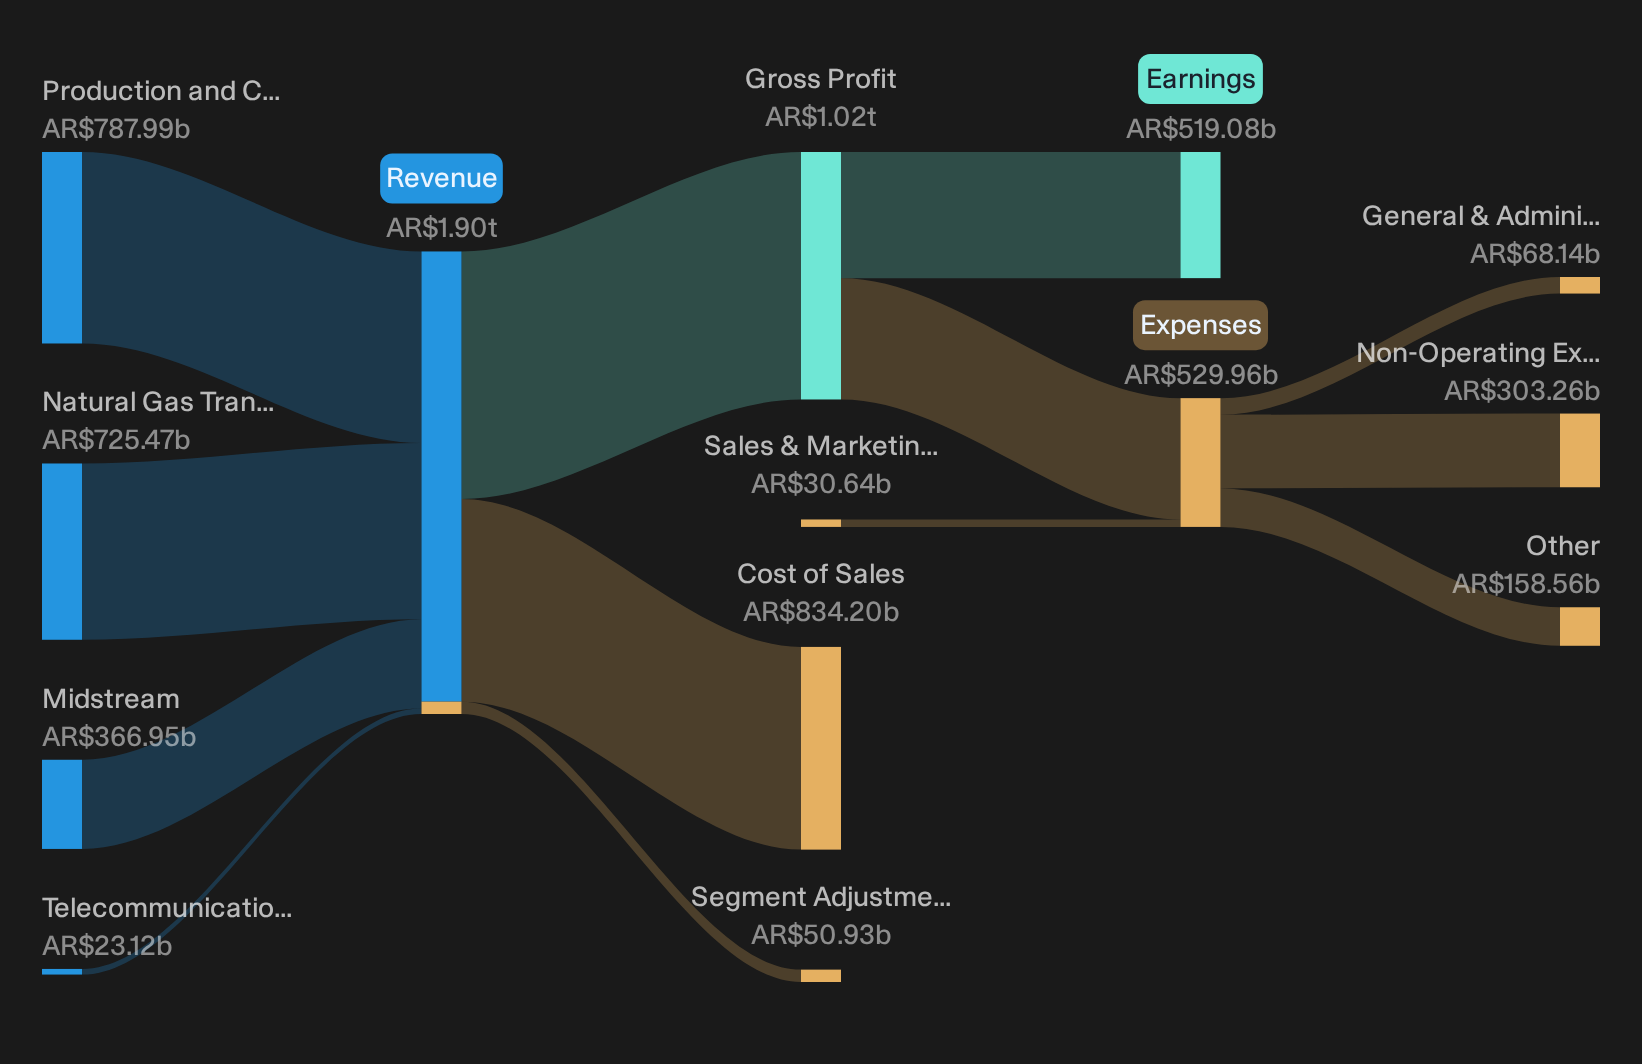
Pembina Pipeline (TSX:PPL)
Pembina Pipeline gives this screener North American midstream heft, linking oil and gas fields to storage, processing and export routes that can matter more when long haul seaborne flows look less reliable.
Pembina Pipeline runs pipelines, processing hubs and marketing operations across Western Canada, with Pipelines generating about CA$3.5b, Facilities CA$1.2b and Marketing & New Ventures around CA$4.3b in segment revenue, and the stock valued near CA$38.5b.
"Strong ongoing investments in expanding midstream and export terminal assets (notably Cedar LNG, Prince Rupert LPG terminal, and new pipeline projects) position Pembina to capture incremental volumes and diversify revenue sources, supporting both top-line growth and future EBITDA expansion."
What matters next is how one large, capital hungry project cycle ultimately filters through to fee-based cash flow strength when conditions shift.
That project cycle is only half the story. Read the full narrative for Pembina Pipeline to see how Pembina Pipeline’s capital plan, risk trade offs and income profile could be decoupling.

DT Midstream (DTM)
DT Midstream plugs directly into the Global Integrated Oil & Gas Majors theme by offering pure-play U.S. gas transport scale that can matter when global LNG and crude pricing ripple back into domestic pipeline demand.
DT Midstream runs U.S.-focused natural gas pipelines and gathering networks, with about US$710 million from Pipeline and US$613 million from Gathering, and the stock valued around US$13.1b.
"Robust, long-term growth in North American LNG exports (with DT Midstream's Haynesville system connected to facilities expecting a 16 Bcf/d demand increase by 2035) underpins high pipeline utilization and expansion needs, likely driving higher revenue and supporting sustainable EBITDA growth."
The real swing factor is how one evolving demand trend ultimately feeds through to long term contract quality and cash flow durability.
That contract shift is the real hinge. Read the full narrative for DT Midstream to see whether DT Midstream’s contracted cash flows are quietly accelerating or masking future risk.

Seeking Fresh Alternatives Beyond These Majors
Some of the sharpest breakout potential often comes from corners of the market the crowd has not fully caught yet. Before momentum flies away and information stales, consider getting in early.
- Spot under the radar income engines and shortlist high yielding businesses using the 163 dividend fortresses while payout strength and price dislocations still align. Consider acting before yields compress.
- Track early AI momentum shifts and sift through the 74 profitable AI stocks that aren't just burning cash where revenue models already support the story, so you are not chasing hype after it peaks.
- Zero in on sturdy balance sheets and scan the list of solid balance sheet and fundamentals (194 results) to find resilient operators while they are still priced like ordinary stocks, not future market leaders.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com