
Limited Bourbon Launch Might Change The Case For Investing In Brown Forman (BF.B)
- Brown-Forman has released Kentucky Boy, a one time, 100 proof, US$99.99 limited edition bourbon honoring Master Distiller Emeritus Chris Morris, curated by Elizabeth McCall and Caleb Trigo, with a portion of proceeds supporting equine nonprofit Second Stride.
- The revival of the historic Kentucky Boy label from Brown-Forman's archives ties brand heritage, premium positioning, and philanthropy into a single high profile bourbon launch that aligns with the group's focus on super premium whiskies.
- We will now look at how Brown-Forman's investment narrative could be influenced by the Kentucky Boy premium limited release.
Brown-Forman Investment Narrative Recap
To own Brown-Forman, you need to believe that premium spirits, steady earnings and a long brand history can still matter even as consumption patterns evolve. The Kentucky Boy release fits that story thematically, but it is small next to a business generating about US$3.9b in annual revenue. The more immediate swing factor remains how effectively Brown-Forman leans into premiumization while dealing with softer developed markets and mixed category demand.
The biggest short term watchpoint is execution on profitability after a recent quarter where sales and revenue were slightly lower than a year ago, but net income and EPS were higher. That points you to mix, pricing and cost discipline rather than volume as the key near term catalyst. On the risk side, high debt levels and moderation in spirits consumption leave less room for error if developed markets weaken further.
The most relevant recent datapoint for Kentucky Boy is the first quarter fiscal 2027 earnings release. Sales of US$1,181 million and revenue of US$911 million were both a touch below the prior year, while net income of US$176 million and diluted EPS of US$0.38 were higher. That combination suggests Brown-Forman is relying more on product mix and pricing than on volume to support profitability.
In that context, a one time, higher priced bourbon such as Kentucky Boy looks aligned with Brown-Forman's premium focus, even if it is not going to move consolidated numbers on its own. The product launch and the upcoming Barclays consumer staples conference appearance give management chances to reinforce the story around premium spirits, margin resilience, balance sheet risk, and how new releases support the broader earnings and dividend profile.
Brown-Forman's narrative projects US$4.1b revenue and US$811.1 million earnings by 2029, based on analyst estimates that imply 1.7% yearly revenue growth and an earnings increase of about US$96.1 million from earnings today of US$715.0 million.
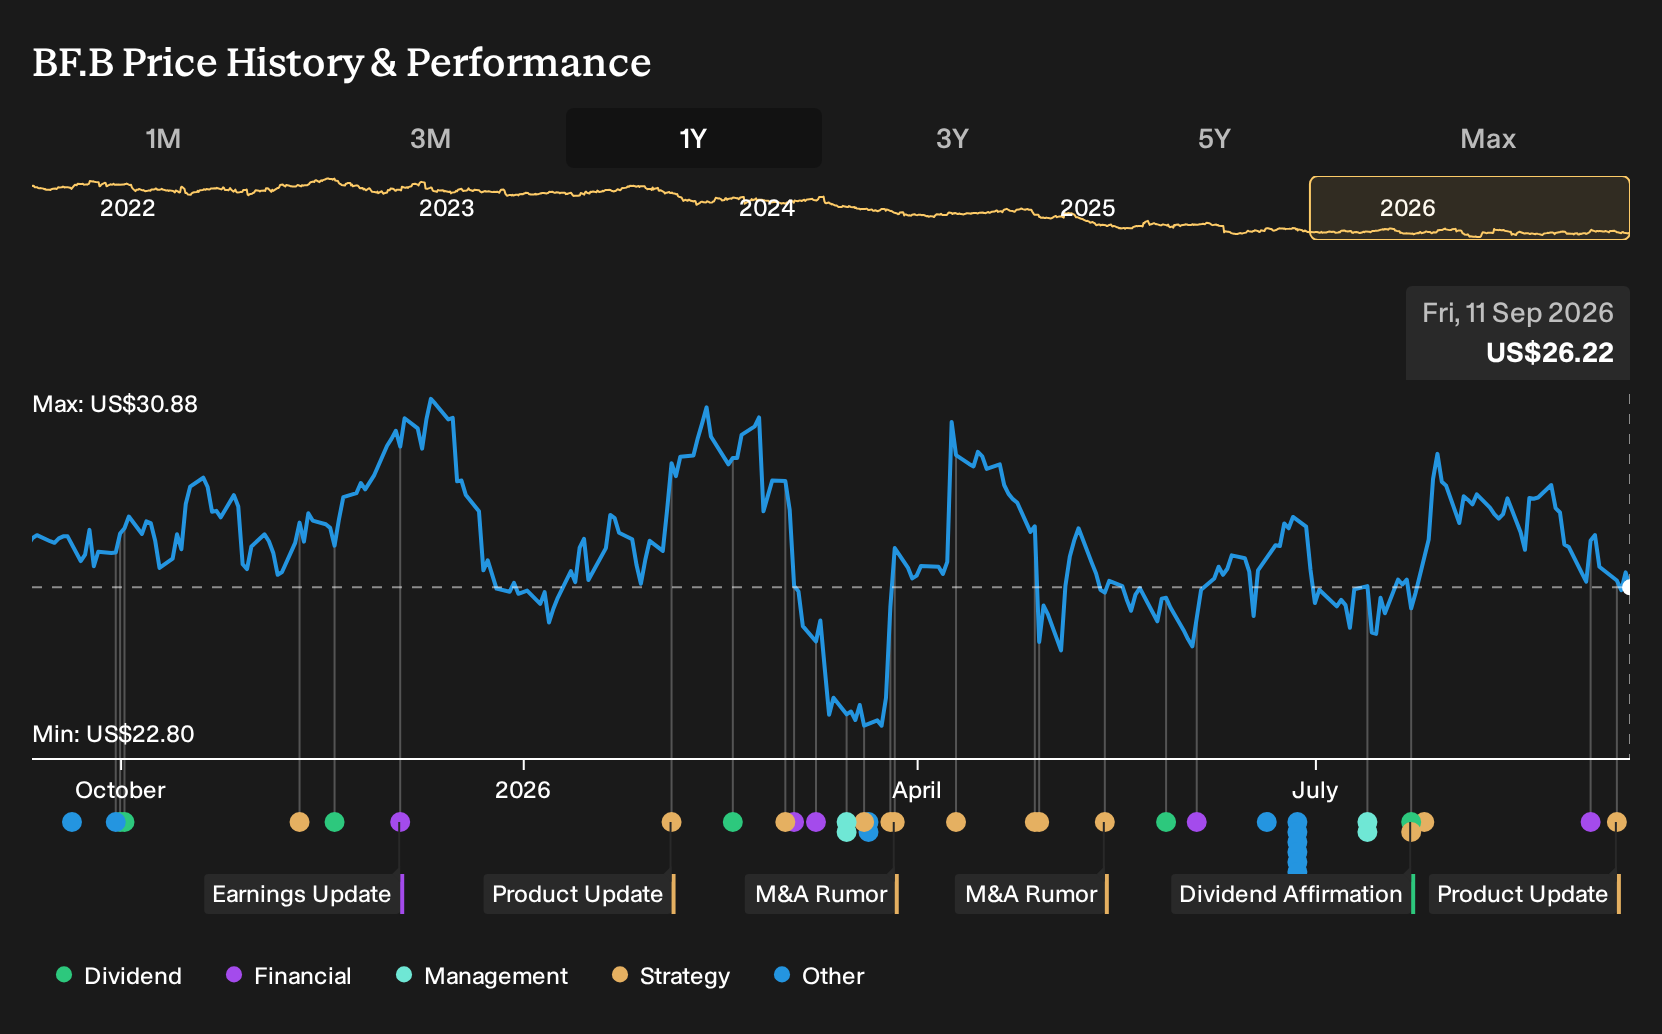
Uncover why Brown-Forman's fair value indicates a 7% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One more angle to weigh is the bullish catalyst around premiumization. The most optimistic analysts were already modeling about US$4.4b in revenue and US$874.2 million in earnings by 2029, well above consensus. Kentucky Boy could push that story further or prompt a rethink. Use this launch to compare several viewpoints before forming your own.
Explore 5 other Brown-Forman fair value estimates, including one that suggests potential upside of up to 46% from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Brown-Forman research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Brown-Forman. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Brown-Forman's overall financial health at a glance.
Looking for more investment ideas beyond Brown-Forman?
Once you have formed a view on Brown-Forman, it can help to compare that thesis with other opportunities that share similar qualities, whether you care most about value, resilience, or income. The Simply Wall St Screener lets you quickly scan and filter for stocks that match the traits you want to focus on next.
- If you are hunting for quality at a discount, start with a curated set of companies that screen as 32 high quality undervalued stocks that may warrant a closer look on valuation grounds.
- If capital preservation and balance sheet strength sit at the top of your checklist, narrow your focus using a list of solid balance sheet and fundamentals (23 results) to compare against Brown-Forman's financial position.
- If you are building an income focused portfolio, use a collection of 6 dividend fortresses that could help you stress test yield, payout ratios, and consistency across multiple stocks in minutes.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com