
Learn Why The Bull Case For Mastercard (MA) Could Change Following Wallet Pay Launch
- Mastercard recently launched Wallet Pay, a global portfolio for digital wallets that supports NFC, QR and online payments, and joined Ant International and Visa to develop shared standards for AI agents in payments.
- The combination of Wallet Pay and the Know-Your-Agent framework points to Mastercard leaning further into infrastructure that could shape how digital wallets and AI agents access its global acceptance network.
- We will now examine how Mastercard's push into interoperable wallets and AI agent standards could influence the broader investment narrative.
Mastercard Investment Narrative Recap
To own Mastercard, you need to believe the shift to digital payments, e-commerce and value added services continues to create room for more volume and high margin services on its network. The key near term swing factor remains how consistently the firm can turn that opportunity into mid teens type earnings progress while carrying a high P/E and meaningful debt.
The recent Wallet Pay and AI agent frameworks look more like long runway infrastructure than an immediate earnings needle mover. Near term, the bigger risk still sits with regulatory pressure, domestic real time schemes and incentive heavy renewal battles with large issuing partners that could compress pricing or make results choppier.
The Know Your Agent collaboration with Ant International and Visa is the clearest bridge between Mastercard’s current business and the agentic commerce theme. It aims to make AI driven transactions easier to onboard and monitor across ecosystems, which speaks directly to how the firm could stay embedded in commerce if AI agents handle more checkout decisions.
For you as an investor, the interest is less about hype and more about plumbing. If agentic commerce grows from today’s very small base, a shared KYA framework can help keep transactions on card rails, support value added fraud and identity services, and reduce integration friction for merchants, while still carrying execution risk if alternative rails win more share.
Mastercard's narrative projects US$50.0b revenue and US$23.3b earnings by 2029. This is based on an assumed 12.5% yearly revenue growth and an earnings increase of about US$7.0b from US$16.3b today.
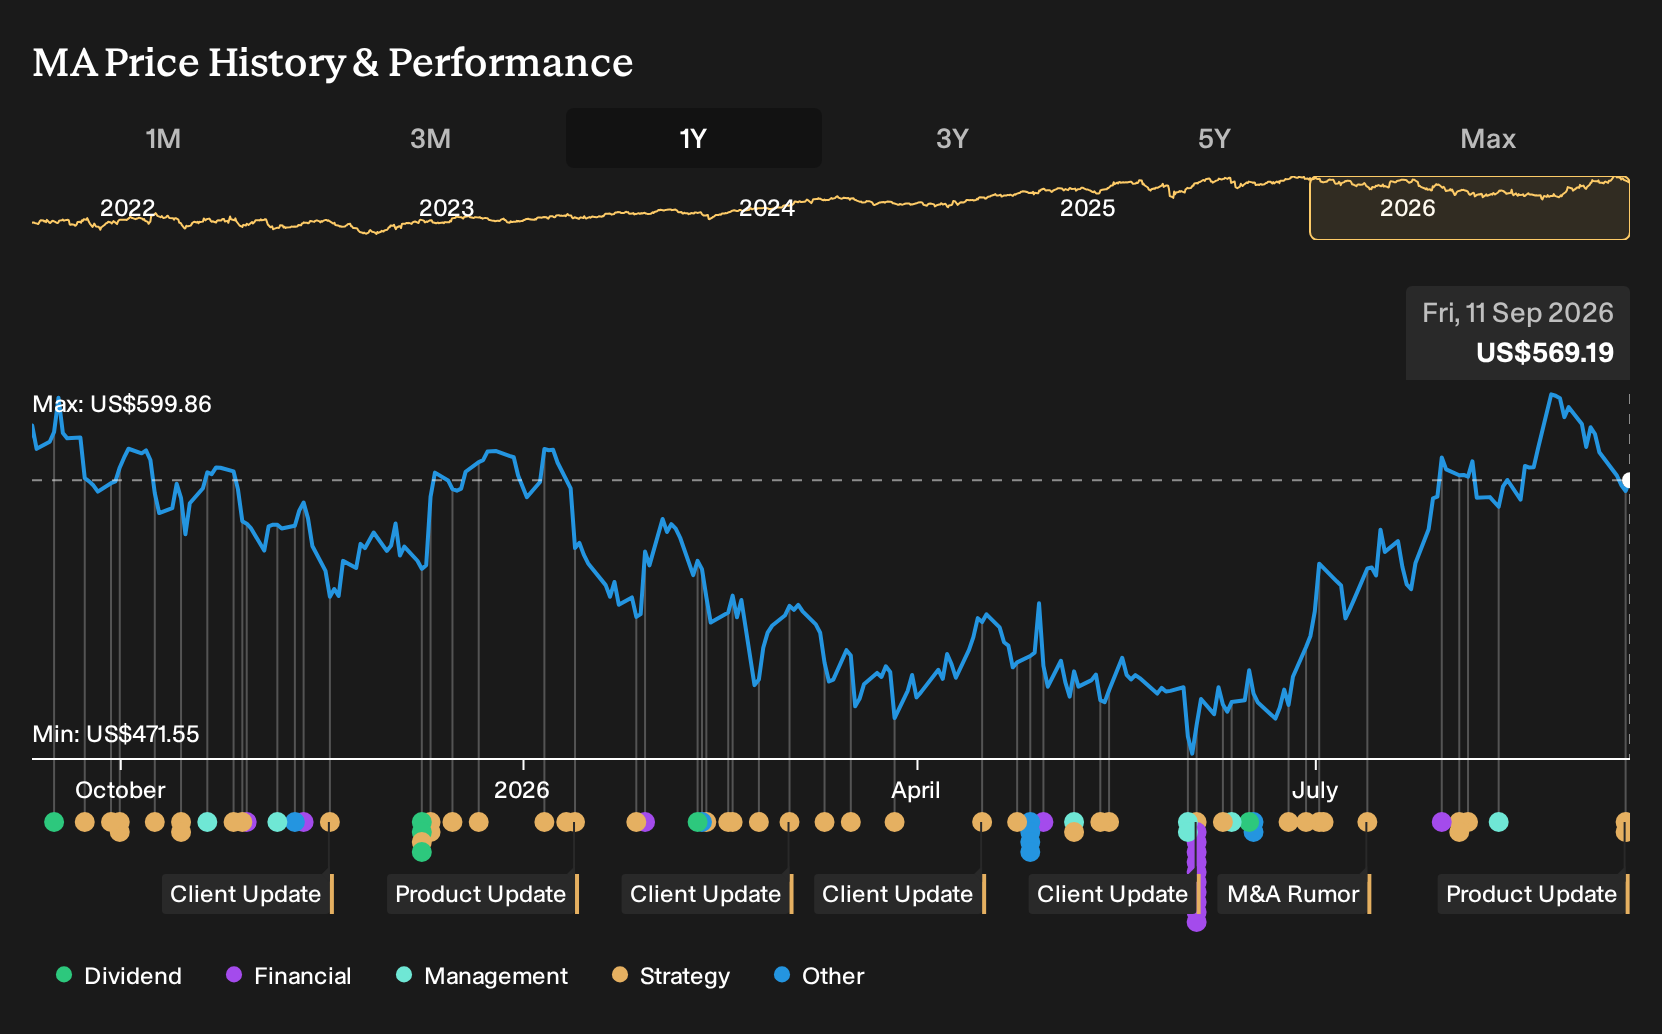
Uncover why Mastercard's fair value indicates a 17% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
The Simply Wall St Community offers 22 fair value views on Mastercard, ranging from US$520 to about US$1,091, so opinions stretch from deep discount territory to rich pricing. Set that against risks around local real time schemes and regulation, and you get a wide debate that is worth exploring before forming your own stance.
Explore 21 other Mastercard fair value estimates, including one that suggests a potential 92% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Mastercard research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Mastercard. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Mastercard's overall financial health at a glance.
Looking For More Ideas Beyond Mastercard?
If you want to pressure test your Mastercard thesis against other opportunities, the Simply Wall St Screener is a useful way to line up companies with different risk and reward profiles and see how they stack up on the same metrics.
- For investors who care most about quality and price discipline, scan a curated set of 32 high quality undervalued stocks that combine strong fundamentals with more modest expectations baked into the share price.
- If reliability and capital preservation sit higher on your priority list, focus on a 11 resilient stocks with low risk scores that screens for businesses with sturdier balance sheets and fewer red flags in the risk profile.
- Those hunting for underfollowed opportunities can broaden their watchlist with a 15 high quality undiscovered gems that highlights financially solid companies receiving less market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com