
Sensient Technologies (SXT) Pulls Back After A Strong Run, Is It Still Below Fair Value?
Sensient Technologies (SXT) has drawn fresh attention after recent share price pressure, with the stock down 4.6% over the past week and 3.6% over the past month despite strong year to date gains.
The recent pullback comes after a strong run, with Sensient Technologies posting a 37.6% year to date share price return. Its 1 year total shareholder return of 22.7% and 3 year total shareholder return of about 2.1x suggest longer term holders have already seen substantial gains.
Scan Sensient Technologies against a curated 32 high quality undervalued stocks list that have also come under pressure after strong runs and see how this pullback compares.
Sensient Technologies now looks like a strong ingredients business whose share price has sprinted ahead, then paused. After this pullback, are you paying up for quality or getting that quality at a fair entry point?
Most Popular Narrative: 9.9% Undervalued
On the most followed narrative, Sensient Technologies screens below its fair value estimate of $142.80 versus the last close at $128.60. This puts the recent pullback against a much richer long term story.
Sensient's 15+ years of proactive investment in natural colors R&D, global manufacturing capacity, and a vertically integrated botanical supply chain gives it a defensible advantage in meeting escalating consumer and CPG demand for clean-label, natural ingredients that support sustainable growth and premium pricing, which may enhance both revenue and gross margins.
Want to see what that edge is worth in numbers? The narrative focuses on faster earnings compounding, fatter margins, and a rich profit multiple. Curious which assumptions do the heavy lifting?
Result: Fair Value of $142.80 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, the whole Sensient Technologies narrative can wobble if agricultural inputs remain volatile or if heavy capital spending fails to translate into the expected earnings power.
Find out about the key risks to this Sensient Technologies narrative.
Another View: What Multiples Say About Sensient Technologies
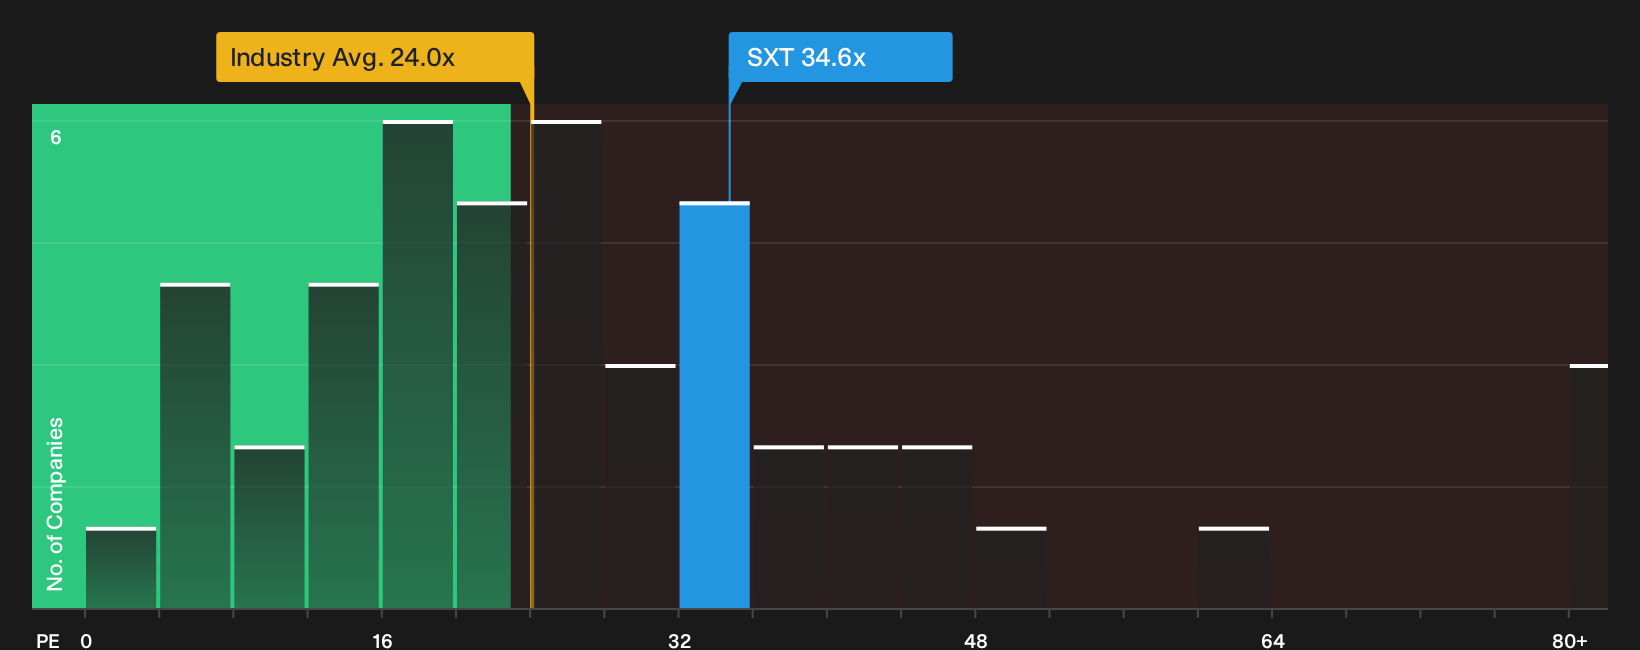
The story changes when you stop looking at fair value models and check what the current P/E is saying. Sensient Technologies trades on 34.6x earnings, above both the US Chemicals sector at 24x and its peer group around 30.5x, while the fair ratio sits lower at 23.2x. That gap points to valuation risk if sentiment cools or growth expectations ease.
For investors who prefer to anchor on earnings multiples rather than narratives, this raises an obvious question: Is the premium price a reasonable trade off for the perceived quality of Sensient Technologies, or is it asking you to pay too much for a good story?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Sensient Technologies story so far. If you want to move quickly and form your own view, start by weighing the 3 key rewards and 1 important warning sign.
Looking for more Sensient Technologies sized ideas?
Do not stop at Sensient Technologies. Use this moment to refresh your watchlist with fresh opportunities that match your risk, income, and quality preferences.
- Target potential mispricings by scanning a curated 32 high quality undervalued stocks that highlights companies with strong fundamentals trading below their assessed worth.
- Lock in income-focused ideas by reviewing a handpicked 6 dividend fortresses that screens for higher yielding payouts with supporting financial metrics.
- Strengthen portfolio resilience by filtering through a 11 resilient stocks with low risk scores that focuses on businesses with sturdier balance sheets and lower risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com