
Why Oji Holdings (TSE:3861) Is Getting Fresh Attention
Oji Holdings (TSE:3861) has been drawing fresh attention after recent share price moves and updated fundamental data, prompting investors to reassess how its pulp, paper, and materials businesses are currently valued.
Recent trading has been mixed for Oji Holdings, with the share price edging up 0.86% over the last session but still down over the year to date. However, a 90-day share price return of 8.78% and a 1-year total shareholder return of 8.84% suggest momentum has been firmer over the medium term than in the very short run.
Scan how Oji Holdings compares with other material stocks that show similar medium term momentum and fundamentals by working through the hand picked 16 high quality undervalued stocks list.
Bulls see Oji Holdings as a steady cash generator that the market still prices cautiously. Bears point to modest growth and a limited discount. Which side do the current valuation numbers lean toward?
Price-to-Earnings of 11.5x: Is it justified?
On the surface, Oji Holdings looks modestly priced, with a P/E of 11.5x at a last close of ¥867.3, compared with richer valuations across peers and the wider JP market.
The P/E ratio links what investors pay today to the earnings the group currently produces. For a mature pulp, paper, and materials business with steady but not rapid profit forecasts, this kind of metric often carries more weight than top line focused measures such as P/S.
Analysts see earnings growing, but not rapidly, and forecast Return on Equity around the mid single digits. That combination implies the market is not paying up for aggressive profit expansion. Instead, the current multiple suggests expectations anchored to moderate profitability and a business that investors view as solid but not especially high return.
Compared with the Asian Forestry industry average P/E of 15.5x and a peer group around 17.8x, Oji Holdings trades on a marked discount. The fair P/E estimate of 14x indicates potential for the valuation multiple to move closer to levels implied by its own earnings profile rather than the current lower band.
Explore the SWS fair ratio for Oji Holdings
Result: Price-to-Earnings of 11.5x (UNDERVALUED).
Still, the case for Oji Holdings can weaken quickly if modest revenue and net income growth stall or if its broad materials portfolio faces sustained pricing pressure.
Find out about the key risks to this Oji Holdings narrative.
Another View on Oji Holdings Using DCF
The picture looks different when switching from the P/E lens to our DCF model. On this approach, Oji Holdings at ¥867.3 trades above an estimated future cash flow value of ¥770.58. That points to an overvalued signal rather than a bargain multiple. Which yardstick should carry more weight for you?
For a closer look at how this cash flow view is built and what assumptions sit underneath it, take a moment with the Look into how the SWS DCF model arrives at its fair value.
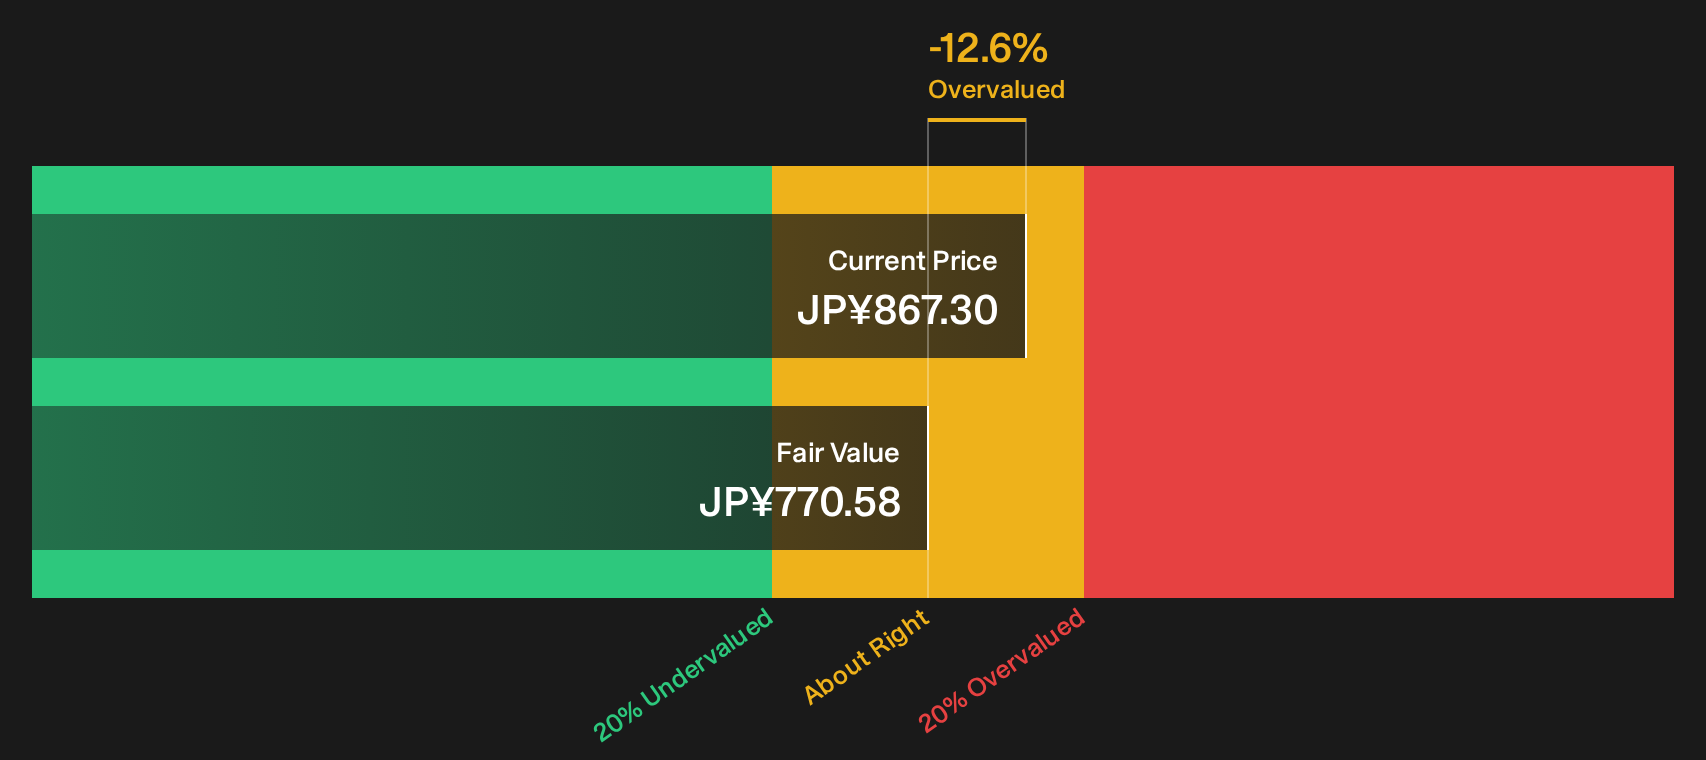
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Oji Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 16 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals or a clear message on Oji Holdings, it is important to look closely at both the concerns and the bright spots. Act quickly, review the full spread of risks and potential upsides, and ground your own stance in the 4 key rewards and 3 important warning signs
Looking for more investment ideas beyond Oji Holdings?
If Oji Holdings has sharpened your focus on valuation and quality, you can widen your watchlist now with a few targeted idea lists built from the Simply Wall St screener.
- Target quality at a discount by scanning companies that score well on fundamentals yet still trade on restrained expectations through the 16 high quality undervalued stocks.
- Strengthen your income stream by reviewing businesses with higher yields and resilience profiles using the 19 dividend fortresses.
- Dial down portfolio risk by filtering for companies with sturdier finances and healthier balance sheets via the list of solid balance sheet and fundamentals (19 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com