
Albertsons (ACI) Stock Trades At A Premium On Earnings Despite A 44% Slide
Albertsons Companies has delivered weak share performance over the past few years, yet the stock still screens as expensive on most valuation checks. That mix of a falling price and an overvalued signal raises questions about whether recent news around leadership and regulatory scrutiny is fully reflected in what investors are paying today.
- Over the past 3 years, Albertsons Companies shareholders have seen the price decline about 44%, which suggests confidence in the story has already softened.
- Meg Whitman’s appointment as Executive Chair may support expectations for better execution and use of technology, while the Department of Justice probe into beef pricing practices could weigh on how investors view long term profitability and risk.
- The broader valuation framework, where Albertsons Companies scores 2 out of 6, leans toward the stock being expensive rather than a clear bargain.
The issue now is whether Albertsons Companies is already pricing in too much improvement in operations and risk management after a large multi year share price decline.
Compare Albertsons Companies with other retailers that pair falling share prices with richer valuation signals by scanning 31 high quality undervalued stocks for potential alternatives.
Has Albertsons Companies Run Too Far on Earnings?
P/E works well for a mature, cash generative retailer like Albertsons Companies because earnings are a key anchor for what investors are willing to pay.
On this yardstick, the current P/E of about 89.2x sits far above the Consumer Retailing industry average of 17.9x and the peer group on roughly 16.0x. The fair P/E ratio implied by Simply Wall St’s model is 32.8x, which already reflects the company’s specific mix of growth prospects, margins, size and risk. At today’s level, the market is paying a large premium to that tailored benchmark, not just a small uplift for quality.
Meg Whitman’s arrival as Executive Chair may be shaping expectations for better execution and technology use, yet the earnings multiple already includes a rich set of expectations compared with sector norms.
On the P/E multiple, Albertsons Companies stock appears clearly overvalued relative to what the underlying earnings profile would usually support.
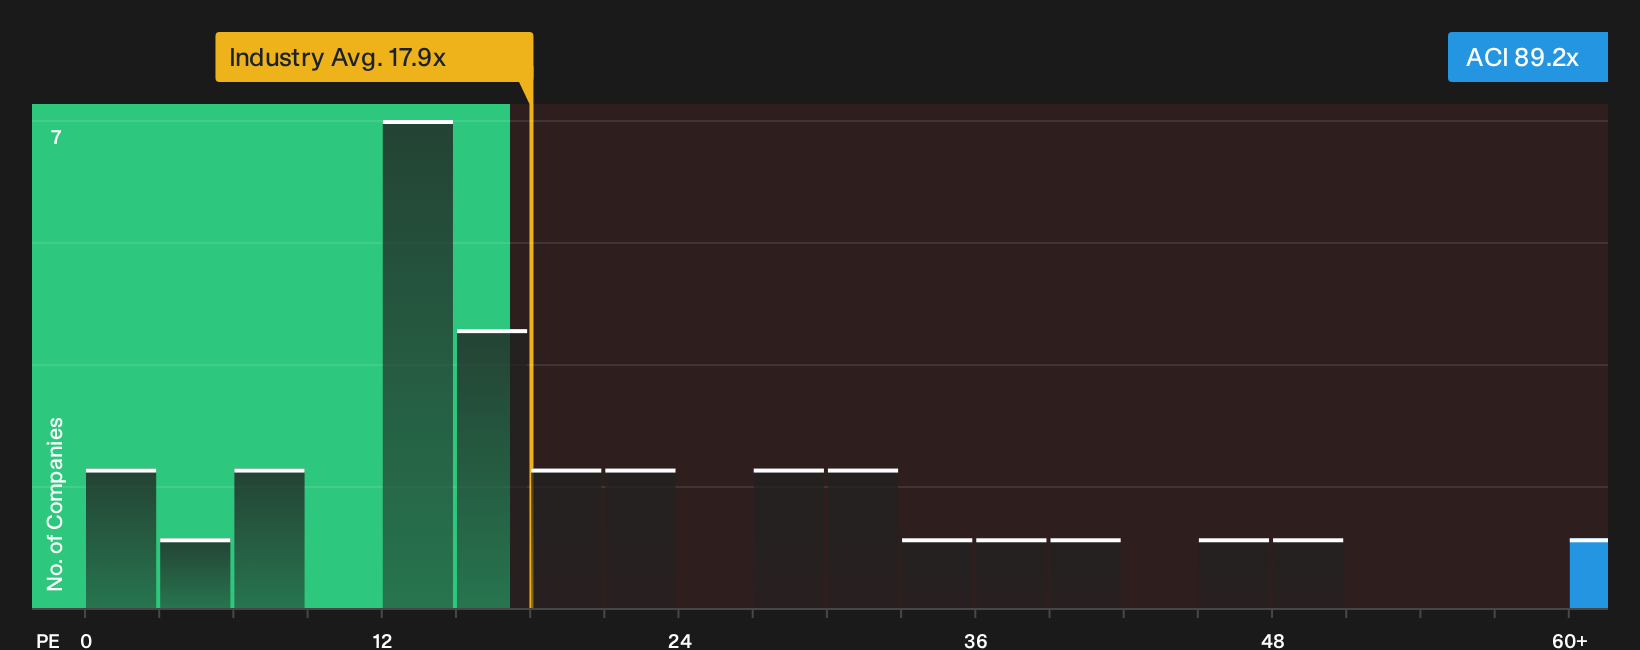
See what the numbers say about this price — find out in our valuation breakdown.
The Albertsons Companies Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Albertsons Companies valuation puzzle leaves off and explain which future paths for growth, margins and earnings would need to occur for the stock to be worth materially more or less than today’s price, based on scenarios shared on the Community page. Each Narrative links a specific fair value estimate to a particular storyline about Albertsons Companies' potential catalysts and key risks so you can track over time which version of events appears to be taking shape.
Community views on Albertsons Companies split sharply between a restructuring story with upside and a reset that still looks too rich.
Bull case: 15% undervalued
"Modernization through technology investments, such as automation, AI-driven inventory/pricing, and centralized buying, are streamlining operations, reducing labor and supply chain costs..."
Read the full Bull Case to see why Albertsons Companies could be undervalued
Bear case: 21% overvalued
"Albertsons forecasts same-store sales growth of only 1.5% to 2.5%, reflecting muted revenue expectations potentially due to the competitive environment and cautious consumer spending trends..."
Read the full Bear Case to see why Albertsons Companies could be overvalued
Do you think there's more to the story for Albertsons Companies? Head over to our Community to see what others are saying!
The Bottom Line
Albertsons Companies screens as overvalued on earnings, with the market already paying a premium to sector norms for its current profit profile. That gap can close in two ways. Either execution, technology use and risk management improve enough to grow into this richer multiple, or expectations cool and the P/E drifts closer to peers. The key question for investors now is whether future margins and cash generation will ultimately justify paying so much more for Albertsons Companies than for other retailers with similar characteristics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com