
Ambarella (AMBA) Stock Could Be Cheap Despite Its 55% Slump
Ambarella presents a tricky setup for valuation focused investors right now, with a Discounted Cash Flow (DCF) estimate pointing to upside relative to the current share price, while market based multiples paint the stock as expensive and the long term return record remains weak.
- The share price has fallen 54.8% over the past 5 years, which signals that long term holders have faced a difficult ride despite recent news driven interest.
- Partnerships with Capgemini and Macnica can support expectations for stronger edge AI adoption and revenue over time, while reliance on a relatively narrow set of edge AI use cases may limit how quickly cash flows materialize.
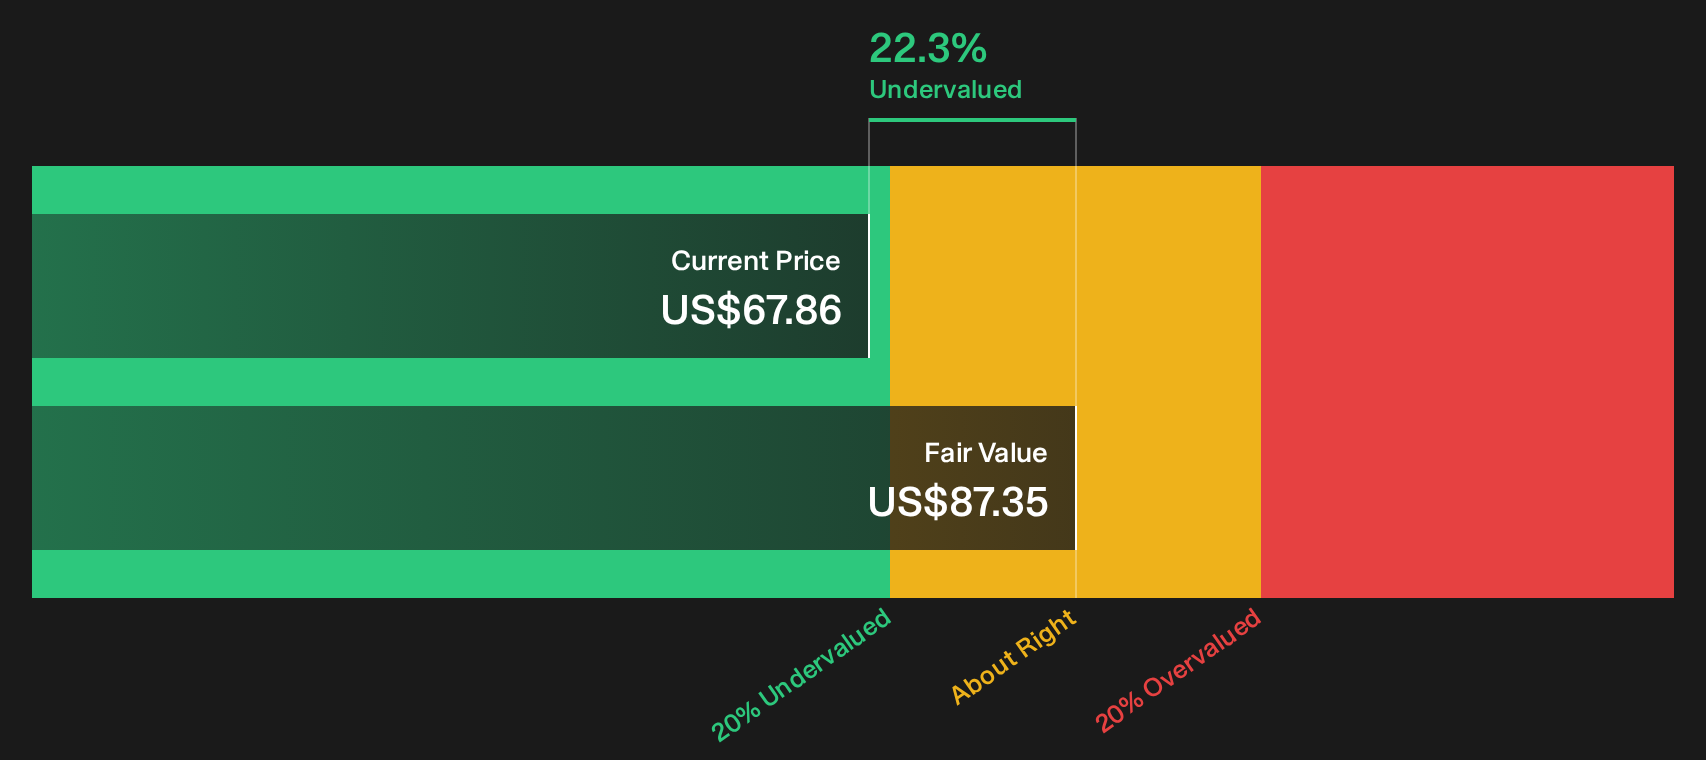
- The low value score of 2 out of 6 suggests Ambarella does not screen as a clear bargain on the broader checklist, even though the DCF implies the shares trade roughly 22.3% below intrinsic value.
The issue now is whether the DCF based intrinsic value or the richer looking trading multiples offer the more reliable guide to what Ambarella is really worth today.
Spot undervalued edge AI opportunities by comparing Ambarella with 89 AI infrastructure stocks.Does Ambarella Look Undervalued on Cash Flow?
The Discounted Cash Flow model here works by projecting Ambarella’s future free cash flows and discounting them back to today in dollar terms. For the latest twelve months, Ambarella generated about $10 million of free cash flow, and the model assumes that this base eventually shifts into a growing stream of cash tied to broader edge AI adoption.
On those assumptions, the 2 Stage Free Cash Flow to Equity approach arrives at an intrinsic value of about $87 per share, which is roughly 22.3% above where the stock changes hands today. Ambarella’s partnerships with Capgemini and Macnica help explain why the cash flow profile in the model leans toward recovery and growth rather than permanent stagnation, even though the timing of that ramp remains uncertain.
On balance, the Discounted Cash Flow output indicates that Ambarella stock appears undervalued relative to what its projected cash generation supports.
Our Discounted Cash Flow (DCF) analysis suggests Ambarella is undervalued by 22.3%. Track this in your watchlist or portfolio, or discover 31 more high quality undervalued stocks.
Is Ambarella Getting Expensive on Sales?
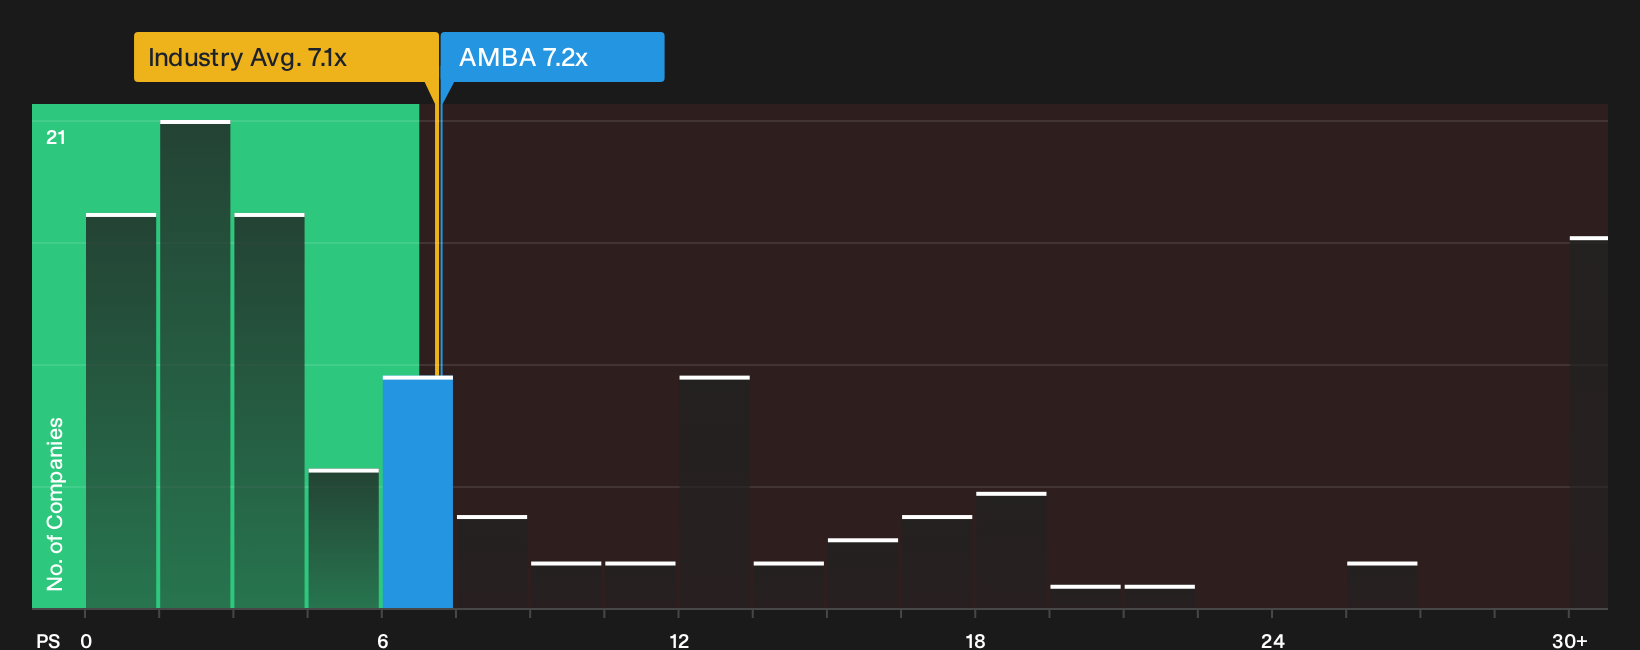
P/S is the cleaner lens for Ambarella right now, because revenue is positive while earnings are still in loss-making territory.
The stock trades on a P/S of about 7.2x, which is very close to the broader semiconductor industry average of roughly 7.1x. Against a peer group that sits nearer 4.4x, Ambarella carries a clear premium, which suggests investors are already paying up for its edge AI positioning and partnerships.
The modelled fair P/S ratio for Ambarella is about 5.4x, which is lower than where the shares trade today. That gap signals the current price implies richer terms than the combination of growth profile, margins, size and risk would typically support within this framework.
On this P/S yardstick, Ambarella stock appears overvalued relative to what the fundamentals in this model would justify.
See what the numbers say about this price — find out in our valuation breakdown.
The Ambarella Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Ambarella pick up where this valuation puzzle leaves off and explain which assumptions on growth, margins and future earnings would need to occur for the stock to be worth materially more or less than today's price. Each narrative links a specific fair value to a clear storyline about Ambarella's potential catalysts and key risks so you can track over time which version of events is actually unfolding on the Community page.
One of the top community narratives on Ambarella: 24% undervalued
"Sharply increasing demand for AI-powered edge devices, including portable video, robotics and edge infrastructure, has led to a rapid expansion of Ambarella's addressable markets..."
Read one of the top narratives on Ambarella
Do you think there's more to the story for Ambarella? Head over to our Community to see what others are saying!
The Bottom Line
Ambarella’s Discounted Cash Flow (DCF) estimate points to meaningful upside, while the sales based multiple flags the shares as overvalued relative to peers. That split comes from one framework leaning on future cash generation and funding needs, and the other leaning on what investors already pay for growth, sentiment and comparable chips. Broader valuation checks are not especially supportive, so the bullish case rests on edge AI demand turning projected cash flows into reality within a reasonable timeframe. The key issue from here is whether Ambarella can convert its partnerships and product pipeline into profitable scale before the current valuation premium feels overextended.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com