
Valero (VLO) Stock Looks Above Fair Value On Its Big Five Year Run
Valero Energy stock has delivered very strong gains over the past five years, yet the current market price screens as expensive when compared with intrinsic value estimates and broader valuation checks. For anyone looking at Valero Energy today, the question is less about recent performance and more about what investors are now paying for each dollar of future cash flow.
- The share price has produced a very large return over 5 years, which puts extra focus on whether the recent run already reflects the bulk of the company’s fundamentals.
- Future cash generation and refinery profitability can support the current share price, while any pressure on refining margins or cash flow visibility may weigh heavily on what investors are willing to pay.
- The broader toolkit of valuation checks points to overvaluation, and the value score, which is 0 of 6 checks passing, suggests Valero Energy does not screen as a clear bargain right now.
The key issue is whether the current premium to the Discounted Cash Flow intrinsic value estimate leaves enough room for error if conditions become less supportive for Valero Energy.
Scan beyond Valero Energy's sharp multi year gains and stress test your ideas against our hand picked list of 31 high quality undervalued stocks.
Has Valero Energy Run Too Far on Cash Flow?
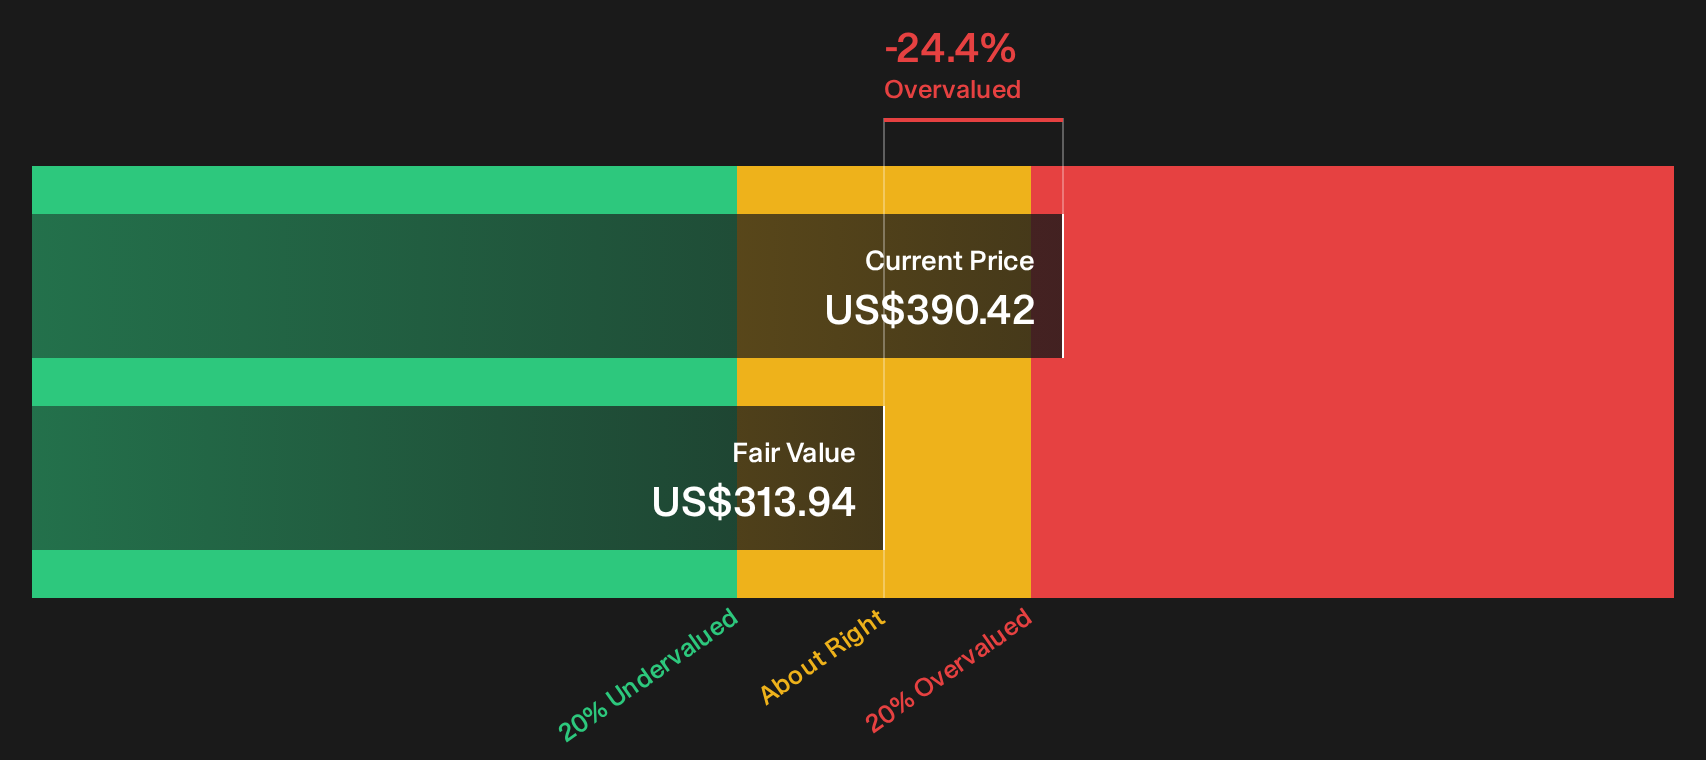
The Discounted Cash Flow (DCF) model here is built on projected free cash generation rather than headline earnings. Valero Energy has produced about $10.02b in free cash flow over the last twelve months, which is a hefty base. The DCF framework assumes cash flows ease back from that level over time rather than climb, reflecting a pattern of declining projections through the next decade.
On those cash flow assumptions, the model arrives at an estimated intrinsic value of about $314 per share. Compared with the current market price, the DCF output implies the stock trades at roughly a 24.4% premium. That gap suggests investors are already paying up for Valero Energy, with expectations that run ahead of what the cash flow projections alone would support.
On this DCF view, Valero Energy stock currently screens as overvalued.
Our Discounted Cash Flow (DCF) analysis suggests Valero Energy may be overvalued by 24.4%. Discover 31 high quality undervalued stocks or create your own screener to find better value opportunities.
Does Valero Energy Look Pricey on Earnings?
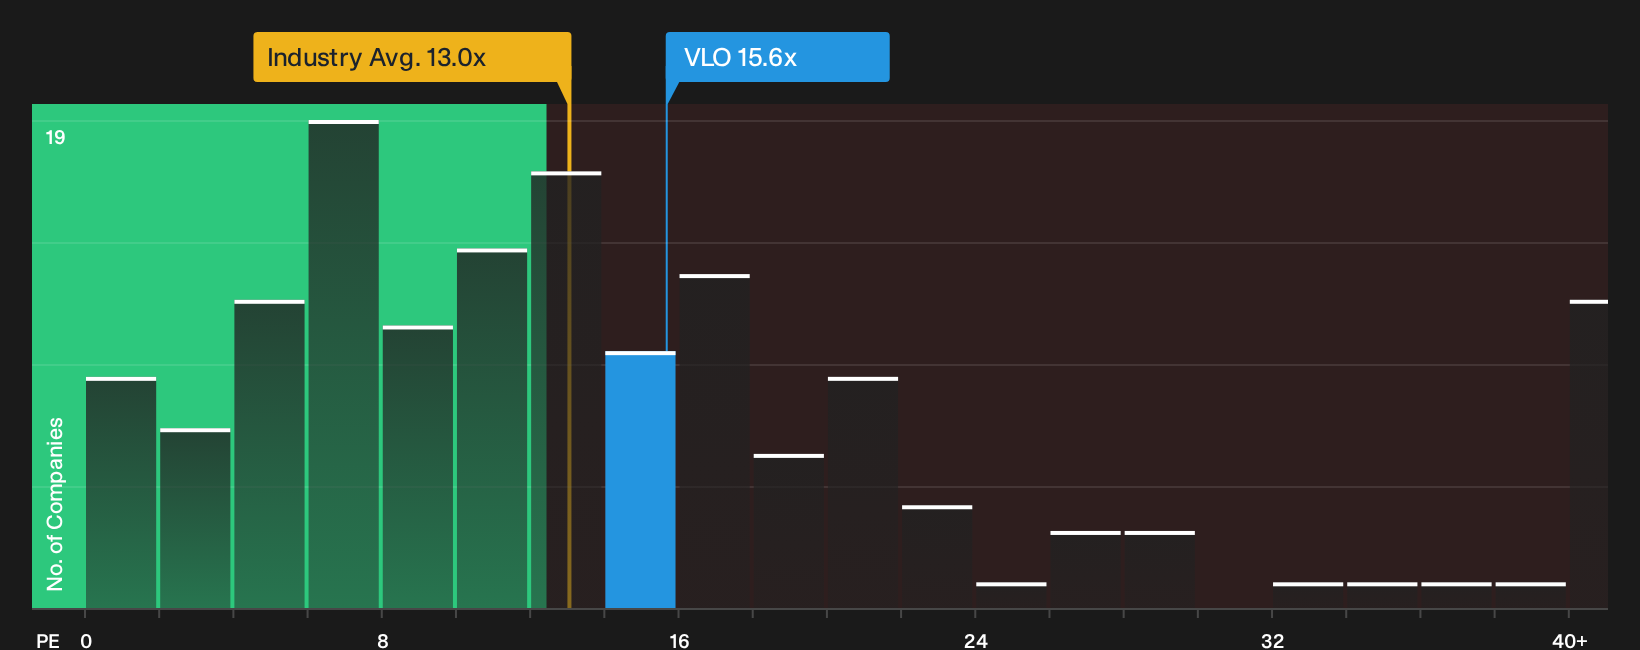
The P/E ratio works well for Valero Energy because earnings are a primary yardstick for an established refiner. On this metric, the stock trades at about 15.6x earnings, which is higher than both the Oil and Gas industry average of roughly 13.0x and the peer group average of about 11.1x.
A fair P/E multiple for Valero Energy, based on a model that weighs its sector, profitability profile, size and risk, is closer to 12.0x. The current valuation is several turns above that level, which indicates investors are paying a premium relative to what this framework suggests is reasonable for the business.
On the P/E yardstick alone, Valero Energy stock appears overvalued compared with both industry norms and the modelled fair multiple.
See what the numbers say about this price — find out in our valuation breakdown.
The Valero Energy Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the valuation puzzle for Valero Energy leaves off, by spelling out which paths for margins, earnings and growth would need to play out for the stock to be worth materially more or materially less than today’s share price. Rather than relying on a single multiple or model figure, each narrative lays out the assumptions behind its fair value view so you can track those against Valero Energy's reported results over time.
One of the top community narratives on Valero Energy: 46% overvalued
"A strong balance sheet and $5.3 billion of available liquidity provide Valero with operational and financial flexibility to invest in growth and optimization projects, potentially improving future earnings..."
Read one of the top narratives on Valero Energy
Do you think there's more to the story for Valero Energy? Head over to our Community to see what others are saying!
The Bottom Line
Valero Energy screens as overvalued on both the Discounted Cash Flow (DCF) intrinsic value estimate and the current P/E multiple. The recent move has stretched expectations, so the market is already assigning a rich price to future cash generation and refinery economics. The key question from here is whether refining margins and free cash flow can stay strong enough, for long enough, to justify that premium rather than see the valuation compress.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com