
Is Kesko Oyj (HLSE:KESKOB) Fully Valued Or Below Fair Value At €21.90?
Kesko Oyj (HLSE:KESKOB) drew investor attention after its recent close at €21.90. This matched the current consensus valuation and put the focus squarely on its fundamentals and regional retail footprint.
Over the past year, Kesko Oyj has paired a 14.54% year to date share price return with a 1 year total shareholder return of 21.23%. This suggests that recent buying interest is connected less to the flat 1 day move and more to a broader reassessment of its long term prospects, even though the 5 year total shareholder return is down 12.24%.
Compare Kesko Oyj's recent rerating with other retailers by scanning our hand picked list of solid balance sheet and fundamentals (194 results) for potential alternatives in the same broader space.
Kesko Oyj runs a broad retail network across groceries, building supplies and cars, which can support a solid business case. After the recent share price reset, is that quality being offered at a reasonable valuation today?
Most Popular Narrative: 0.5% Overvalued
The most followed narrative currently points to a fair value of €21.80 for Kesko Oyj, almost exactly in line with the latest close at €21.90. That alignment puts the emphasis on what is assumed for long term earnings and cash generation rather than any quick re rating.
In order for the above numbers to justify the price target of the analysts, the company would need to trade at a PE ratio of 18.6x on those 2029 earnings, down from 19.3x today. This future PE is lower than the current PE for the GB Consumer Retailing industry at 19.3x.
Want to understand why Kesko Oyj is modeled to grow earnings steadily while carrying a richer profit multiple than many peers? The heart of this narrative is a specific blend of revenue compounding, margin expansion and a valuation anchor that leans on those later year profit forecasts rather than today’s reported numbers.
Result: Fair Value of €21.80 (OVERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, parts of the Kesko Oyj story could unravel if heavy grocery investment fails to lift returns or if construction activity stays weak for longer than expected.
Find out about the key risks to this Kesko Oyj narrative.
Another View on Kesko Oyj’s Valuation
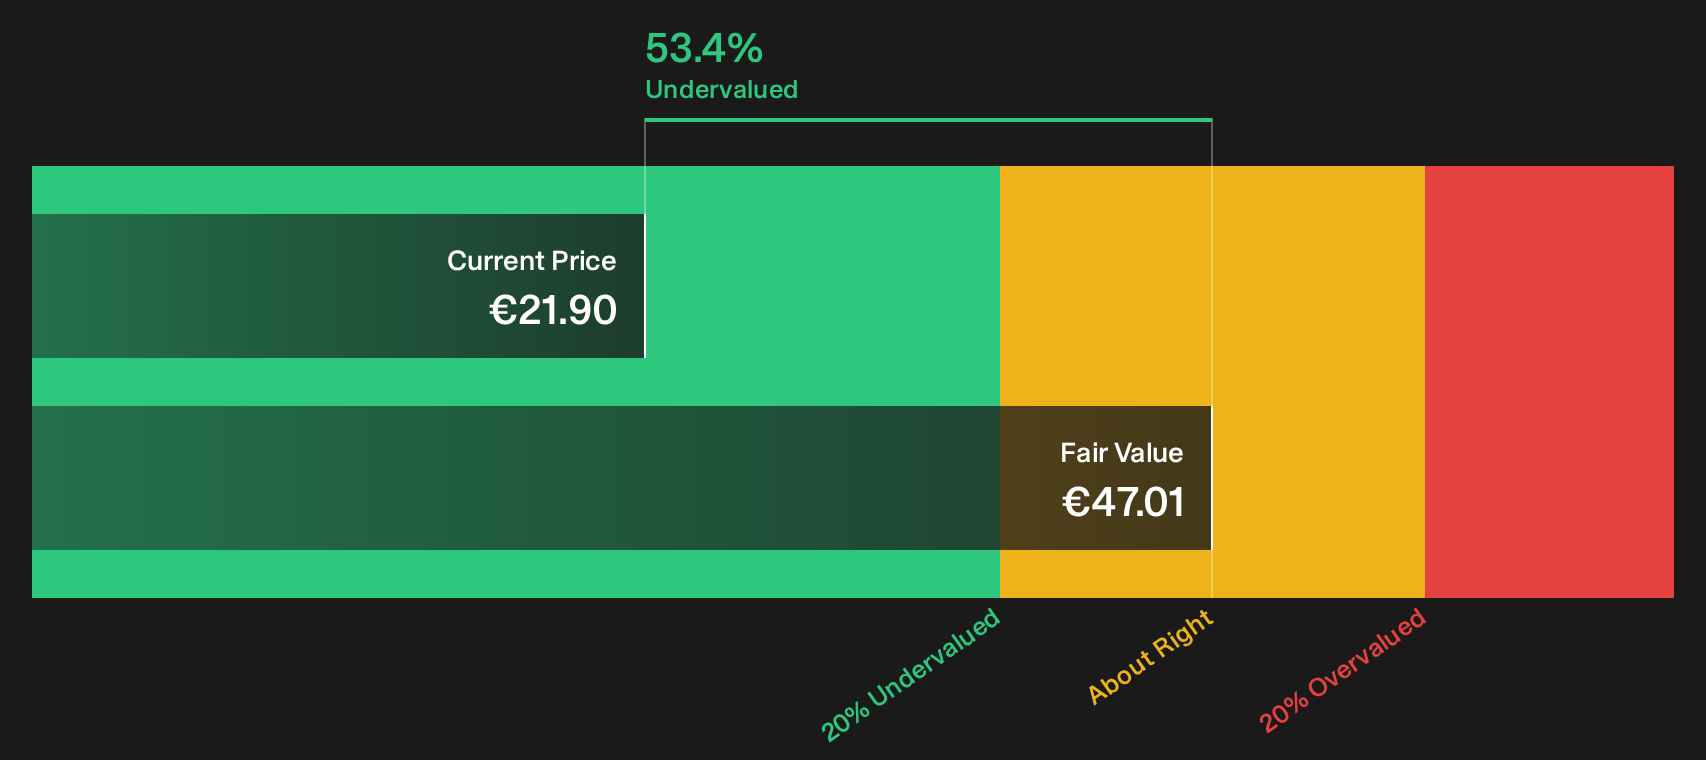
While the latest narrative pegs Kesko Oyj as only around 0.5% overvalued at €21.80, the SWS DCF model points in a very different direction. On that framework, the shares trade at €21.90, which is 53.4% below an estimated future cash flow value of €47.01. Which lens do you trust more when cash flows and earnings multiples disagree this sharply?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals on Kesko Oyj’s value can create plenty of noise, so move quickly, review the underlying data and decide where you stand with the company’s 3 key rewards and 2 important warning signs.
Looking for more Kesko Oyj style investment ideas?
If you stop with Kesko Oyj, you risk missing other opportunities that match your approach. Keep pushing your research wider with focused screeners.
- Target resilient balance sheets and steady fundamentals by scanning the list of solid balance sheet and fundamentals (194 results) that filters for financially robust businesses.
- Hunt for quality at a potential discount by reviewing the 183 high quality undervalued stocks that highlights companies with strong numbers and softer pricing.
- Prioritise income potential and stability by checking the 164 dividend fortresses that surfaces higher yield candidates with defensive characteristics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com