
JAPAN POST BANK (TSE:7182) On Rate Hike Hopes And Whether The Stock Still Looks Undervalued
JAPAN POST BANK (TSE:7182) has drawn investor attention after its recent share price move, with the stock up over the past month while still showing a decline over the past week.
That recent pullback sits against a much stronger backdrop, with JAPAN POST BANK showing a year-to-date share price return of 44.55% and a 1-year total shareholder return of 79.14%, which points to strong longer-term momentum despite softer short-term trading.
Scan opportunities with similar momentum and financial resilience by reviewing our hand picked 16 high quality undervalued stocks that share traits with JAPAN POST BANK's recent move.
After a strong year for JAPAN POST BANK and a recent pause in the share price, the gap between the current ¥3,290 level, analyst targets and intrinsic estimates raises a simple question: Is the stock still cheap or already generous?
Most Popular Narrative: 5.4% Undervalued
The most followed narrative on JAPAN POST BANK pegs fair value at ¥3,478, slightly above the recent ¥3,290 close. This frames the current pullback as a modest discount rather than a sharp mispricing.
The shift to positive yen interest rates and expectations for further Bank of Japan policy rate hikes are seen as creating a more supportive environment for reinvestment returns on domestic fixed income, which can help sustain the bank's profit expansion phase and influence net margins.
Want to see what sits behind that fair value call for JAPAN POST BANK? The narrative leans heavily on a step change in revenue growth, richer margins and a future earnings multiple that looks more like a growth story than a sleepy lender.
Result: Fair Value of ¥3,478 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, this story can unravel if Japanese government bond yields retreat again, or if rising competition lifts funding costs faster than JAPAN POST BANK can adjust.
Find out about the key risks to this JAPAN POST BANK narrative.
Another View: JAPAN POST BANK On Earnings Multiples
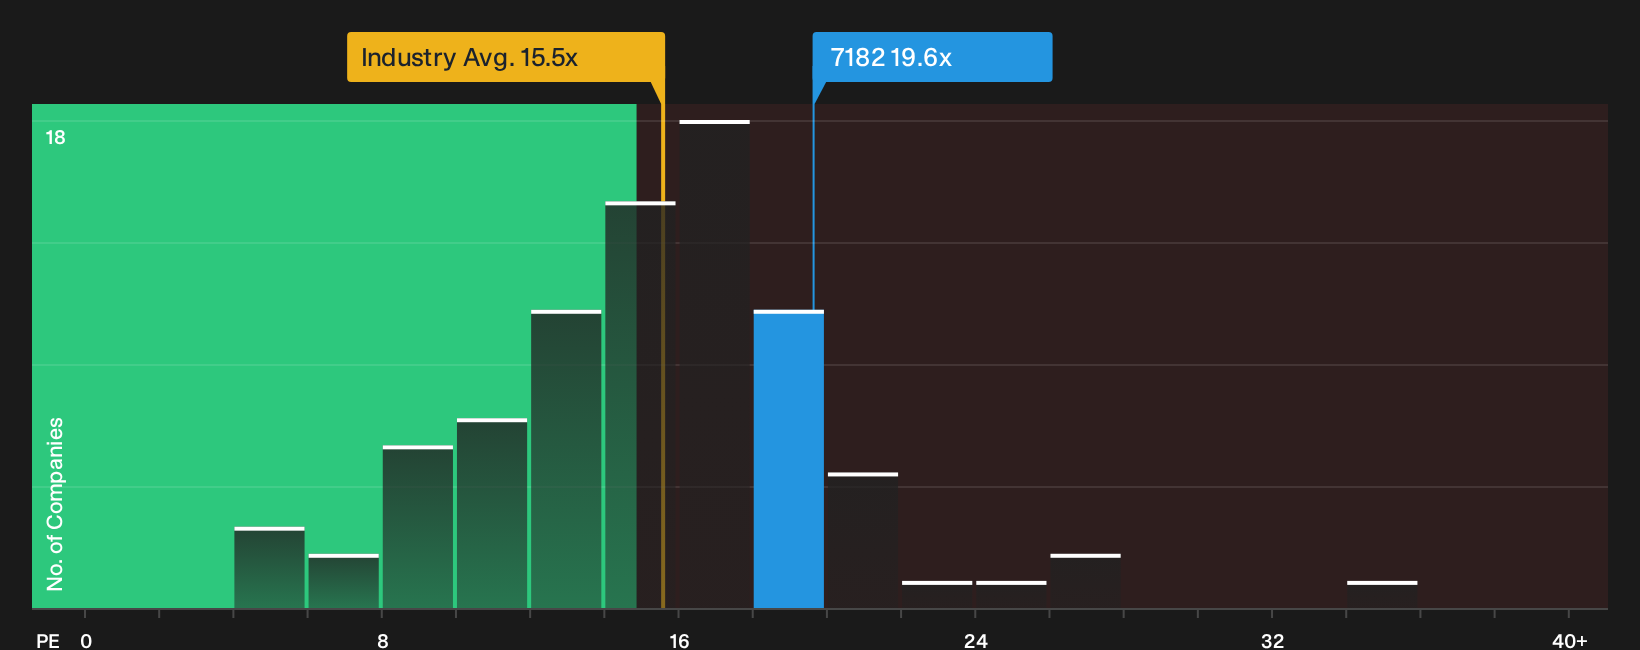
While the narrative and fair value work frame JAPAN POST BANK as 5.4% undervalued, the simple earnings lens looks less generous. The stock trades on a P/E of 19.6x, which is higher than both the JP Banks industry at 15.5x and its peer average of 17.4x.
That premium is not extreme because the fair ratio sits slightly higher at 20.8x. However, it does narrow the margin of safety. If sentiment cools and the market leans back toward industry levels instead of the fair ratio, how comfortable are you with paying up today for that growth story?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and caution around JAPAN POST BANK feels familiar, move quickly and examine the full picture yourself. Weigh both sides through the 3 key rewards and 1 important warning sign.
Looking for more JAPAN POST BANK style ideas?
If you want to keep sharpening your watchlist beyond JAPAN POST BANK, use these filters now so you do not miss the next opportunity.
- Target resilient payers and compare their yields and balance sheets using the 19 dividend fortresses.
- Hunt for mispriced quality and surface potential bargains through the 73 high quality undiscovered gems.
- Prioritise capital protection and stress test your portfolio against the 10 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com