
Intuit (INTU) Stock Looks Cheap On A 50% One Year Slump
Intuit stock has had a rough stretch, with a steep share price decline over the past year even as broad valuation checks now flag the company as looking cheap on several fronts. For investors, the gap between that weak share performance and a strong value score is what matters most.
- Over the past year, Intuit shares have fallen 49.7%, which puts the stock firmly in “out of favour” territory for many investors.
- Management’s push to build an end to end consumer money platform around TurboTax, Credit Karma and QuickBooks can support longer term earnings power, while the securities lawsuit and questions around Mailchimp and generative AI adoption add real uncertainty to how that plays out.
- On Simply Wall St’s broader checks, Intuit screens as relatively cheap, with a high value score of 5 out of 6, which points to a stock that looks discounted across several valuation lenses rather than obviously expensive.
The issue now is whether Intuit’s depressed share price already reflects these risks or if the current discount still overcompensates for them.
Spot opportunities that echo Intuit's mix of pressure and high value scores by scanning 31 high quality undervalued stocks, which highlights leading similar rerating potential across the market.Is Intuit a Bargain on Earnings?
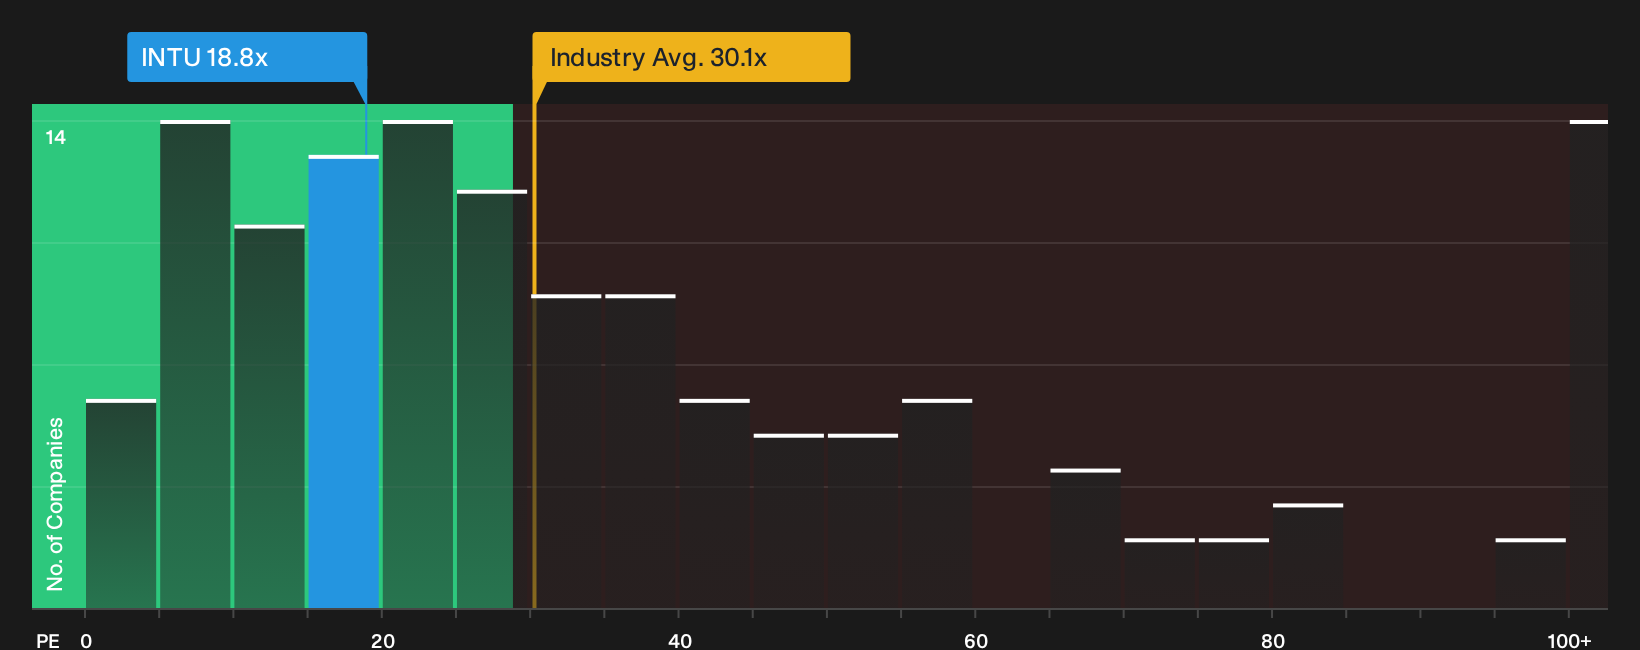
The P/E ratio fits Intuit because earnings still sit at the center of how most investors frame the TurboTax and QuickBooks franchise. On that lens, Intuit trades on a P/E of 18.8x, which is well below both the software sector average of 30.1x and a peer group closer to 44.5x. The modelled fair P/E for Intuit is 37.3x, which highlights a sizeable gap between what the market currently pays for each dollar of earnings and what the fundamentals and risk profile would usually point to.
That discount has opened up even after Intuit’s softer full year guidance and the securities lawsuit headlines that have weighed on sentiment since 2025. The lawsuit and Mailchimp and generative AI questions clearly matter for confidence, yet the present earnings multiple already sits far below both industry norms and the fair ratio estimate.
On the P/E multiple alone, Intuit stock appears undervalued relative to both sector peers and the fair earnings multiple implied by its profile.
See what the numbers say about this price — find out in our valuation breakdown.
The Intuit Narrative: What Would Justify Today's Price?
Intuit Narratives on Simply Wall St pick up where the P/E puzzle leaves off by spelling out which paths for growth, profitability and earnings would need to hold for the stock to be worth materially more or less than today’s price, and they sit on the Community page. Each one sets out a fair value as a thesis about Intuit's business that can be tracked over time, rather than a static snapshot.
Community views on Intuit could hardly be further apart, with one camp leaning into quality on sale and the other focusing on AI and growth risks that could cap upside.
Bull case: 43% undervalued
"The business quality here is not in question. The cash generation is phenomenal, the moat is real, the AI strategy is credible, and management has skin in the game…"
Read the full Bull Case to see why Intuit could be undervalued
Bear case: 11% overvalued
"AI related competition features heavily in the cautious view, with JPMorgan and others pointing to risks that lower cost AI based tax and accounting tools may pressure TurboTax DIY and QuickBooks…"
Read the full Bear Case to see why Intuit could be overvalued
Do you think there's more to the story for Intuit? Head over to our Community to see what others are saying!
The Bottom Line
Intuit now screens as undervalued on earnings multiples, with the market paying far less for each dollar of profit than sector peers or the modelled fair P/E suggest. That gap only closes if investors stay convinced that legal and AI related risks permanently cap the TurboTax, Credit Karma and QuickBooks franchise. The crux is whether today’s discount reflects a genuine value opportunity or whether the securities lawsuit and Mailchimp and generative AI questions prove sticky enough to keep the P/E anchored where it is.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com