
Comcast (CMCSA) Stock Still Looks Cheap On New Network Partnership News
Comcast stock has had a rough five year stretch, yet current valuation checks still flag the shares as looking cheap on several fronts rather than fully pricing in that weaker run.
- Over the past five years, Comcast shareholders have seen the price decline about 44.6%, which sets expectations low and can create a value driven setup.
- New partnerships with Fastly and Equinix can support long term cash flow expectations, while execution risk around network investments and streaming quality may still weigh on how much investors are willing to pay for those future earnings.
- On Simply Wall St’s broader checklist, Comcast earns a high value score of 5 out of 6, which means the stock currently leans cheap rather than expensive across multiple valuation gauges.
The issue now is whether Comcast’s depressed share price already reflects the recent setbacks or still leaves a margin between today’s market value and what the underlying business may justify.
Scan how Comcast compares with other beaten down value opportunities by running the same checks across our hand picked list of 31 high quality undervalued stocks.
Is Comcast Still Cheap on Earnings?
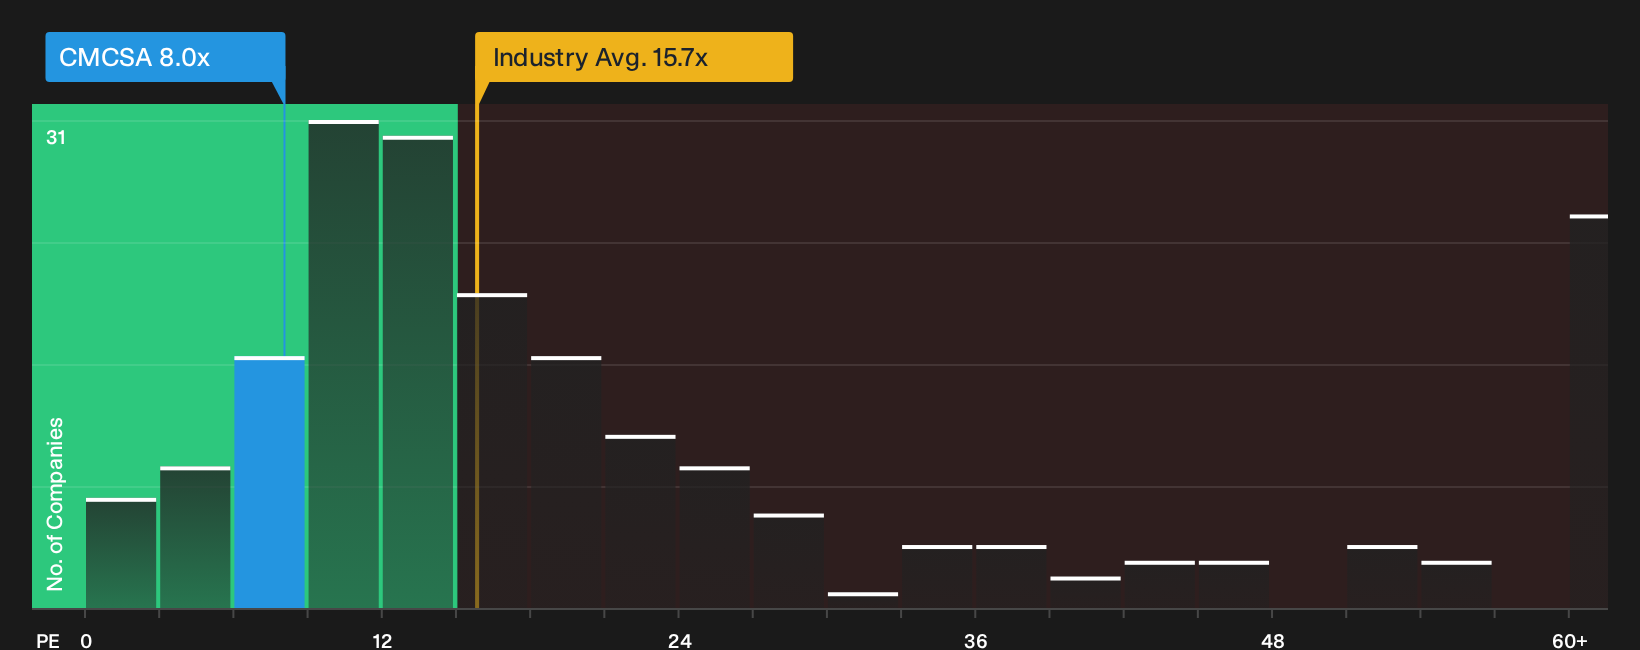
The P/E ratio fits Comcast because earnings are the main driver of how investors judge large telecom and media groups. On that yardstick, Comcast trades at about 8.0x earnings, compared with a telecom industry average near 16.1x and a peer set closer to 11.9x. That is a wide gap for a mature, cash generative operator with entrenched broadband and media assets.
A more tailored fair P/E for Comcast, based on its sector, profitability profile, size and risk, sits around 16.2x. The current 8.0x level is roughly half that benchmark. This indicates the market is pricing in a heavy dose of caution on future earnings quality despite recent partnerships with Fastly and Equinix that aim to improve network performance. The multiple suggests investors are still treating recent setbacks as the dominant story.
On this earnings multiple, Comcast stock appears undervalued relative to both its own fair P/E and typical telecom peers.
See what the numbers say about this price — find out in our valuation breakdown.
The Comcast Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Comcast pick up where the valuation gap leaves off by spelling out which growth, margin and earnings paths would need to hold for the stock to be worth materially more or materially less than today’s price. Each storyline links Comcast's potential catalysts and key risks to a single implied fair value, so you can watch over time which version of events actually unfolds.
Community narratives on Comcast sit wide apart, from a value story tied to broadband and media assets to a cautionary view focused on saturation and costs.
Bull case: 16% undervalued
"The opening of Epic Universe and the planned pipeline of new parks (e.g., London, Vegas, Texas) demonstrate management's ability to leverage Comcast's global IP portfolio and cater to demographic and urbanization trends..."
Read the full Bull Case to see why Comcast could be undervalued
Bear case: 20% overvalued
"Stagnant broadband growth remains a serious risk as the US market for broadband is reaching saturation, with slowing population growth and minimal expansion in addressable households..."
Read the full Bear Case to see why Comcast could be overvalued
Do you think there's more to the story for Comcast? Head over to our Community to see what others are saying!
The Bottom Line
Comcast screens as undervalued on earnings based multiples, which points to a gap between what the market is willing to pay today and what comparable telecom and media groups command. That discount only really pays off if cash flows from broadband, media and the park pipeline hold up well enough for sentiment to shift and the P/E to move closer to peers. The core debate now is whether current concerns around execution, saturation and streaming quality prove temporary or whether they are exactly why the discount is justified and stays in place.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com