
Danaher (DHR) Precision Medicine Story Keeps Fair Value In Focus
Recent commentary on Danaher (DHR) has focused on the stock’s limited upside compared with the S&P 500, tying that underperformance to concerns around organic revenue trends, margins, and earnings per share.
Over the past year Danaher has delivered a 6.1% total shareholder return, even though the share price is down 13.1% year to date and recently eased from its 90 day gain of 11.1%. This points to fading short term momentum despite a more resilient longer term picture when dividends are included.
Contrast Danaher’s recent softness with a curated group of resilient balance sheet stocks by scanning the list of solid balance sheet and fundamentals (23 results) that has already filtered for fundamental strength.
After a choppy stretch where Danaher has lagged broader indices yet still produced a modest 1-year gain with dividends, the question now is simple: Does the current valuation still compensate you for the operational questions on growth, margins, and earnings?
Most Popular Narrative: 12.5% Undervalued
On the most followed narrative, Danaher’s fair value of $228.61 sits above the last close of $200.14. This puts a clear spotlight on the underlying growth engine that is being modelled into that gap.
The sustained advancement of precision medicine and personalized therapies, including new AI-assisted diagnostic solutions and groundbreaking launches in genomics (like support for in vivo CRISPR therapies), positions Danaher's technology portfolio to capture higher-margin growth and drive long-term EBITDA expansion.
Read the complete narrative. Read the complete narrative.
Want to see what is built into that premium for Danaher? The story leans heavily on recurring consumables, a meaningful margin lift, and a richer profit mix. Curious which future earnings path has to play out for that valuation gap to close.
Result: Fair Value of $228.61 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, the Danaher narrative depends on bioprocessing order patterns improving and on China policy risks easing. Both of these factors could just as easily move the story in the other direction.
Find out about the key risks to this Danaher narrative.
Another View on Danaher’s Valuation
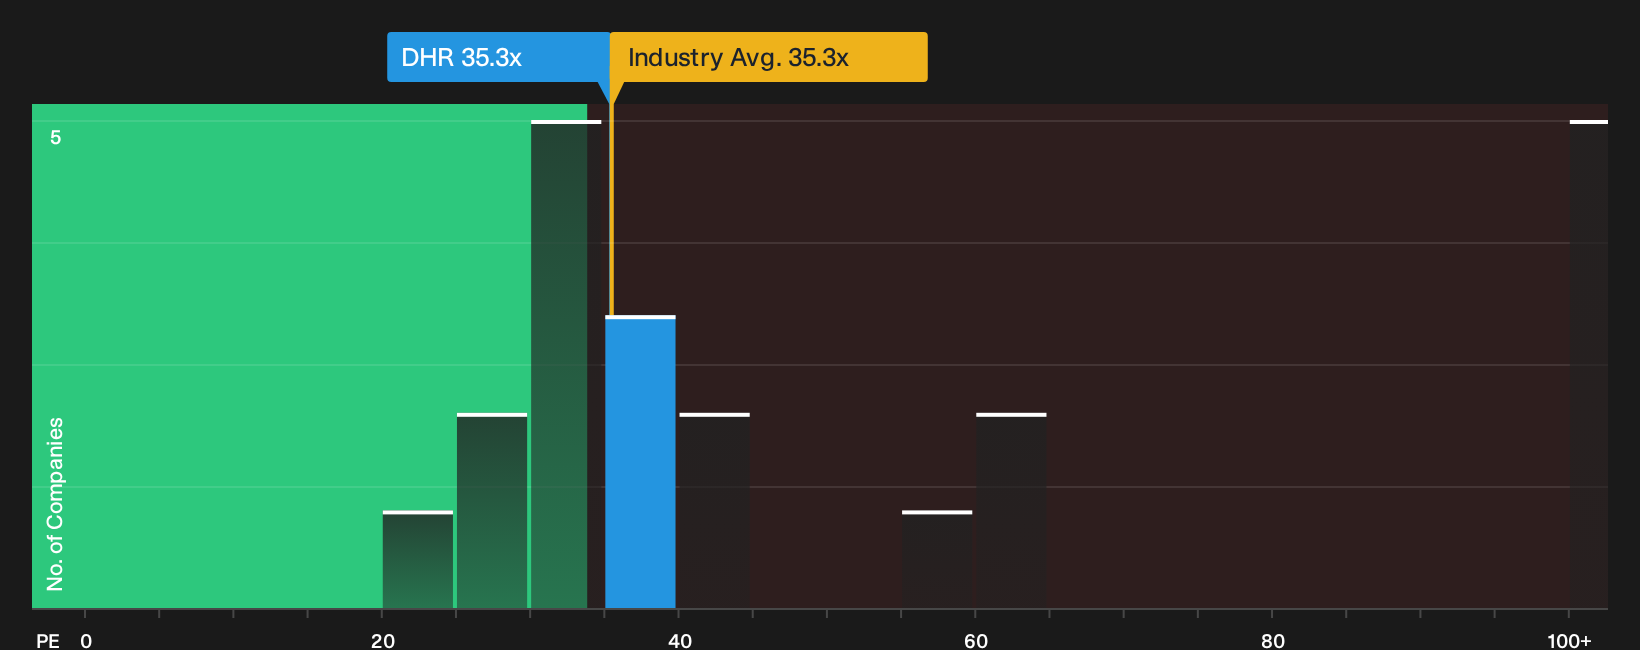
On a multiples lens, Danaher looks less clear cut. The current P/E of 35.3x sits above both the estimated fair ratio of 31.7x and the peer average of 32.6x. That points to investors already paying up for quality. The open question is whether that premium still leaves enough room for error.
For a closer look at how that P/E gap could narrow or stretch over time, and what that might mean for your risk or opportunity, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Danaher can be confusing, so use that uncertainty as a prompt to move quickly. Review the numbers and weigh both sides of the story with the 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond Danaher?
If Danaher has sharpened your focus on quality and valuation, do not stop here. Use the screener to spot other opportunities that could fit your playbook.
- Target resilient balance sheets by scanning the list of solid balance sheet and fundamentals (23 results) that highlights companies with stronger financial footing and cleaner fundamentals.
- Pursue potential mispricings by reviewing the 31 high quality undervalued stocks that filters for businesses where fundamentals and current pricing appear out of sync.
- Stack income potential on top of capital returns by checking the 6 dividend fortresses that focuses on higher yielding companies with robust payouts.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com