
Should Alternative Capital Growth Require Action From RenaissanceRe Stock Investors?
- RenaissanceRe Holdings has been highlighted as a leading participant in the fast growing alternative capital segment of reinsurance, using catastrophe bonds and collateralized reinsurance to expand capacity and diversify how it sources risk capital.
- The Capital Partners platform is becoming a key earnings lever for RenaissanceRe Holdings, as managing third party funds supports fee income and improves capital efficiency without relying solely on its own balance sheet.
- We will now examine how RenaissanceRe Holdings' expanding third party capital platform influences the investment narrative around its earnings mix.
RenaissanceRe Holdings Investment Narrative Recap
For RenaissanceRe Holdings, the core belief as a shareholder is that the reinsurance franchise can keep turning strong risk selection and fee based Capital Partners income into attractive returns, even as headline revenue and earnings are forecast to decline over the next few years. The near term swing factor remains underwriting and catastrophe experience, given the sizeable property cat exposure and the growing use of alternative capital.
The biggest risk right now is that softer pricing in property and casualty lines, together with any severe natural catastrophe season, erodes those currently high 22.9% net margins and a 20.7% return on equity. The recent focus on third party capital does not materially change that near term risk profile, but it does shift more of the earnings mix toward fee income rather than pure underwriting.
The most relevant element from recent commentary is the emphasis that RenaissanceRe Holdings, along with a few peers, is well positioned around alternative capital and third party funds. That ties directly into the Capital Partners platform, which has already seen fee income from capital partners double since 2023 and now contributes regularly to results with limited balance sheet usage.
For you as an investor, that matters because analysts expect revenue to decline about 9.9% per year and earnings to contract roughly 16.3% annually over the next three years. Execution on the capital light fee engine may help offset some of that pressure, while the main operational watchpoints remain catastrophe volatility, competition in E&S and casualty, tax changes in Bermuda, and how consistently management maintains underwriting discipline as markets soften.
What The Current Forecasts Assume For RenaissanceRe Holdings
RenaissanceRe Holdings' narrative projects US$7.4b revenue and US$1.3b earnings by 2029, based on analyst estimates that revenue will decline 13.0% per year and earnings will fall by US$1.3b from US$2.6b today.
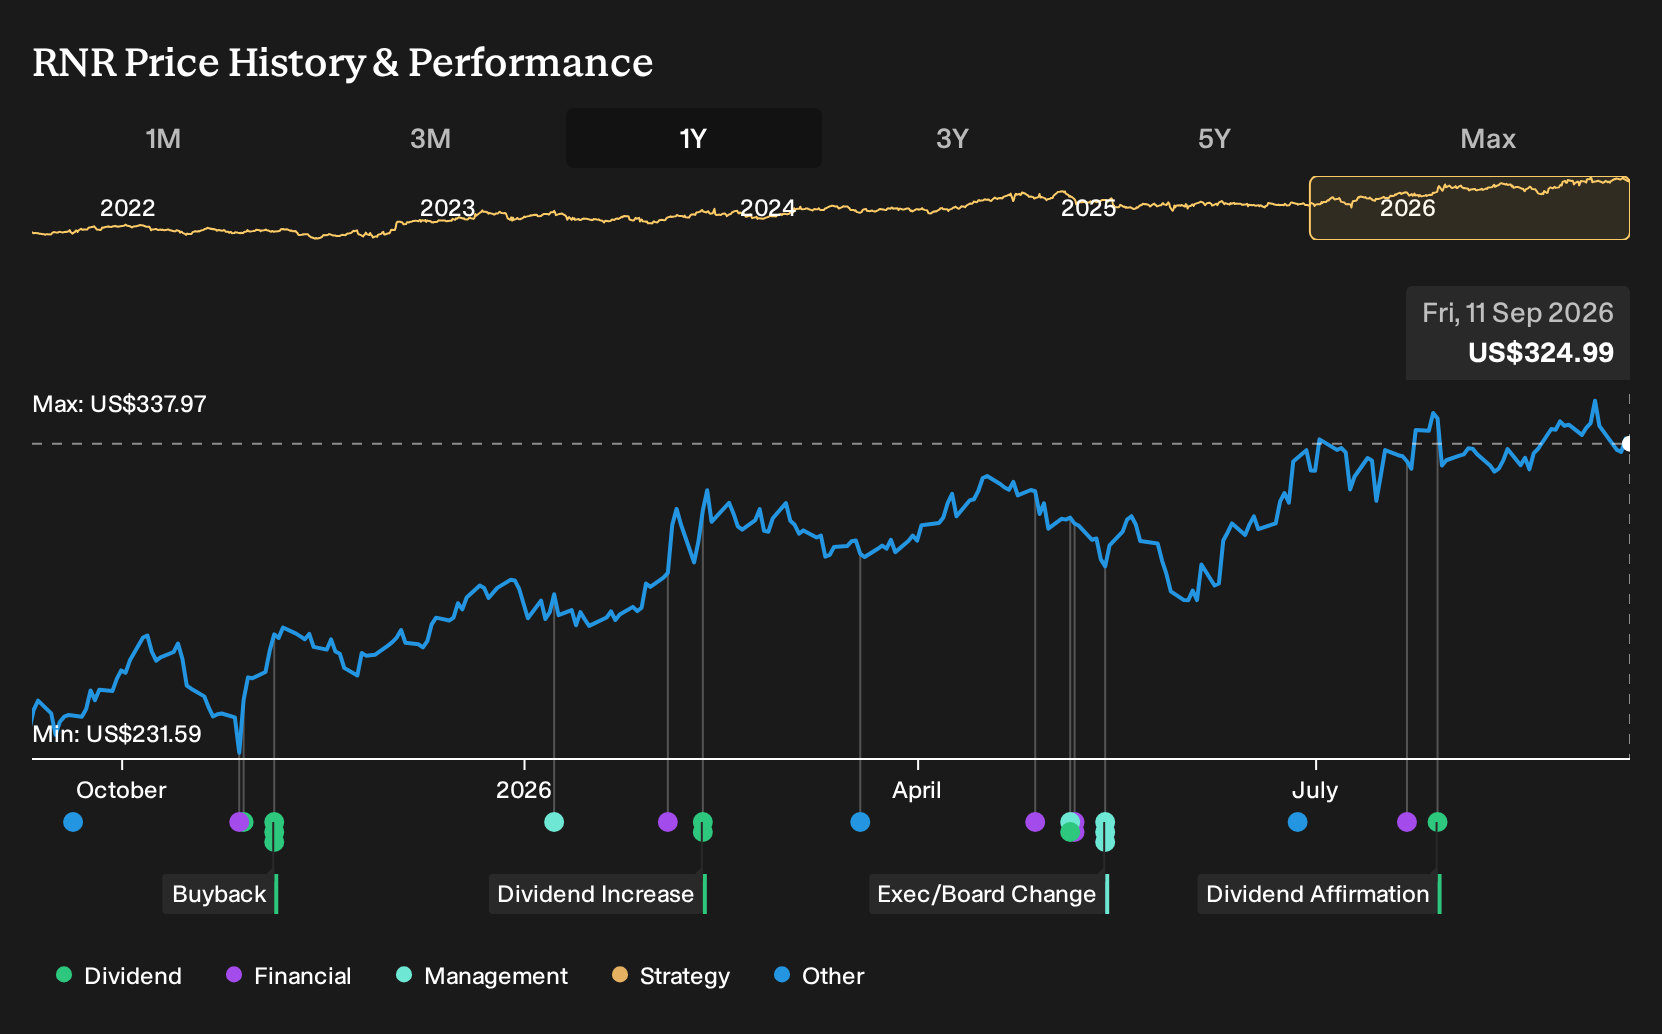
Uncover why RenaissanceRe Holdings' fair value indicates a 7% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view on RenaissanceRe leans heavily into catastrophe risk. The most pessimistic analysts already had a cooler take before this news, forecasting revenue declines of about 10.3% a year and earnings falling from US$2.7b to US$1.4b by 2029. Use that contrast to assess how this update might influence your own view.
Explore 2 other RenaissanceRe Holdings fair value estimates, including one that suggests as much as 8% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your RenaissanceRe Holdings research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for RenaissanceRe Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate RenaissanceRe Holdings' overall financial health at a glance.
Looking For More Ideas Beyond RenaissanceRe Holdings?
If the RenaissanceRe Holdings story has sharpened your thinking on risk, return, and balance sheet strength, it can be useful to line it up against other opportunities using the Simply Wall St Screener. That way you can test your thesis across a wider set of businesses rather than anchoring on a single stock.
- For investors who want potential upside without abandoning quality, scan a curated group of attractively priced companies through the 31 high quality undervalued stocks.
- If your priority is resilience and capital strength, compare RenaissanceRe Holdings with other financially robust businesses by reviewing the list of solid balance sheet and fundamentals (23 results).
- When the goal is to uncover lesser known opportunities, broaden your watchlist with a focused collection of under-the-radar candidates using the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com