
DuPont De Nemours (DD) Could Be 26% Undervalued Following Its PFAS Settlement
DuPont de Nemours (DD) just agreed to a long running environmental settlement tied to PFAS emissions in North Carolina, a legal step that may reshape how investors think about the stock’s ongoing liability profile.
Recent trading has been choppy for DuPont de Nemours, with the share price down 12.0% over 30 days and 12.3% over 90 days, even though the year to date share price return is 3.6% and the 1 year total shareholder return is 33.3%. This suggests that the fresh PFAS settlement is feeding into a reassessment of long term risk rather than erasing the gains long term holders have seen.
Spot under-pressure stories like DuPont de Nemours and compare them with financially resilient peers using our curated 11 resilient stocks with low risk scores.After a sharp pullback despite a 1 year total return above 30%, DuPont de Nemours now sits in an awkward middle ground. Is most of the easy upside already gone, or does the current valuation still leave meaningful room ahead?
Most Popular Narrative: 26.2% Undervalued
On the most followed narrative, DuPont de Nemours screens as materially undervalued, with fair value well above the last close of $126.99. This puts a spotlight on the assumptions driving that gap.
DuPont's accelerated growth in Electronics, particularly from AI-driven applications, advanced packaging, and high-performance computing, positions the company to capture outsized revenue expansion as node migrations and broader electronics market recovery unfold through 2025 and beyond. Persistent strength and strategic investment in Healthcare & Water, driven by surging global demand for clean water solutions and healthcare products, leverages favorable demographic, sustainability, and infrastructure trends to drive above-peer organic revenue growth and margin stability.
Read the complete narrative. Read the complete narrative.
Want to understand why this narrative assigns such a high fair value to DuPont de Nemours? The core story links steady top line progress, a large margin reset, and a richer future earnings multiple than many mature industrial peers. Curious which revenue mix shifts and profitability targets have to land for that to hold up? The full narrative lays out those numbers in detail.
Result: Fair Value of $172.07 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, the DuPont de Nemours story can crack if PFAS liabilities escalate again or if any portfolio shrinkage leaves earnings more concentrated and volatile.
Find out about the key risks to this DuPont de Nemours narrative.
Another View: What Multiples Say About DuPont de Nemours
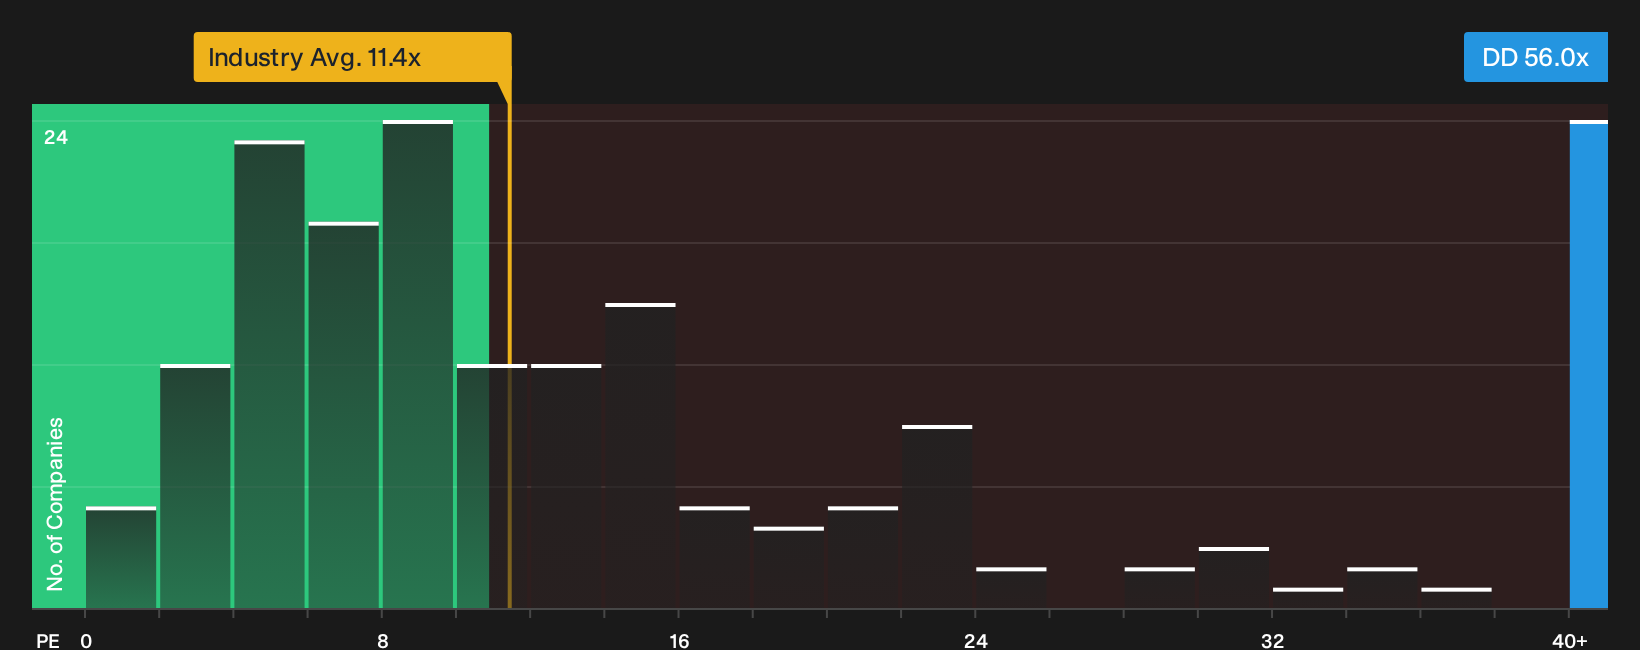
On a simple earnings lens, DuPont de Nemours looks far less relaxed than the 26.2% undervalued narrative suggests. The stock trades on a P/E of 56x, compared with 29.4x for peers and 11.4x for the wider Industrials group, while the fair ratio sits at 36.9x. That gap implies investors today are paying a steep premium for future execution that has not yet flowed through reported earnings. Is that a cushion or a tightrope for anyone building a new position?
For a clearer breakdown of how this earnings multiple stacks up against the assumptions in play, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around DuPont de Nemours can feel messy, so move quickly, review the data on both sides, and pressure test your own view with the 4 key rewards and 2 important warning signs.
Looking for more DuPont de Nemours style investment ideas?
Do not stop your research with DuPont de Nemours. Use this pullback as a prompt to widen your watchlist and line up your next move.
- Spot potential bargains early by scanning our 16 high quality undiscovered gems and see which under-the-radar businesses already have the fundamentals to support long term compounding.
- Build a sturdier core for your portfolio by using the list of solid balance sheet and fundamentals (23 results) to focus on companies with healthier finances backing their share prices.
- Target value oriented ideas with defined upside by filtering opportunities through the 31 high quality undervalued stocks before sentiment fully catches up.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com