
CONMED Stock Faces Questions After Suture Anchor Labeling Recall
- CONMED Corporation previously initiated a voluntary Class II recall of its Genesys CrossFT Suture Anchor, involving two units distributed in Texas with incorrect patient implant cards that affect device identification and traceability.
- The recall highlights how even limited quantity labeling issues can introduce operational friction for CONMED in orthopedics, including correction costs and added scrutiny on quality systems and post market surveillance.
- We will now examine how this limited Genesys CrossFT labeling recall might influence CONMED's broader investment narrative around surgical devices.
Stress test how this CONMED recall shapes your risk tolerance by scanning a curated set of 11 resilient stocks with low risk scores designed to keep operational surprises to a minimum.
CONMED Investment Narrative Recap
To own CONMED, you need to believe in a steady build in minimally invasive procedure volumes and recurring revenue from products like AirSeal, Buffalo Filter and BioBrace, supported by ongoing operational clean up after a choppy earnings period. The current recall involves only two Genesys CrossFT Suture Anchor units, so it does not materially change that overarching thesis.
In the near term, the key swing factor is still execution on supply chain and cost discipline so that earnings catch up with the revenue base and one off items fade. The biggest risk remains pressure on hospital capital budgets and elective procedures, alongside elevated debt that is not yet well covered by operating cash flow.
The recent voluntary Class II recall of the Genesys CrossFT Suture Anchor with Disposable Driver ties directly into orthopedics, where CONMED has already dealt with supply chain friction and share loss. This particular event is small in scale, but it feeds into how closely you think the quality system and post market surveillance support a smoother recovery in that segment.
For catalysts, the focus still sits on resolving operational bottlenecks, improving margins from the current 4.1% level and converting forecast earnings growth into cleaner, less one off heavy results. Execution on high value platforms like AirSeal and Buffalo Filter, while keeping labeling and traceability issues contained, will shape how much confidence investors place in CONMED’s medium term outlook.
CONMED's current analyst narrative points to revenues of US$1.6b and earnings of US$179.7m by 2029, built on forecast top line expansion of 4.2% per year and an earnings step up of roughly US$123.2m from the US$56.5m recorded today.
Uncover why CONMED's fair value is essentially consistent with its current price.
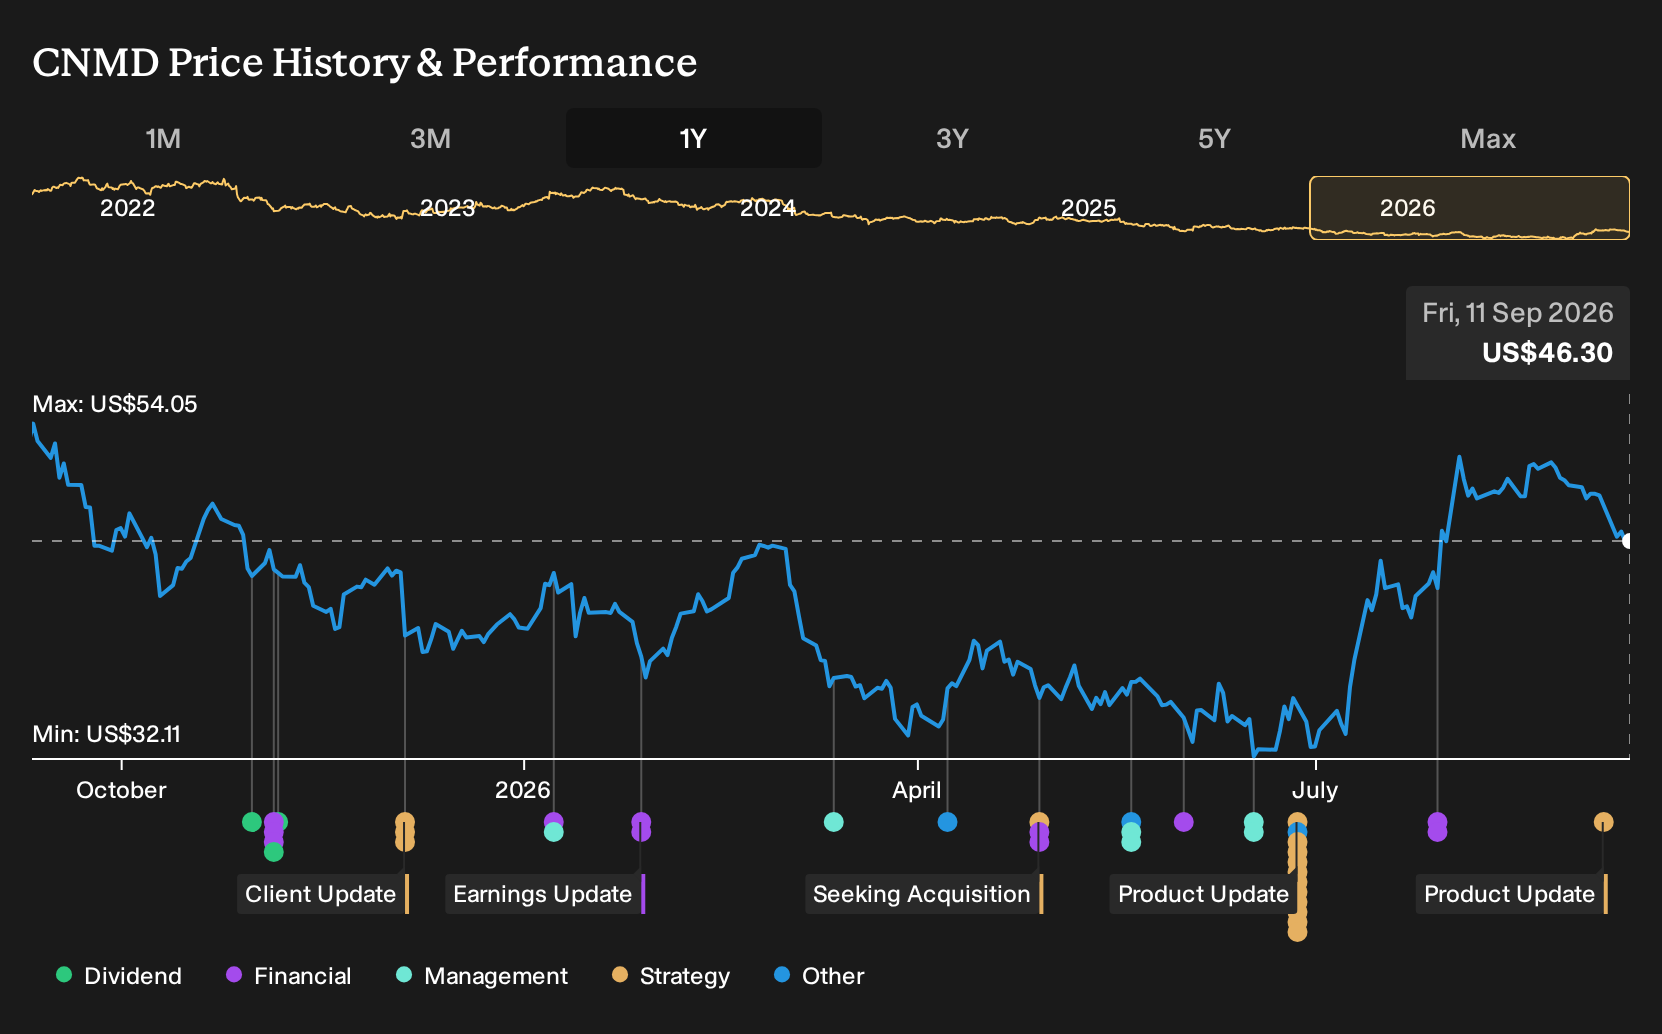
Exploring Other Perspectives
Some of the lowest CONMED forecasts lean hard into reimbursement and cost control risk. These analysts were already penciling in slower revenue of about US$1.5b and earnings near US$168.2m by 2029. A labeling recall like this could reinforce that cautious story, or it might prompt you to recheck both bullish and bearish assumptions.
Explore 3 other CONMED fair value estimates, including one that suggests as much as 7% downside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your CONMED research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for CONMED. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CONMED's overall financial health at a glance.
Looking for more CONMED investment ideas?
If this CONMED recall has you reassessing risk and reward, it might be a good moment to widen the lens and compare it with other businesses that fit different portfolio roles using the Simply Wall St Screener.
- For investors who want potential mispricing backed by solid fundamentals, scan our curated set of 31 high quality undervalued stocks that combine quality metrics with attractive valuation signals.
- If capital preservation and balance sheet strength matter most to you, focus on companies in the list of solid balance sheet and fundamentals (23 results) to see which ones carry less financial strain.
- When resilience is the priority, review a 11 resilient stocks with low risk scores that screens for businesses with lower overall risk scores so operational surprises are less likely to catch you off guard.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com