
Braze (BRZE) Stock Looks Cheap On Its 48% Three Year Slide
Braze stock has fallen hard over the past three years, yet on most valuation checks it now screens as cheap rather than expensive. This creates a clear gap between recent share price pressure and what the numbers suggest about pricing.
- Over the past three years, Braze has declined about 48%, which leaves the current market value well below where longer term holders bought in.
- Growth expectations around its AI driven marketing tools and the expanded relationship with a large cloud provider can support sentiment, while any slowdown in new customers or weaker profitability could limit how much investors are willing to pay for that story.
- On broader valuation checks, Braze looks inexpensive, with the stock screening as undervalued in 6 out of 6 metrics rather than as a fully priced software play.
The issue now is whether the recent share price slide has already more than accounted for Braze's risks, or if the current discount is signaling that the business needs to deliver much stronger fundamentals to justify a higher valuation.
Spot under-pressure stories like Braze that still screen as potential value and compare them with 31 high quality undervalued stocksIs Braze a Bargain on Sales?
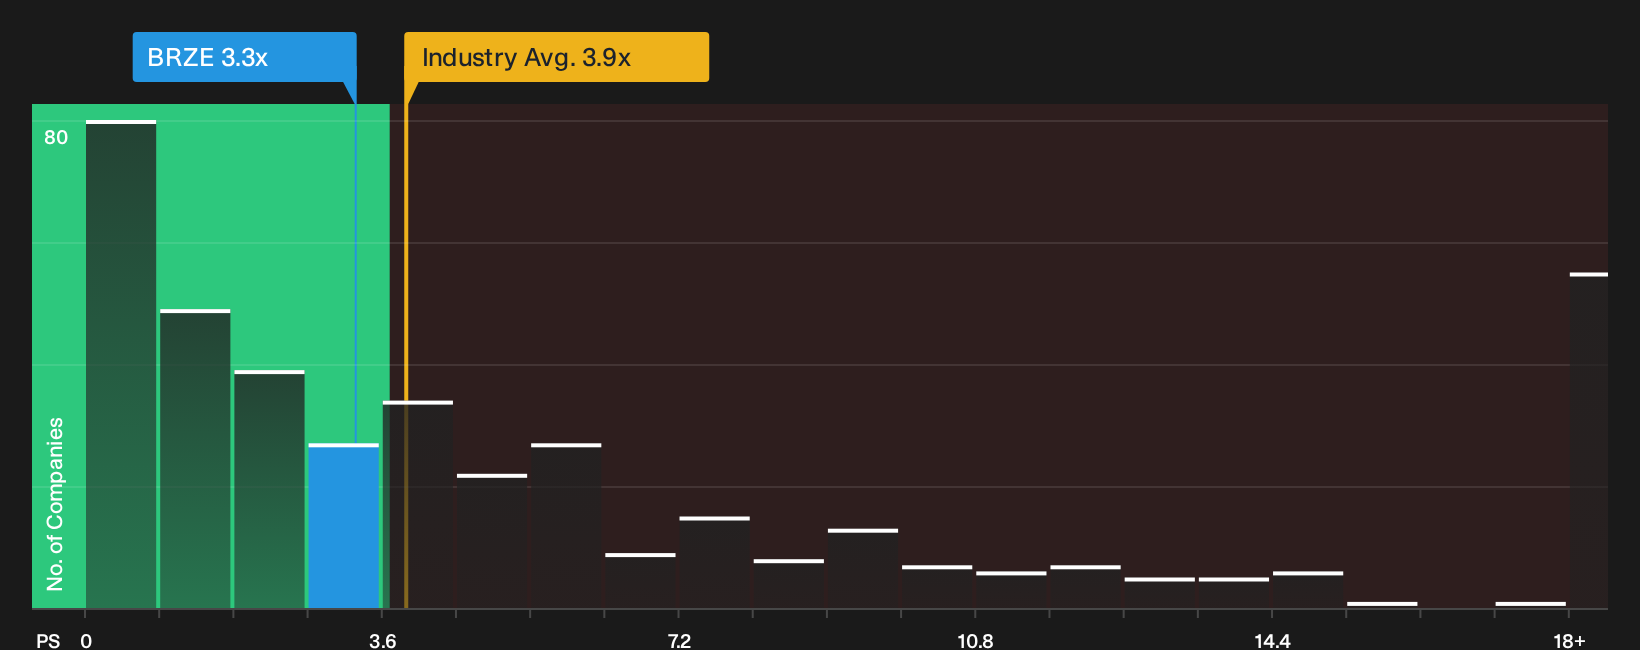
P/S is a useful lens for Braze because the business is still defined more by its revenue base than by mature earnings. On this measure, Braze trades at about 3.3x sales, below both the broader software industry at roughly 3.9x and the peer group near 4.1x. The fair P/S ratio implied by the model is 4.1x, which is higher than where the shares change hands today.
That gap suggests the market is pricing Braze at a discount to what would typically be expected given its sector, size and risk profile. Despite the recent share price hit after Q2 results and guidance, the stock still screens below the multiple that the tailored fair ratio points to.
On the P/S yardstick, Braze stock appears undervalued compared with both its fair ratio and software peers.
See what the numbers say about this price — find out in our valuation breakdown.
The Braze Narrative: What Would Justify Today's Price?
Narratives for Braze sit on Simply Wall St's Community page and spell out which future paths for growth, margins and earnings would need to play out for the stock to be worth materially more or less than today's price. Each one is framed as a thesis about Braze's business that can be checked over time, rather than a one off estimate, so you can see how that story holds up as new information arrives.
One of the top community narratives on Braze: 34% undervalued
"Braze's acquisition of OfferFit is expected to enhance AI-driven optimization capabilities and lead to revenue growth through deal size expansion and differentiation in the market..."
Read one of the top narratives on Braze
Do you think there's more to the story for Braze? Head over to our Community to see what others are saying!
The Bottom Line
Braze now screens as undervalued on standard market multiples, which suggests investors are pricing in a fair amount of execution and profitability risk. The key question is whether the marketing platform can keep converting product interest into durable revenue without eroding margins. If growth in newer tools and partnerships holds up while efficiency improves, the current discount can look like patience being rewarded. If customer additions or profitability falter, that lower multiple can simply reflect a business that has more to prove before the market is willing to pay up again.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com