
Illumina (ILMN) Stock May Be 20% Undervalued On Cash Flow
Illumina has rallied sharply over the past year, yet the valuation signals pull in different directions. The intrinsic value estimate based on a Discounted Cash Flow model points to the shares trading at a discount, while market multiples and a low overall value score lean closer to an expensive reading.
- Illumina is up about 117% over the past year, which puts fresh pressure on the current share price to justify that kind of recovery.
- Expectations for future cash generation from Illumina's sequencing business can support the Discounted Cash Flow upside case. However, any disappointment in growth or profitability may quickly challenge that view.
- The broader valuation checks are cautious, as Illumina screens as attractive on only a small share of metrics. The stock does not come across as a clear bargain even though the value score of 2 hints at some isolated areas of appeal.
The issue now is whether Illumina's current price already bakes in most of the good news that a 20.3% Discounted Cash Flow discount suggests is still on the table.
Capitalize on the valuation debate around Illumina by scanning a curated list of 31 high quality undervalued stocks that also combine cash flow support with disciplined balance sheets.Is Illumina Still Cheap on Cash Flow?
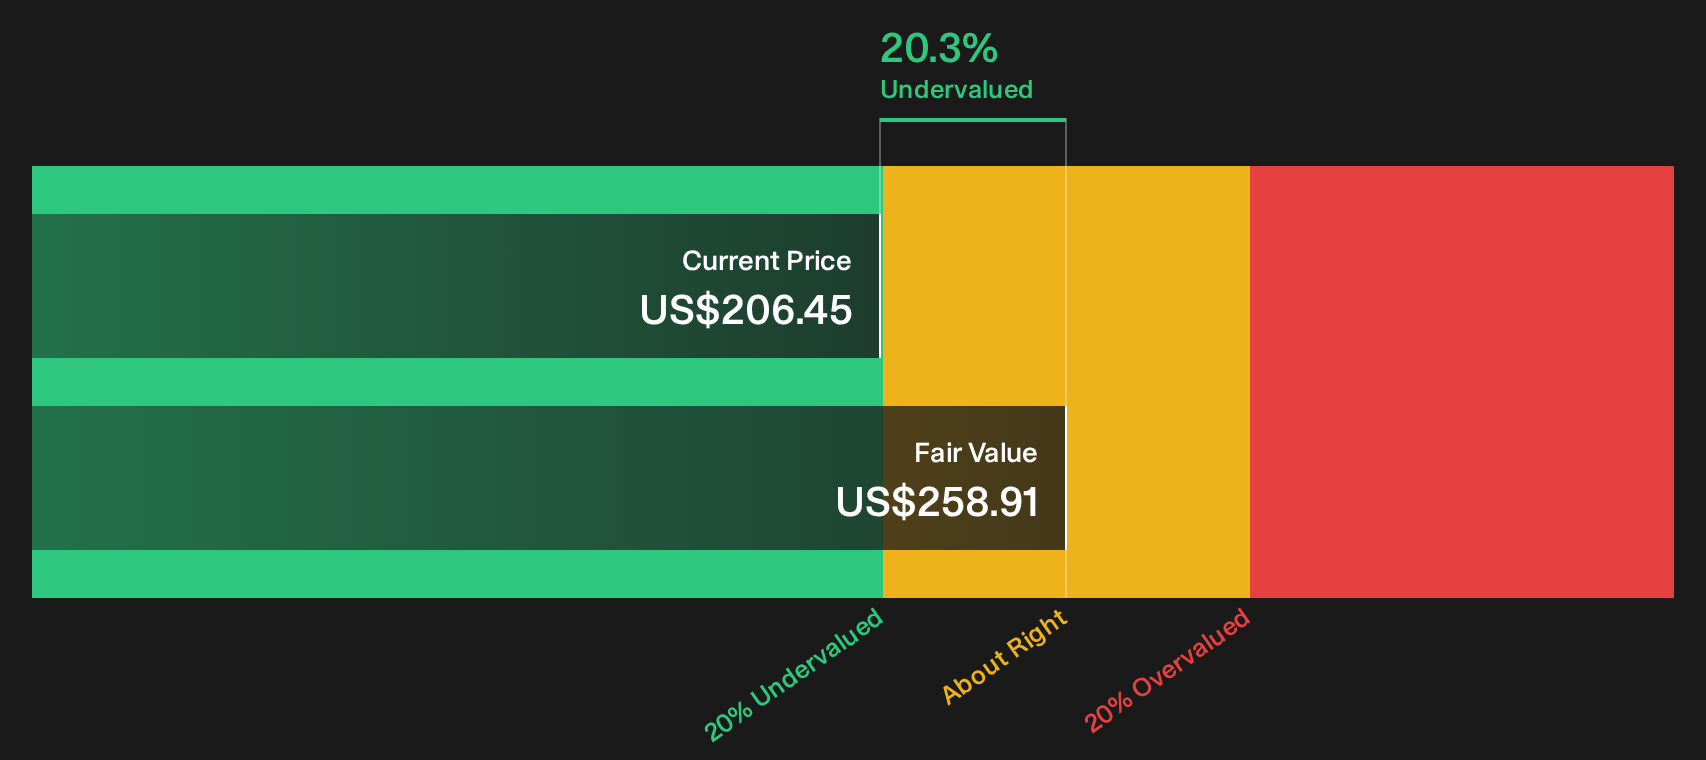
The Discounted Cash Flow (DCF) approach looks at the cash Illumina is expected to generate for shareholders and discounts it back to today. On that scorecard, the latest twelve month free cash flow sits at about $942.9 million, and the model assumes that this stream continues growing rather than shrinking.
Those projections, run through a 2 Stage Free Cash Flow to Equity framework, point to an estimated intrinsic value of about $259 per share. Set against the current market price, that implies the stock trades at roughly a 20.3% discount. In plain terms, if the cash flow path used in the DCF proves realistic, Illumina’s current quotation appears conservative rather than stretched.
Taken together, the DCF output indicates that Illumina appears undervalued relative to its modeled cash generation.
Our Discounted Cash Flow (DCF) analysis suggests Illumina is undervalued by 20.3%. Track this in your watchlist or portfolio, or discover 31 more high quality undervalued stocks.
Has Illumina Run Too Far on Earnings?
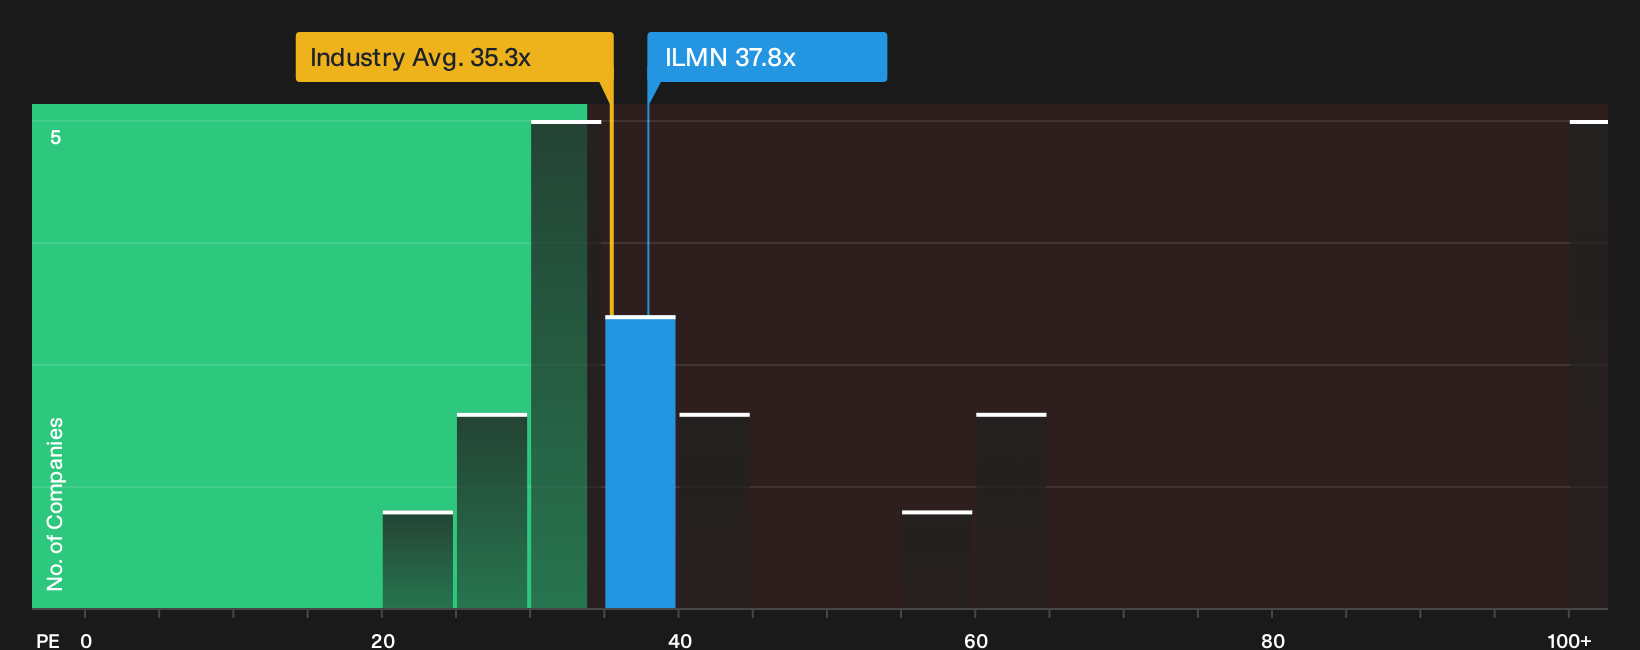
P/E works well for Illumina because investors still anchor much of their view on the earnings power behind its sequencing platform. On that score, the stock trades on a P/E of about 37.8x, which is above both the Life Sciences industry average of roughly 35.3x and the peer group near 33.0x.
The valuation model that blends Illumina’s growth profile, profitability, size and risk points to a fair P/E closer to 26.4x. That is a sizeable gap to the current multiple and indicates investors are paying a premium that the tailored benchmark does not support, even though the sector itself tends to trade on higher P/E ratios.
On earnings, Illumina currently screens as overvalued relative to the P/E level the model flags as reasonable.
See what the numbers say about this price — find out in our valuation breakdown.
The Illumina Narrative: What Would Justify Today's Price?
Illumina’s valuation puzzle only really comes into focus once you see the Narratives that sit on Simply Wall St’s Community page, since these spell out which paths for revenue, margins and earnings would need to play out for the shares to look meaningfully cheaper or richer than today’s quote. Each Narrative treats fair value as a thesis about Illumina's business that you can monitor over time, rather than a static number on a chart.
Community views on Illumina split into two very different stories about what drives value from here.
Bull case: 10% undervalued
"With the acquisition of SomaLogic and recent product launches in multiomics, Illumina is uniquely positioned to capitalize on the explosive growth in population genomics and multiomic-driven precision medicine..."
Read the full Bull Case to see why Illumina could be undervalued
Bear case: roughly fairly valued
"Intensifying competition, particularly from upcoming platforms like Roche's with faster turnaround times, poses the risk of price pressure, potential market share loss, and margin compression..."
Read the full Bear Case to see why Illumina could be overvalued
Do you think there's more to the story for Illumina? Head over to our Community to see what others are saying!
The Bottom Line
Illumina’s Discounted Cash Flow (DCF) output points to intrinsic value above the current quotation, yet the P/E screen leans toward the shares looking overvalued. That clash reflects a simple split. The intrinsic value view leans on the cash that Illumina can generate over time, while the market multiple view leans on how much investors are willing to pay today for its earnings profile. Broader valuation checks remain weak, so any apparent discount rests heavily on the DCF assumptions. The key question from here is whether Illumina can deliver the growth and margins implied in that cash flow path without the market cutting the earnings multiple.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com