
Clearway Energy (CWEN) Stock Trades At A Premium To Earnings Despite A 46% Return
Clearway Energy stock has delivered a strong 46.1% gain over the past three years, yet current valuation checks paint a picture of a utility business that does not screen as an obvious bargain. Recent share price weakness and a low overall value score both lean in the same direction, implying investors are paying a relatively full price for the current fundamentals.
- A 46.1% return over three years highlights that Clearway Energy has already rewarded patient shareholders, which can limit how much upside investors may reasonably expect from here.
- The company’s focus on contracted renewable assets can support relatively stable cash flows. However, future project spending and funding needs may weigh on how much value ultimately flows through to equity holders.
- The broader valuation checks say Clearway Energy leans expensive rather than cheap, with only 1 of 6 metrics screening as attractive on value 1.
The issue now is whether Clearway Energy’s current price already reflects the cash generation the business can realistically deliver, or if there is still room for investors to pay today and be compensated over time.
Compare Clearway Energy’s recent returns with hand-picked peers by scanning 39 power grid technology and infrastructure stocks that are shaping the future of energy infrastructure and grid reliability.
Does Clearway Energy Look Pricey on Earnings?
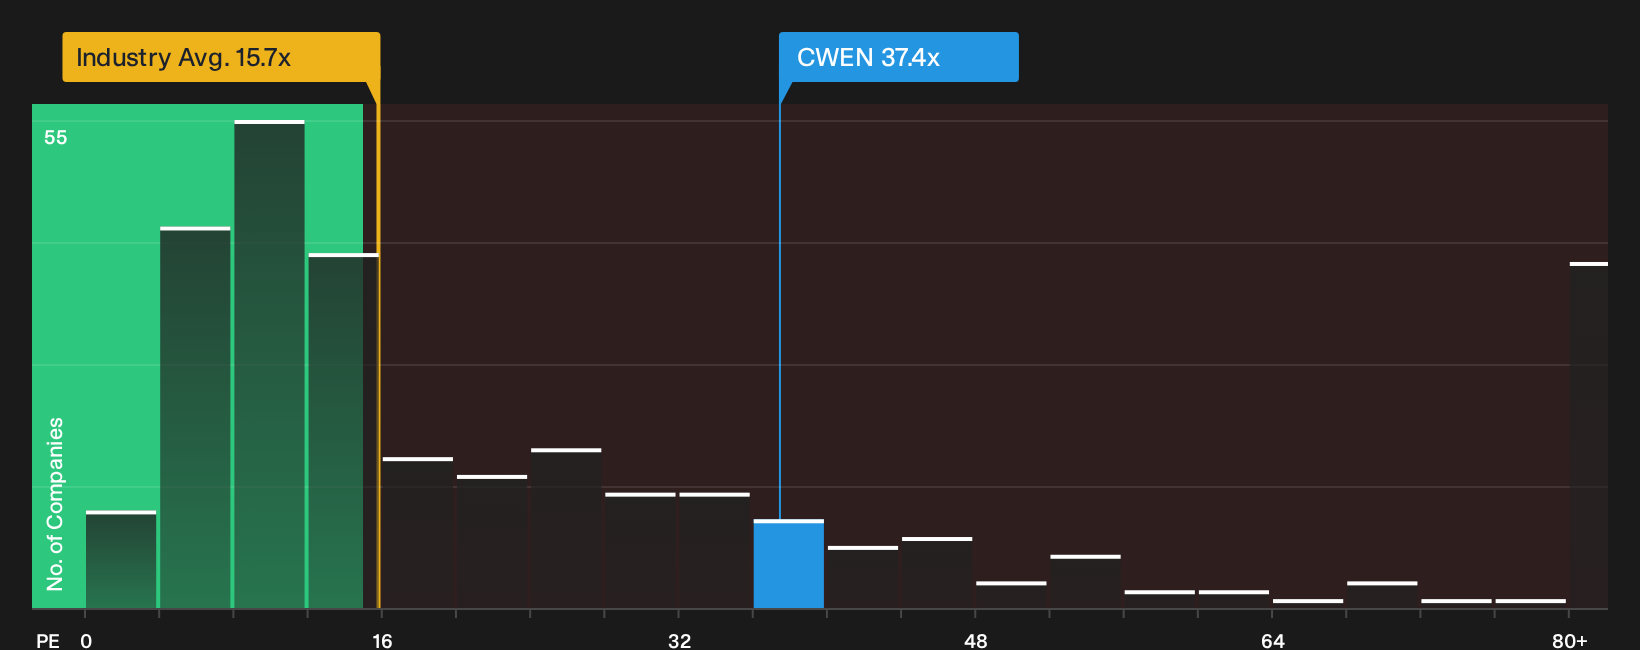
The P/E ratio fits Clearway Energy reasonably well because earnings sit at the center of how many investors judge utility-like cash flow streams. On this metric, the stock trades on about 37.4x earnings. That compares with an average of roughly 15.7x for the wider renewable energy industry, so the shares change hands at a clear premium to the sector.
A more tailored yardstick points to a lower figure. The Fair Ratio for Clearway Energy is estimated at about 28.7x, which is below both the current multiple and the peer average of roughly 33.1x. The gap implies investors are already paying up relative to what this framework suggests for the firm’s size, risk profile and profitability.
On the P/E multiple, Clearway Energy stock screens as overvalued compared with both its fair ratio and renewable energy peers.
See what the numbers say about this price — find out in our valuation breakdown.
The Clearway Energy Narrative: What Would Justify Today's Price?
For Clearway Energy, Simply Wall St Narratives pick up where this valuation puzzle leaves off by spelling out which assumptions on growth, profitability and earnings would need to hold for the share price to look meaningfully higher or lower than it does today. These narratives sit on the platform's Community page. Rather than pointing to a single multiple, each narrative sets out its own drivers behind an implied value so you can compare those expectations with Clearway Energy's actual results as they arrive.
One of the top community narratives on Clearway Energy: roughly fairly valued
"For you as an investor, the key debate centers on how much risk to assign to cash flow delivery, sector headwinds in renewables and the valuation that Clearway Energy now carries..."
Read one of the top narratives on Clearway Energy
Do you think there's more to the story for Clearway Energy? Head over to our Community to see what others are saying!
The Bottom Line
Clearway Energy screens as overvalued on the main market multiples, which suggests the current share price already bakes in optimistic assumptions on future cash generation. Broader checks also lean against a clear value case, since few indicators point to meaningful undervaluation. What matters most from here is whether Clearway Energy can grow cash flows enough to keep justifying a premium P/E, or whether investor expectations eventually cool and the valuation settles closer to sector norms.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com