
Does New CMO Hire Change The Bull Case For Calix Stock (CALX)?
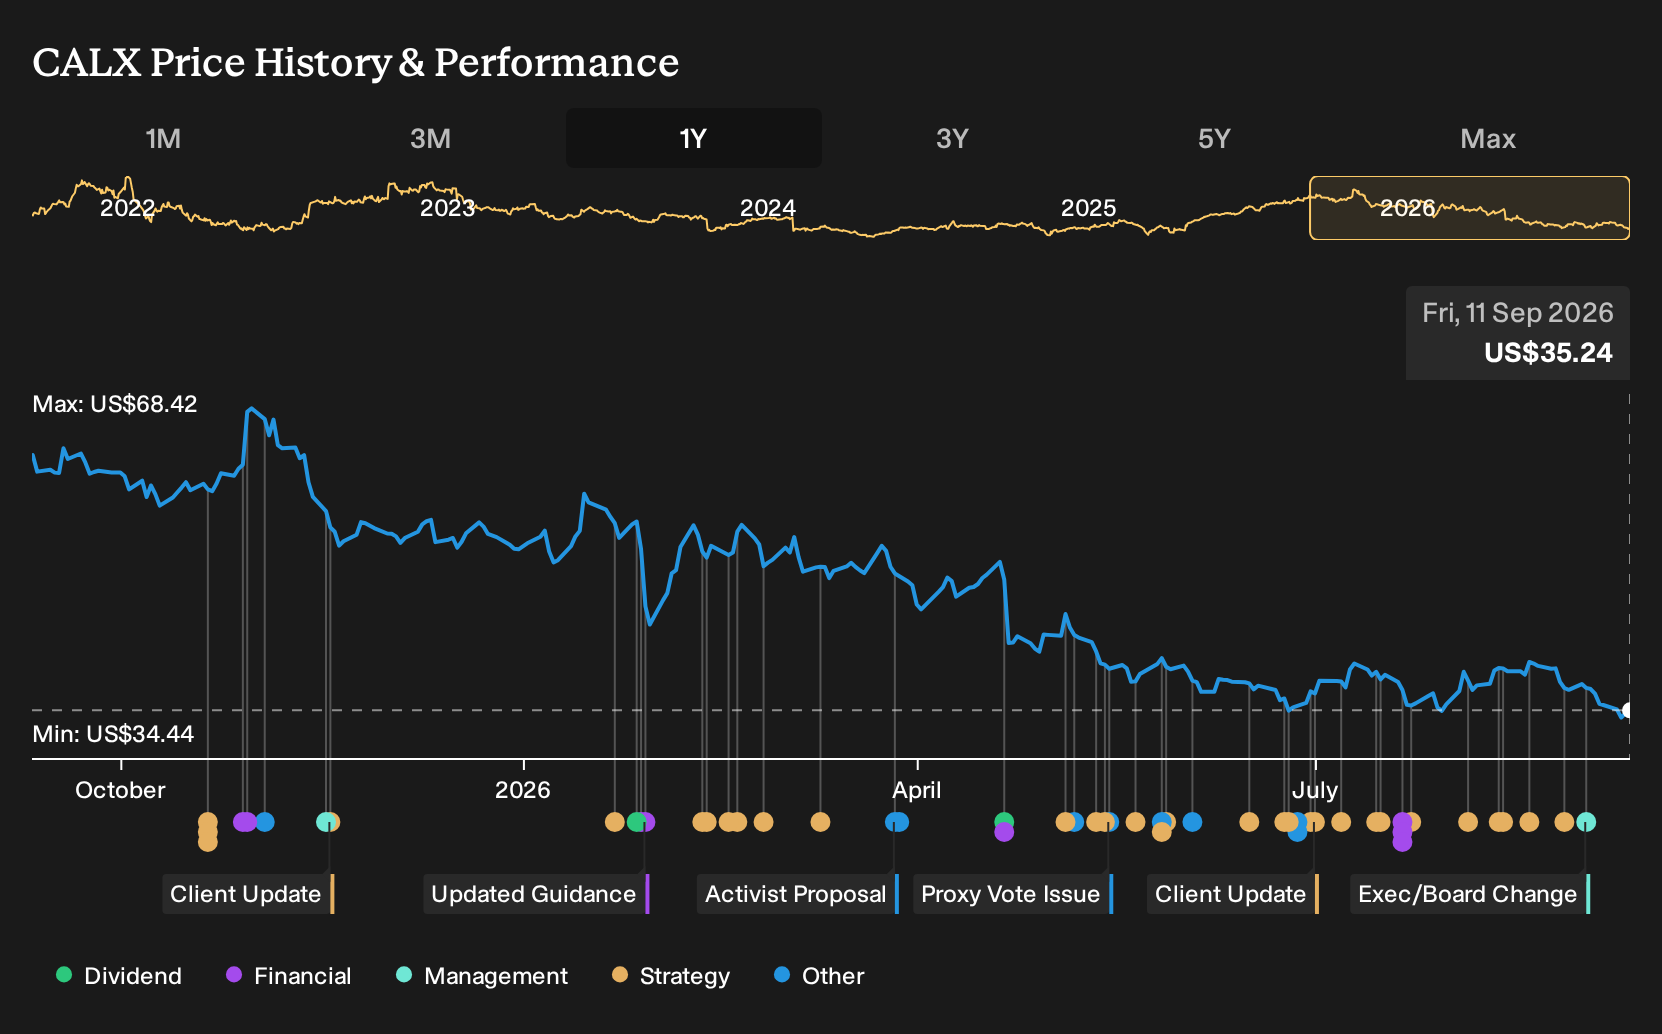
- Calix appointed Juergen Lindner as chief marketing officer in September 2026, adding decades of global tech leadership across SAP, Oracle and ServiceNow.
- The hire brings direct experience commercialising agentic AI and large-scale cloud platforms, which highlights how seriously Calix is treating its AI-native roadmap.
- We will assess how Calix's investment narrative is influenced by this AI-focused marketing leadership change and what it means for execution.
Scan beyond Calix and consider how other AI infrastructure players are positioning their go-to-market engines by evaluating opportunities from our hand-picked 89 AI infrastructure stocks.
Calix Investment Narrative Recap
Owning Calix means believing in its shift toward an AI heavy, cloud first platform, where broadband providers lean more on software, automation, and managed services. The near term story still revolves around execution on the third generation AI platform rollout and what that means for recurring revenue, margins, and customer stickiness.
The key short term catalyst is how quickly service providers adopt agentic AI features and expand usage across residential, business, and municipal segments. The biggest risk is that uptake is slower or more fragmented, especially outside the US where data sovereignty requirements raise complexity. The new CMO hire supports messaging but does not remove those operational risks.
One useful way to view the Juergen Lindner appointment is alongside Calix plans for its third generation platform that integrates agentic AI. The firm is aiming to turn that architecture into higher average revenue per user, lower churn, and more predictable software style income, rather than relying on lumpier hardware projects.
The same launch is also where several risks converge. Customer concentration, tougher competition from telecom and cloud vendors, and the need to manage privacy rules across regions all appear as execution tests for this platform cycle. Stronger marketing leadership can support go to market discipline, but adoption speed and contract quality still depend on customers.
Calix's current story aligns with analyst assumptions that revenue grows at 15.2% a year, reaching a top line of US$1.7b and earnings of US$185.1m by 2029, up from US$51.2m today. This would require earnings to rise about 3.6 times over that period.
Uncover why Calix's fair value points to a 77% potential upside to its current price, which could narrow quickly as sentiment catches up.
Exploring Other Perspectives
One alternate view focuses on slower fiber build capacity rather than AI execution. The most cautious analysts had pencilled in revenue of about US$1.6b and earnings of US$165.7m by 2029, which already reflected concern about that bottleneck. With Calix now hiring an AI heavy CMO, those pessimistic assumptions may shift. You can compare both narratives and decide which feels closer to your own expectations.
Explore 5 other Calix fair value estimates, including one that suggests it could be worth just $52.00!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Calix research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Calix. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Calix's overall financial health at a glance.
Looking For More Investment Ideas Beyond Calix?
Once you have a handle on Calix, it can help to widen the lens and compare it with other opportunities that match your preferred risk, quality, and income profile using the Simply Wall St Screener.
- If you want potentially higher upside with tighter budgets, review a hand picked set of smaller companies through the 21 elite penny stocks with strong financials.
- For investors who care most about quality and value, scan a curated pool of resilient businesses through the 31 high quality undervalued stocks.
- Anyone prioritising balance sheet strength and fundamental resilience can start with the list of solid balance sheet and fundamentals (23 results) to see which companies fit that brief.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com