
First Horizon (FHN) Stock Looks Cheap On Fair Value While Earnings Look Fair
First Horizon has delivered a very strong 3 year share gain while the current valuation work suggests the stock may still be pricing in a meaningful discount to its intrinsic value. The Excess Returns model points to an intrinsic value estimate well above the recent market price, while traditional earnings based multiples look broadly in line with peers.
- Over the past 3 years, First Horizon has returned 135.8%, which puts recent trading in the context of a long and already substantial move.
- Analysts at Morgan Stanley highlight First Horizon’s differentiated, more countercyclical business mix as a potential engine for organic growth, but the outlook for capital return and the wider banking cycle still adds uncertainty to how that growth may be valued.
- On Simply Wall St’s broader checks, First Horizon earns a high value score of 5 out of 6, which indicates the shares screen as cheap across most valuation angles rather than fairly priced.
The issue now is whether First Horizon’s recent share price around US$24.47 already reflects the Excess Returns upside or if the intrinsic value estimate still leaves a margin that matters to long term investors.
Scan beyond First Horizon’s 135.8% three year run and find other high quality stocks that still screen as undervalued with 31 high quality undervalued stocks in one place.
Does First Horizon Look Undervalued on Excess Returns?
The Excess Returns model starts by asking whether First Horizon is earning more on its equity base than shareholders require. On the latest inputs, the bank is working off a Book Value of $17.91 per share and an Average Return on Equity of 12.06%, which feeds into a Stable EPS estimate of $2.37 per share. With a calculated Cost of Equity of $1.42 per share, that leaves an Excess Return of $0.95 per share and a Stable Book Value of $19.69 per share.
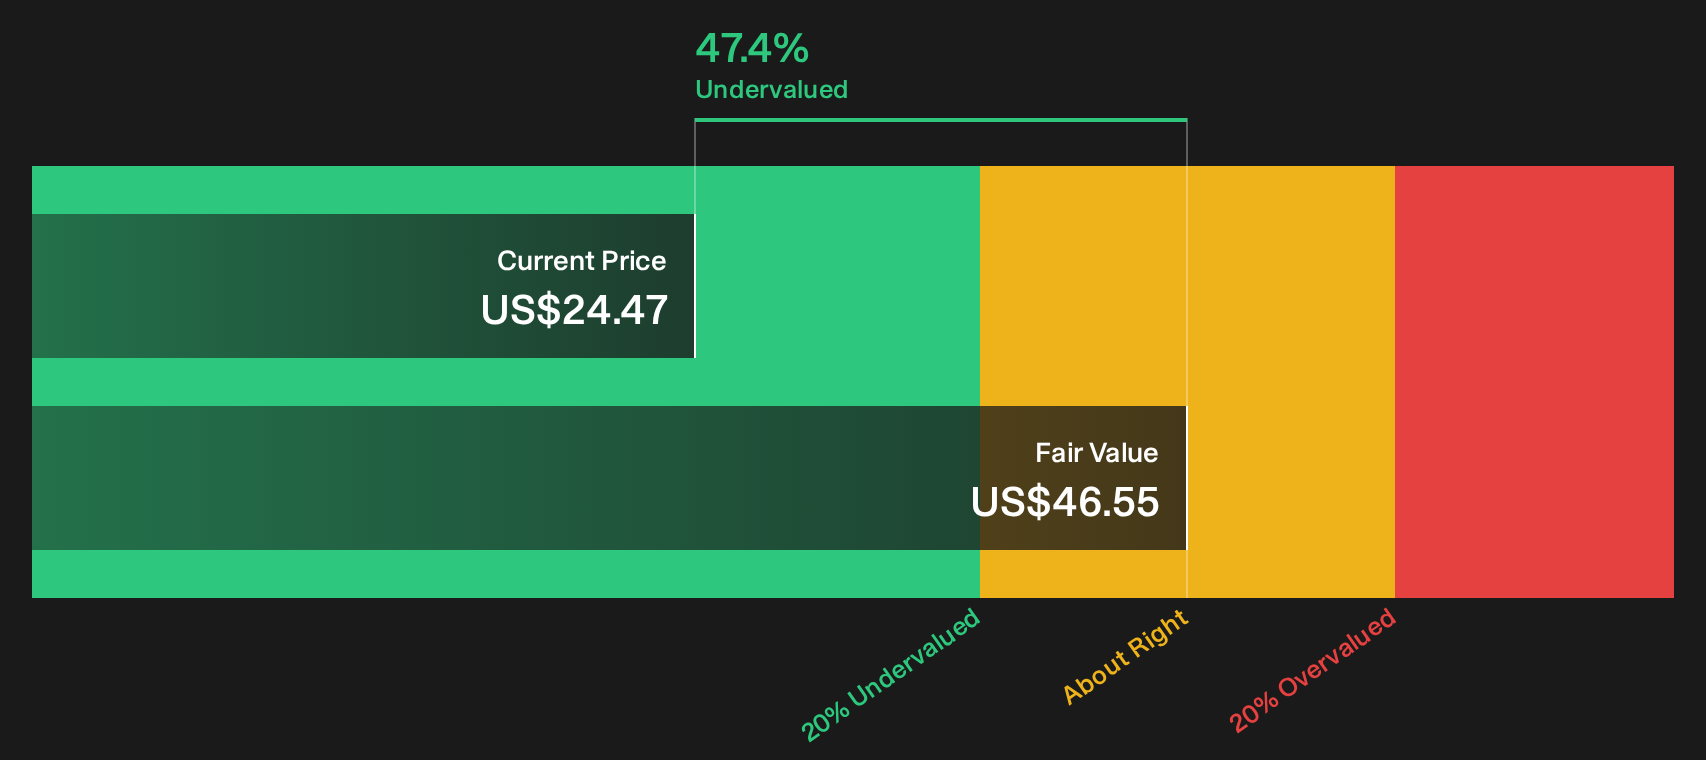
Rolling those excess profits forward produces an intrinsic value estimate of $46.55 per share, well above the recent share price around $24.47, which implies the stock screens as about 47.4% undervalued on this framework. Because Morgan Stanley highlights First Horizon as well positioned for organic growth with a more countercyclical mix, the current discount suggests investors are still hesitant to fully pay up for those future returns. The Excess Returns workup points to First Horizon stock looking undervalued relative to what its projected profitability and equity base would justify.
Our Excess Returns analysis suggests First Horizon is undervalued by 47.4%. Track this in your watchlist or portfolio, or discover 31 more high quality undervalued stocks.
Where Does First Horizon Sit on Earnings?
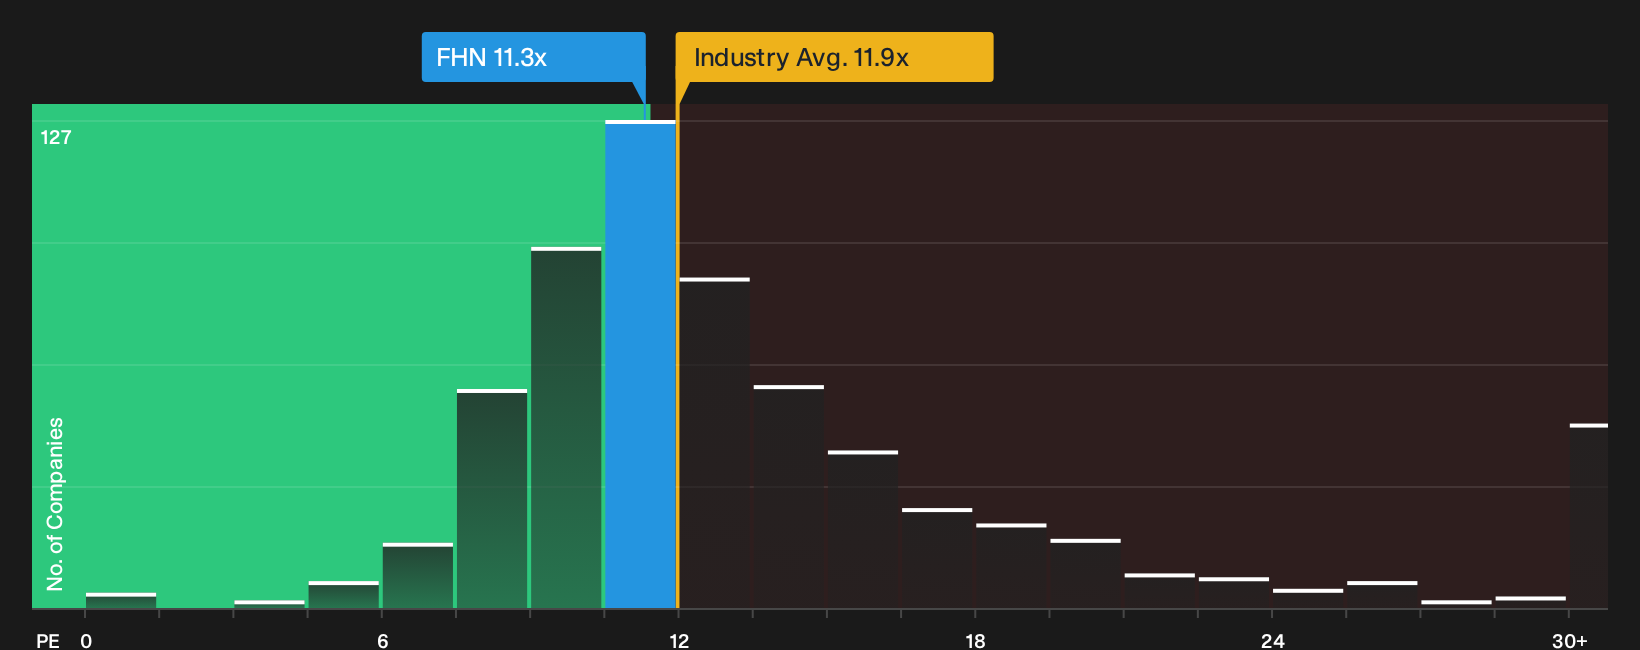
P/E works well for banks like First Horizon because earnings and capital needs tend to move more in step than sales alone. On this metric, the stock trades on a P/E of 11.3x, which is slightly below the Banks industry average of 11.9x and just under the peer group on 11.7x.
The tailored fair P/E ratio from the model is 12.1x, which is only a modest premium to where First Horizon changes hands today. That gap suggests the market price lines up reasonably closely with what the company’s earnings profile, size and risk mix would support, rather than showing a clear discount or an aggressive premium.
On the P/E yardstick, First Horizon looks priced roughly in line with what its earnings and risk profile would justify.
See what the numbers say about this price — find out in our valuation breakdown.
The First Horizon Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the valuation gap on First Horizon leaves off by spelling out what kind of future for growth, profitability and earnings would need to play out for the stock to be worth materially more or less than today’s price. Each scenario links its number to a clear view on how First Horizon's revenues, margins and risk profile might evolve, so you can come back to that framework as fresh information lands on the Community page.
Add your own narrative on First Horizon to provide a clear, numbers-based view on whether Morgan Stanley’s organic growth thesis really delivers. Be one of the first voices in the Simply Wall St community to set out that case and see how it holds up as new results and news arrive.
Do you think there's more to the story for First Horizon? Head over to our Community to see what others are saying!
The Bottom Line
First Horizon screens as undervalued on the Excess Returns intrinsic value work, while the earnings multiple view points closer to about right against peers. That mix suggests the gap now hinges less on obvious mispricing and more on whether the bank converts its current profitability profile into sustained excess returns on equity. The crux for investors is simple. The call turns on whether the market eventually pays more for that earnings stream or keeps discounting the story because of uncertainty around the banking cycle and capital returns.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com