
Dell (DELL) Stock Looks Below Fair Value While Cash Flow Says Fairly Priced
Dell Technologies has delivered a very large 5 year return while current valuation checks send a more restrained message, with the Discounted Cash Flow (DCF) estimate pointing to a fairly valued stock and earnings multiples still screening on the cheap side. For anyone looking at Dell Technologies today, the question is how to treat a share price near record levels when the main models do not give a clear bargain or clear premium.
- The stock has returned about 11.3x over 5 years, which raises the bar for any new buyer who now has to judge whether that kind of compounding already reflects most of the good news.
- Heavy interest in Dell Technologies AI focused infrastructure and servers can support revenue visibility, while the planned US$4b bond raise and ongoing capital needs for data center build outs may constrain how much flexibility management has to return cash to shareholders.
- The broader toolkit, including the 3.0 value score, points to a mixed picture rather than a straightforward bargain or an obviously expensive stock.
The stock's next move may depend on whether Dell Technologies recent gains leave enough upside relative to its intrinsic value estimate and current market multiples.
Spot fresh AI infrastructure momentum plays by scanning 89 AI infrastructure stocks that echo Dell Technologies surge, without relying on a single stock for the whole bet.Where Does Dell Technologies Sit on Cash Flow?
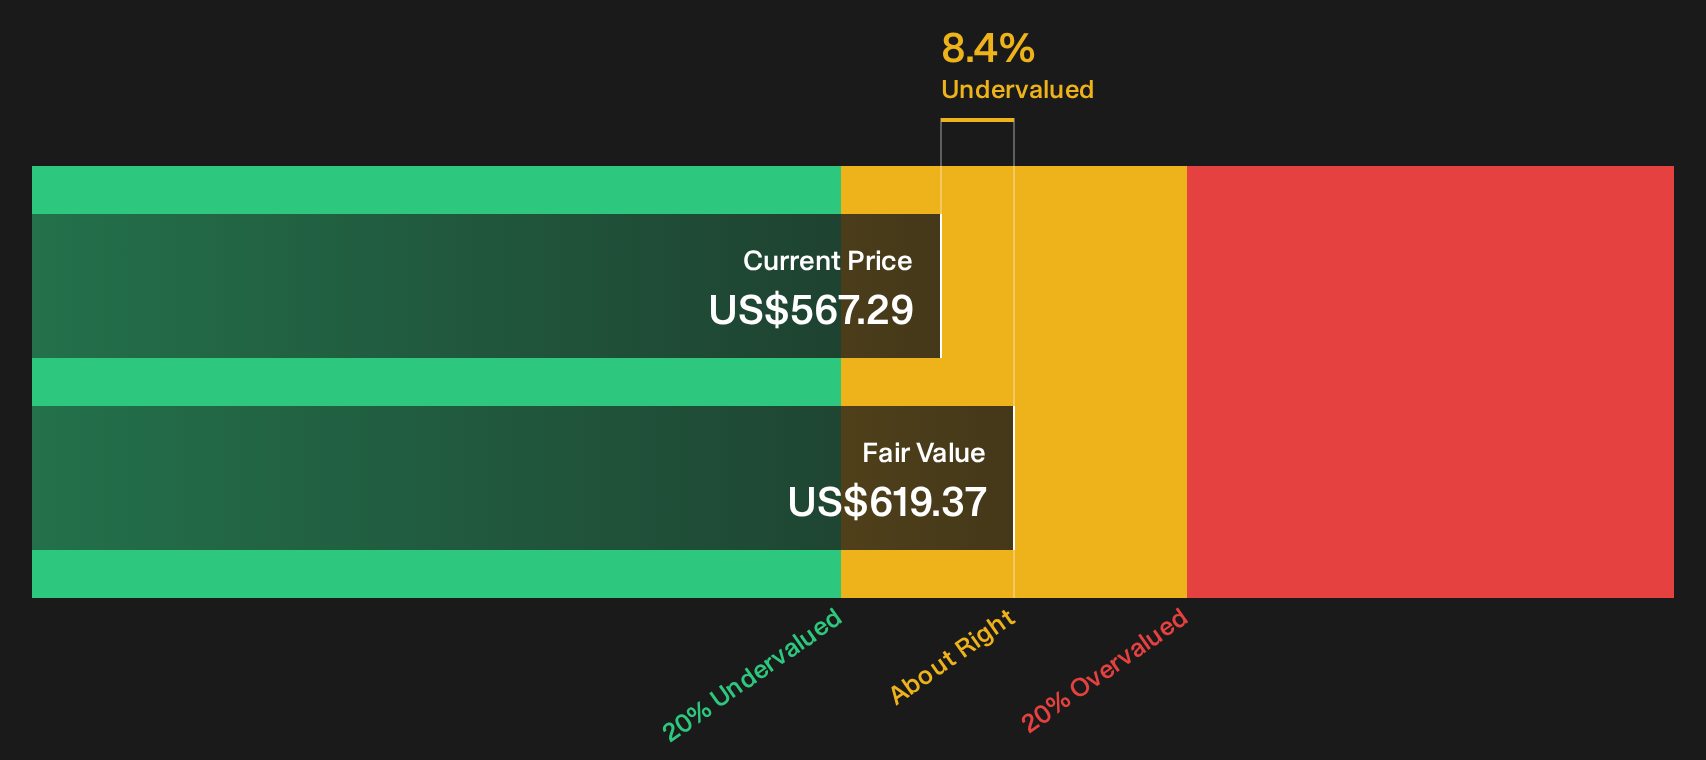
The Discounted Cash Flow (DCF) method values a company based on the cash it is expected to generate for shareholders. For Dell Technologies, the model starts from latest twelve month free cash flow of about $8.2b, then assumes those cash flows keep growing rather than shrinking, which supports a higher long run equity value.
On those assumptions, the DCF output lands at an estimated intrinsic value of about $619 per share, which is roughly 8.4% above the current price. Recent discussion around Dell Technologies AI server demand and the RBC Outperform rating help explain why the market price has already moved close to this modeled value. Put together, the cash flow outlook and the current quote suggest Dell Technologies appears close to fairly valued on this DCF view.
Dell Technologies is fairly valued according to our Discounted Cash Flow (DCF), but this can change at a moment's notice. Track the value in your watchlist or portfolio and be alerted on when to act.
Is Dell Technologies Still Cheap on Earnings?
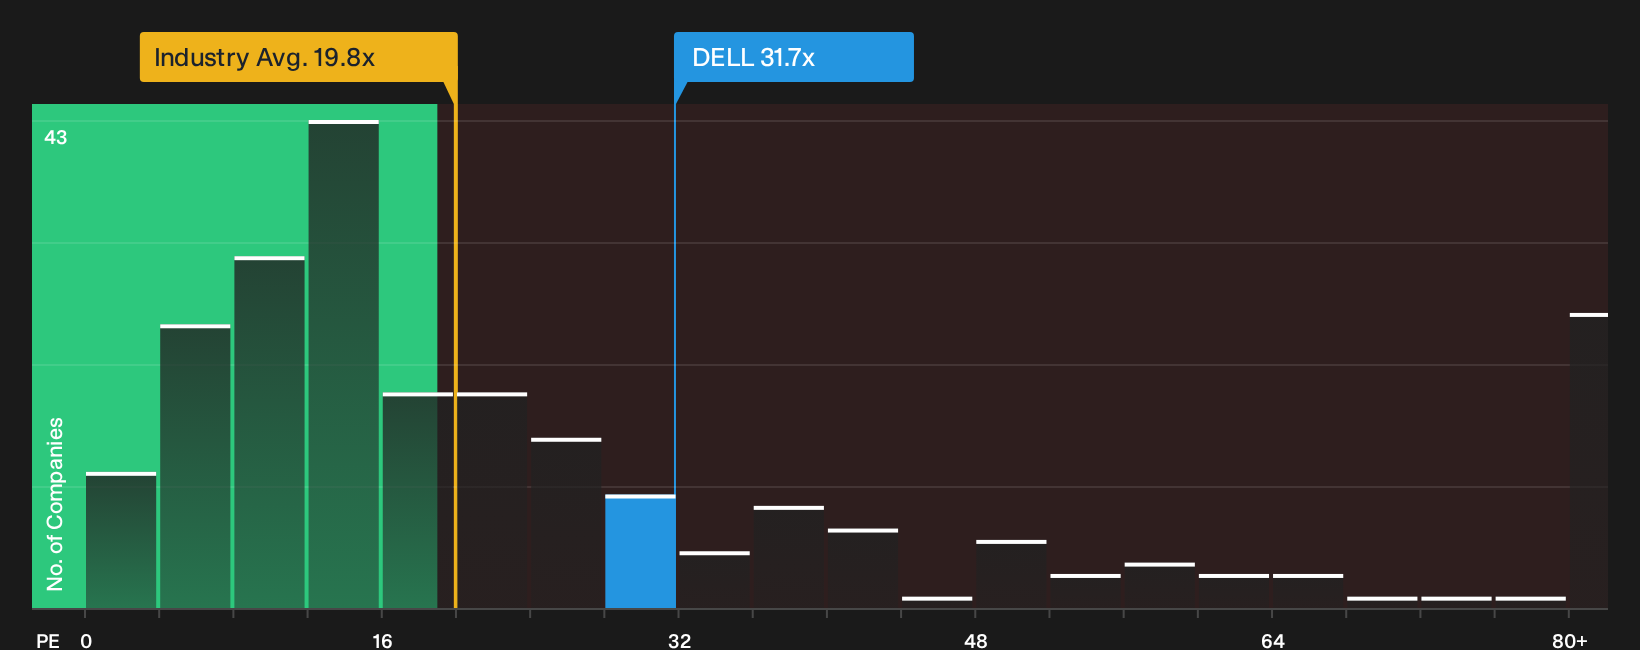
The P/E ratio fits Dell Technologies well because earnings remain a core yardstick for a mature hardware and infrastructure business. On this metric, the stock trades at about 31.7x earnings, almost in line with the 32.1x peer average and well above the broader tech sector on roughly 19.8x. That indicates investors are willing to pay a premium to the wider industry for Dell Technologies earnings, but are pricing it broadly in line with closer peers.
The fair P/E ratio from the model is higher at about 43.8x. The current 31.7x level therefore comes in meaningfully below what would be expected once factors such as scale, margins and risk profile are blended in. Even after the AI driven enthusiasm and recent record share price, Dell Technologies still appears on the undervalued side using this earnings based check.
On the P/E yardstick, Dell Technologies currently looks undervalued relative to what the model suggests would be a fair earnings multiple.
See what the numbers say about this price — find out in our valuation breakdown.
The Dell Technologies Narrative: What Would Justify Today's Price?
Narratives on Dell Technologies pick up where the mixed DCF and P/E signals leave off. They spell out which paths for growth, profitability and earnings would need to play out for the stock to be worth materially more or less than it trades for today on Simply Wall St's Community page. Each storyline ties its number to a clear view on how revenue expansion, margin shape and business risks could evolve, giving you a reference point to revisit as fresh data comes through.
Community views on Dell Technologies split sharply between an AI infrastructure boom story and a hardware margin risk story.
Bull case: 13% undervalued
"Dell's industry-leading pace of bespoke engineering and partnerships with NVIDIA, Google, and AMD is shortening customers' deployment timelines dramatically, making Dell the preferred partner for large-scale, next-generation AI clusters…"
Read the full Bull Case to see why Dell Technologies could be undervalued
Bear case: roughly fairly valued
"Growth in AI server revenues is currently rate (margin) dilutive, as management highlighted; even record AI shipments are accompanied by lower operating income rates and low incremental conversion margins (approximately 2 to 2.5%)…"
Read the full Bear Case to see why Dell Technologies could be overvalued
Do you think there's more to the story for Dell Technologies? Head over to our Community to see what others are saying!
The Bottom Line
Dell Technologies screens as roughly in line with its Discounted Cash Flow (DCF) intrinsic value, while the P/E work still tilts to undervalued. That split comes from the DCF model weighing heavy cash needs and timing of returns, whereas the earnings multiple leans on market expectations for AI driven demand and peer re rating. With such a sharp prior move in the share price, the key issue is whether AI infrastructure orders can support both margins and reinvestment without eroding that earnings based discount. Your decision depends on whether current enthusiasm for Dell Technologies AI servers is durable enough to justify today’s valuation tension between cash flows and multiples.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com