
Is UBS Group (SWX:UBSG) Fully Valued Following Its Debt Tender And New Note Issuance?
UBS Group (SWX:UBSG) has just wrapped up a large debt tender program, agreeing to repurchase about $7.93b of outstanding notes after lifting its maximum purchase size to roughly $5.85b in total consideration.
UBS Group’s shares trade at CHF44.56 after a 1 day share price return of 1.39% and a 90 day share price return of 14.55%. The 1 year total shareholder return of 41.25% and 5 year total shareholder return of 233.69% point to strong momentum that recent debt tender and issuance activity may be reinforcing, as investors reassess both funding costs and perceived risk around the balance sheet.
Scan how UBS Group’s debt moves compare with other balance sheet focused opportunities by reviewing our curated list of 97 resilient stocks with low risk scores today.
Bulls see UBS Group retiring expensive notes and issuing fresh paper as a value unlock for equity holders. Bears see a complex balance sheet shuffle. Which story does the valuation actually back up?
Most Popular Narrative: 1% Overvalued
UBS Group’s widely tracked fair value of CHF44.11 sits just below the last close at CHF44.56. The gap is narrow, so the real story lies in the assumptions.
The ongoing integration of Credit Suisse is progressing ahead of schedule, driving meaningful cost savings, increased scale, and improved operating efficiency. As these synergies are realized through further platform migration and operational streamlining, UBS's net margins and return on equity are likely to improve, supporting higher earnings growth.
Read the complete narrative. Read the complete narrative.
Want to see what kind of revenue path and margin profile are baked into that fair value for UBS Group? The narrative leans heavily on efficiency gains, richer fee income, and a different future earnings mix than today. Curious which specific growth and profitability assumptions have to land for that CHF44.11 estimate to hold up.
Result: Fair Value of CHF44.11 (OVERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, UBS Group faces real tripwires, including tighter Swiss capital rules that could tie up an extra US$24b to US$42b and lingering Credit Suisse integration execution risk.
Find out about the key risks to this UBS Group narrative.
Another View on UBS Group’s Valuation
The analyst narrative has UBS Group looking roughly 1% overvalued around CHF44.56 versus a fair value of CHF44.11. A different lens tells another story. The SWS DCF model estimates fair value at CHF67.51, which implies the shares trade at a sizeable discount instead.
This gap between an earnings based fair value and the future cash flow view raises a simple question. Which set of assumptions do you trust more: the near term profit path or the longer term cash generation profile?
Look into how the SWS DCF model arrives at its fair value.
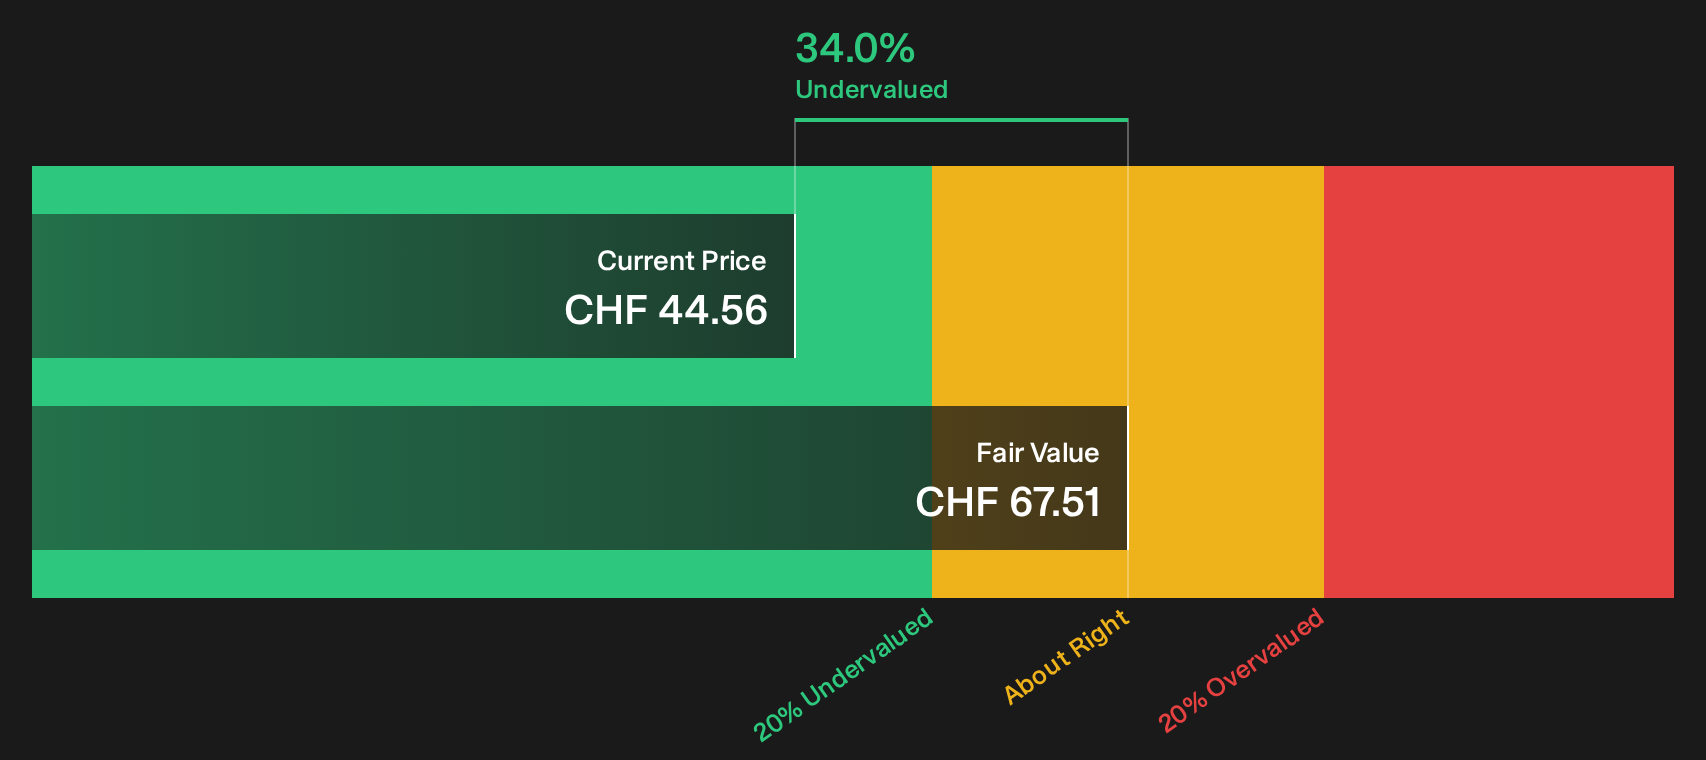
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out UBS Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 183 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages so far on UBS Group, with both risks and rewards on the table and plenty of moving parts still in play. If you want to move quickly and form your own view based on the full spread of concerns and potential upsides, start by weighing the 3 key rewards and 4 important warning signs.
Looking for more investment ideas beyond UBS Group?
If UBS Group has sharpened your focus on risk, reward, and valuation, broaden your watchlist now with a few targeted screens built around different edges.
- Zero in on quality at a discount by checking companies that surface in the 183 high quality undervalued stocks.
- Strengthen your income game by scanning potential high yield opportunities with the 164 dividend fortresses.
- Prioritise resilience by reviewing companies highlighted in the list of solid balance sheet and fundamentals (193 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com