
Avient (AVNT) Stock Looks Reasonable Relative To Fair Value
Avient has delivered a solid 30.6% gain year to date, yet its valuation checks suggest the current share price may still sit below a conservative view of the company’s long term cash generating potential.
- The year to date return of 30.6% signals that investors have already priced in a meaningful recovery story for Avient.
- Future cash flow growth from specialty materials may support the current share price, while any pressure on volumes or pricing could weigh heavily on those cash flow expectations.
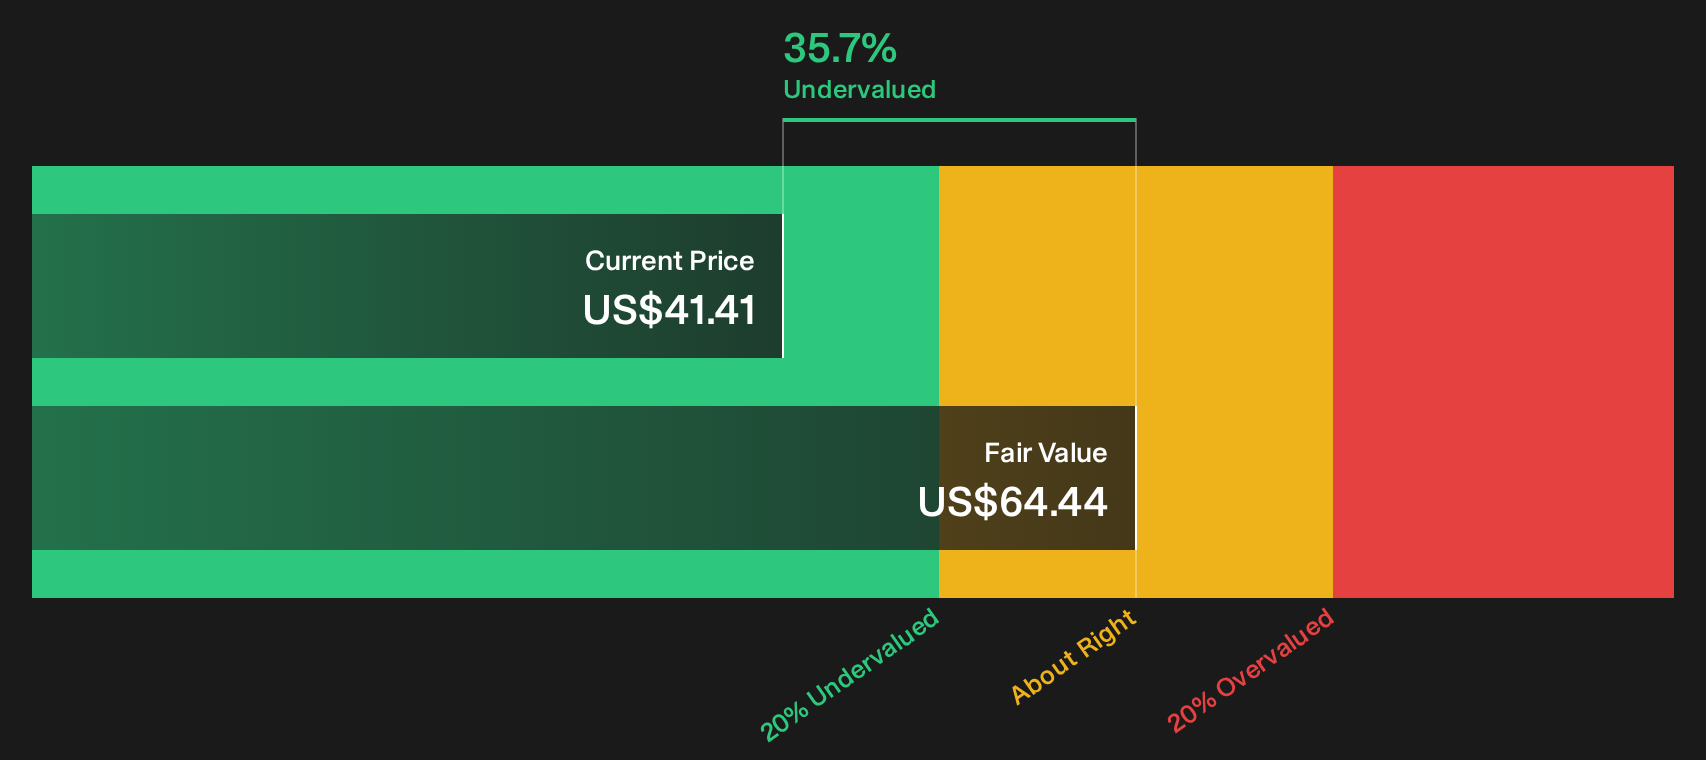
- The broader checks lean cheap, with Avient scoring 6 out of 6 on value tests, and the Discounted Cash Flow (DCF) estimate sitting about 35.7% above the market price.
The issue now is whether that apparent discount to intrinsic value provides enough margin of safety after this year’s strong run in Avient stock.
Compare Avient’s valuation gap with a curated group of other potential mispriced opportunities by scanning 31 high quality undervalued stocks that pair solid cash generation with balance sheet strength.
Is Avient Still Cheap on Cash Flow?
The Discounted Cash Flow (DCF) approach here aims to translate Avient’s expected free cash generation into a per share estimate today. On the latest twelve month numbers, Avient has Free Cash Flow of about $181.7 million, and the model assumes that cash generation grows from this base rather than shrinking. Feeding those projections into a 2 Stage Free Cash Flow to Equity framework produces an intrinsic value estimate of about $64.44 per share.
Set against the current market price, that DCF output indicates the stock trades at roughly a 35.7% discount to this cash flow based value. For an investor focusing on Avient, the key question is whether the assumed improvement in free cash flow is realistic enough to rely on. Even allowing for that judgment call, the gap between the calculated value and the quoted price is wide enough to be considered meaningful.
On this DCF view, Avient appears undervalued relative to the cash flows the business is expected to produce according to the model’s assumptions.
Our Discounted Cash Flow (DCF) analysis suggests Avient is undervalued by 35.7%. Track this in your watchlist or portfolio, or discover 31 more high quality undervalued stocks.
Is Avient Fairly Priced on Earnings?
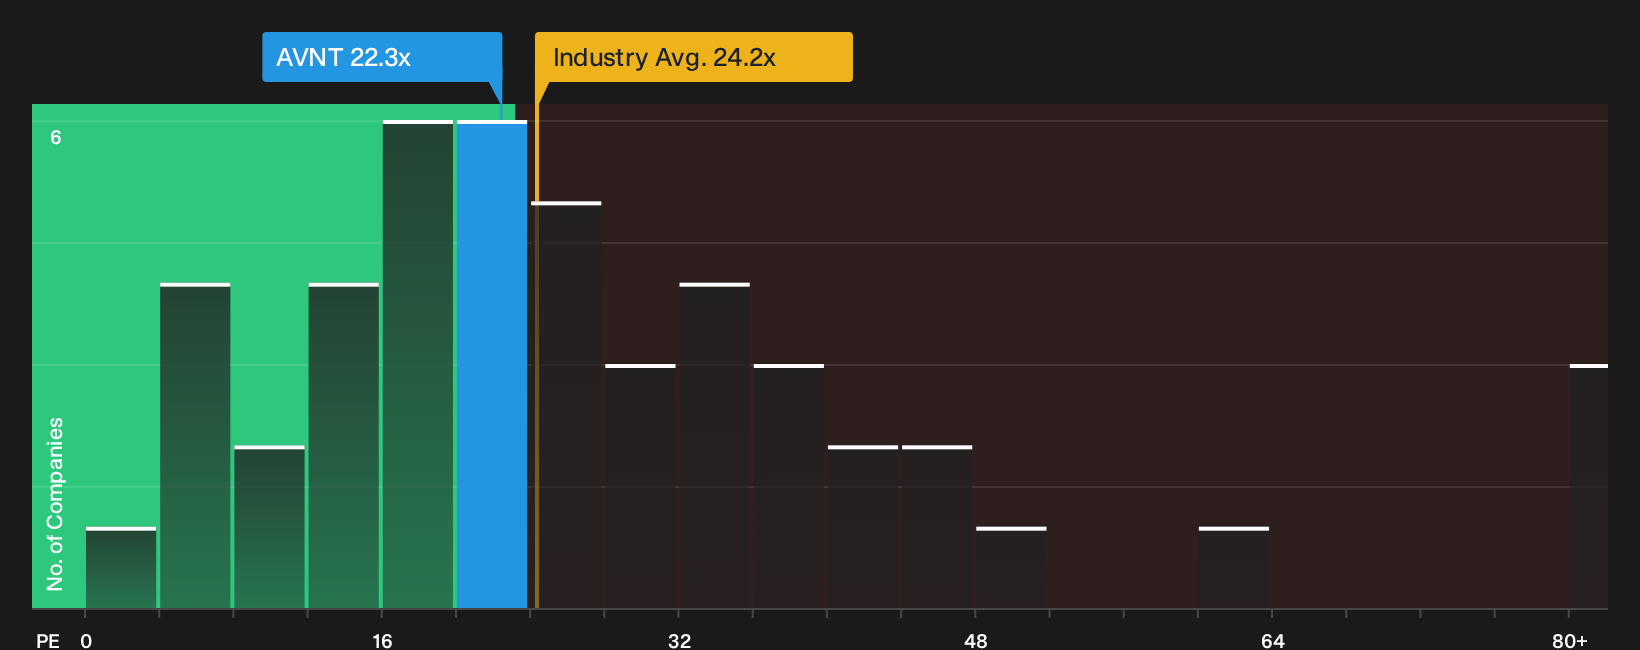
The P/E ratio fits Avient well because earnings remain a key reference point for how the market values specialty chemicals producers. Avient trades on a P/E of about 22.3x, which is slightly below the broader chemicals industry average near 24.2x and also beneath the peer group average of roughly 29.4x. That places the stock on a moderate earnings multiple rather than a clearly cheap or expensive one.
The valuation model that blends Avient’s growth profile, profitability, sector and risk suggests a fair P/E of around 22.5x. That sits very close to where the shares currently change hands, so the gap between price and this tailored benchmark is small. Investors weighing the DCF upside against this earnings-based check are looking at a business that the market is pricing in line with what the model suggests for its earnings power.
On the P/E yardstick, Avient looks roughly fairly valued against both its tailored fair multiple and the wider chemicals sector.
See what the numbers say about this price — find out in our valuation breakdown.
The Avient Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Avient pick up where these valuation checks leave off. They spell out the specific paths for Avient's growth, profitability and earnings that would need to play out for the shares to be worth much more or much less than the current price, and where a single ratio or model offers one headline figure, Narratives lay out the future that figure rests on so you can watch in real time whether it is still on track. These are available on Simply Wall St's Community page for investors who want to connect the numbers to concrete business outcomes.
One of the top community narratives on Avient: 10% undervalued
"Recent Street research on Avient has centered on higher price targets and continued Buy ratings, with analysts pointing to revenue growth, margin expansion, and what they see as better execution on pricing and mix…”
Read one of the top narratives on Avient
Do you think there's more to the story for Avient? Head over to our Community to see what others are saying!
The Bottom Line
Avient screens as undervalued on a Discounted Cash Flow (DCF) view, while the P/E check points to a stock that the market already prices at roughly the going rate for its earnings power. The broader valuation work therefore hinges on whether future free cash generation actually tracks the intrinsic value estimate rather than the more cautious multiple view. For investors, the key question is straightforward: whether Avient can translate its specialty materials focus into steady, defendable cash flows that justify treating the current discount as an opportunity rather than a warning signal.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com