
Cipher Digital (CIFR) Stock May Be Priced For Perfection Despite Strong Sales Growth
Cipher Digital stock has delivered a very large 3 year gain, yet on the current checks it still screens as expensive and not a clear bargain. Recent share price weakness sits against that backdrop, which puts extra focus on whether the recent story and pricing are aligned.
- The share price has risen very roughly 7x over the past 3 years, which leaves little room for disappointment if expectations ease.
- New Texas high performance computing and AI data center projects, including gas pipeline backed power plans, can support long term capacity growth. At the same time, heavy capital needs and ERCOT interconnection uncertainty may weigh on how investors think about the valuation.
- The broader valuation workup is cautious, with a low value score of 0 out of 6 checks, which suggests Cipher Digital does not currently look like a clear bargain on these metrics.
The issue now is whether Cipher Digital’s current share price leaves enough margin for error given its recent gains and the risks around its build out plans.
Scan beyond Cipher Digital and compare its AI infrastructure story with 89 AI infrastructure stocks, which could also be gearing up for major data center and high performance computing demand.
Has Cipher Digital Run Too Far on Sales?
P/S is a useful yardstick for Cipher Digital because the business is still loss making and investors are primarily paying for revenue and future capacity rather than current earnings.
The stock trades on a P/S of 36.6x, which is far above the broader software industry average of about 3.9x and ahead of the peer average of roughly 4.9x. The tailored fair multiple from the model is 5.3x. Even allowing for the high build-out ambitions and AI data center angle, there is a wide gap between what the framework suggests and where the market is currently pricing the shares.
The recent headlines around Pentagon-linked AI infrastructure financing and Texas power projects have increased attention on Cipher Digital. However, the current sales multiple already reflects a significant level of optimism compared with typical software peers.
On this P/S yardstick, Cipher Digital currently appears overvalued and priced for a very ambitious outcome.
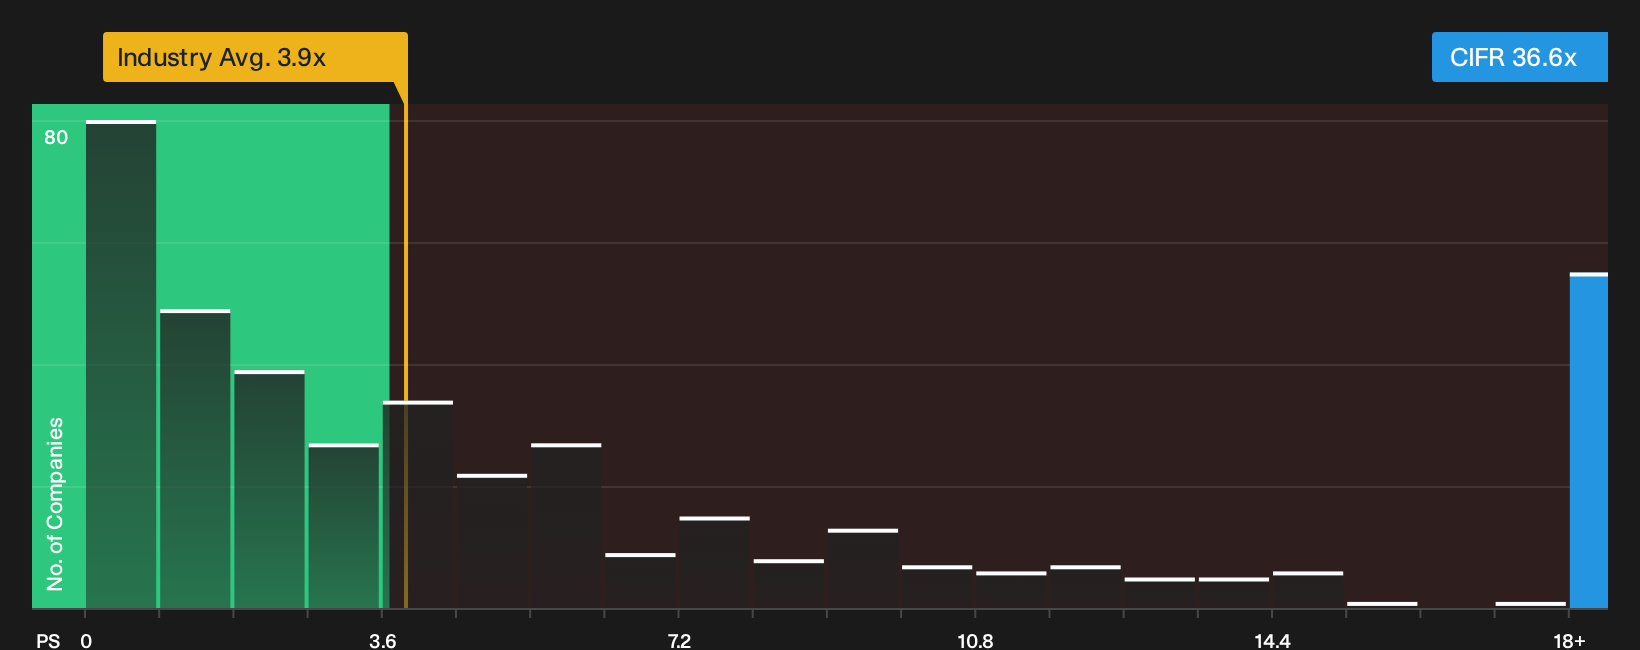
See what the numbers say about this price — find out in our valuation breakdown.
The Cipher Digital Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Cipher Digital valuation puzzle leaves off by spelling out which combinations of growth, margins and earnings would need to play out for the stock to be worth materially more or less than today's price. Each Narrative ties a fair value estimate to a specific version of Cipher Digital's potential catalysts and risks, so you can watch over time which of those stories seems closest to reality on the Community page.
One of the top community narratives on Cipher Digital: 49% undervalued
"Industry wide demand for large scale, flexible, and energy rich data center sites driven by accelerating institutional and mainstream adoption of digital assets and AI aligns with Cipher's strategy…"
Read one of the top narratives on Cipher Digital
Do you think there's more to the story for Cipher Digital? Head over to our Community to see what others are saying!
The Bottom Line
Cipher Digital now screens as overvalued on simple sales multiples, with a wide gap between where the market prices the shares and where the modelled fair P/S sits. That stretch largely reflects investors paying up for future AI data center capacity and power optionality rather than current profits. The key question from here is whether execution on the Texas build out, including capex, interconnection timing and power security, can progress smoothly enough to justify that optimism instead of forcing a reset in expectations.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com