
Earnings Beat Might Change The Case For Investing In Otis Worldwide (OTIS)
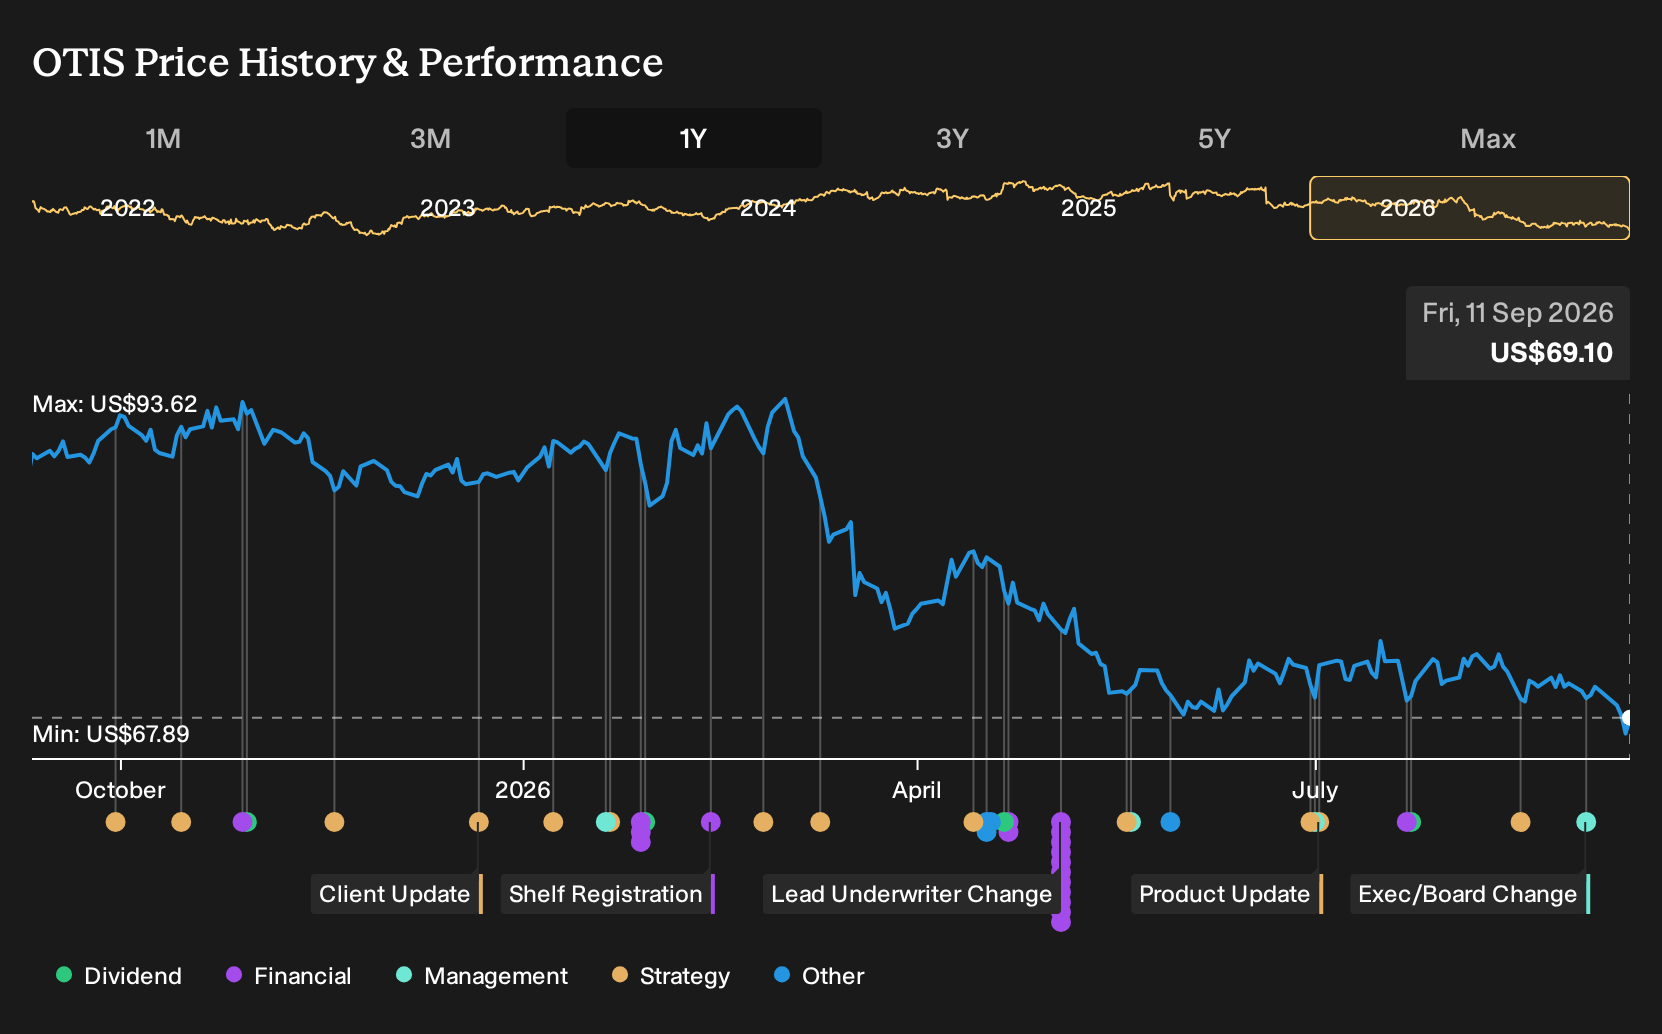
- Otis Worldwide has appointed Sridhar Rajagopal as Managing Director for Southeast Asia, effective 1 September 2026. He will be responsible for regional growth strategy and customer engagement after more than 15 years in leadership roles across Asia Pacific.
- The appointment comes soon after Otis reported quarterly results that exceeded Wall Street expectations despite weaker new-equipment demand in China. This highlights how management focus has shifted toward execution, service quality and modernization to support the wider business.
- We will now look at how Otis Worldwide's investment narrative could shift in light of resilient earnings guidance despite China weakness.
Otis Worldwide Investment Narrative Recap
To own Otis Worldwide, you have to be comfortable with a story that leans on service and modernization to carry the weight while new equipment faces a tougher backdrop. The near term swing factor remains how effectively the business converts its record modernization and service backlog into cash without letting pricing or execution slip.
The biggest risk still sits in weaker new installations and pricing pressure in China alongside softer commercial real estate activity elsewhere. The new Southeast Asia leadership move does not fundamentally change that near term setup, although better execution and customer retention in that region could gradually support the service mix.
The appointment of Sridhar Rajagopal as Managing Director for Southeast Asia matters most for Otis Worldwide’s service and modernization angle. His background across mergers and acquisitions, sales and marketing, and business strategy in Asia Pacific lines up with a model that relies on recurring maintenance work and upgrades to older elevators for a larger share of profit.
For you as a shareholder, the interest is in whether this leadership shift helps Otis capture more modernization projects and long term service contracts in Southeast Asia while China equipment demand remains under pressure. Execution on that front would speak directly to the main catalyst, namely growth in high margin recurring revenue, and would also help offset the risk from slower new builds in other regions.
Otis Worldwide’s current earnings are about US$1.5b and analysts project earnings of US$2.0b by 2029. This implies an increase of roughly US$500m and forecast revenue of US$17.3b by that same year, with the analyst narrative built around revenue growing by 5.1% per year over the next few years.
Uncover why Otis Worldwide's fair value indicates a 29% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view on Otis Worldwide focuses heavily on margin risk. The most cautious analysts already projected revenue of about US$16.9b and earnings near US$1.9b by 2029, with only 4.2% annual revenue growth and a P/E of 18.4x. This is a cooler story than consensus, and this new Southeast Asia hire may prompt those assumptions to be revisited.
Explore 5 other Otis Worldwide fair value estimates, including one that suggests as much as 6% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Otis Worldwide research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Otis Worldwide. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Otis Worldwide's overall financial health at a glance.
Looking For More Investment Ideas Beyond Otis Worldwide?
If the Otis Worldwide story has you thinking about portfolio balance, this is a good moment to scan for other businesses that match your risk, income, and quality preferences using the Simply Wall St Screener.
- If you want potential mispricing with quality fundamentals, start with a focused list of 31 high quality undervalued stocks that may warrant a closer look on your watchlist.
- If income is your priority, broaden your research with a curated set of 6 dividend fortresses that combine meaningful yields with detailed payout data.
- If capital preservation comes first, filter for stability using a hand picked 11 resilient stocks with low risk scores that score well on balance sheet strength and risk metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com