
Hewlett Packard Enterprise (HPE) Stock May Be 32% Undervalued As AI Outlook Rises
Hewlett Packard Enterprise stock has logged a very strong five year run, yet both an intrinsic value check and earnings multiples still point to the shares pricing in less than the modelled worth of the business. That mix of a big past gain and lingering valuation gap is what investors now need to weigh.
- Over the past five years, Hewlett Packard Enterprise has returned about 423.4%, which is a very large gain and sets a high bar for any further upside to feel justified.
- Heavy demand for Hewlett Packard Enterprise AI servers and networking gear can support expectations for future cash flows, while any slowdown in that AI related spending or supply constraints may undermine those assumptions and weigh on the valuation.
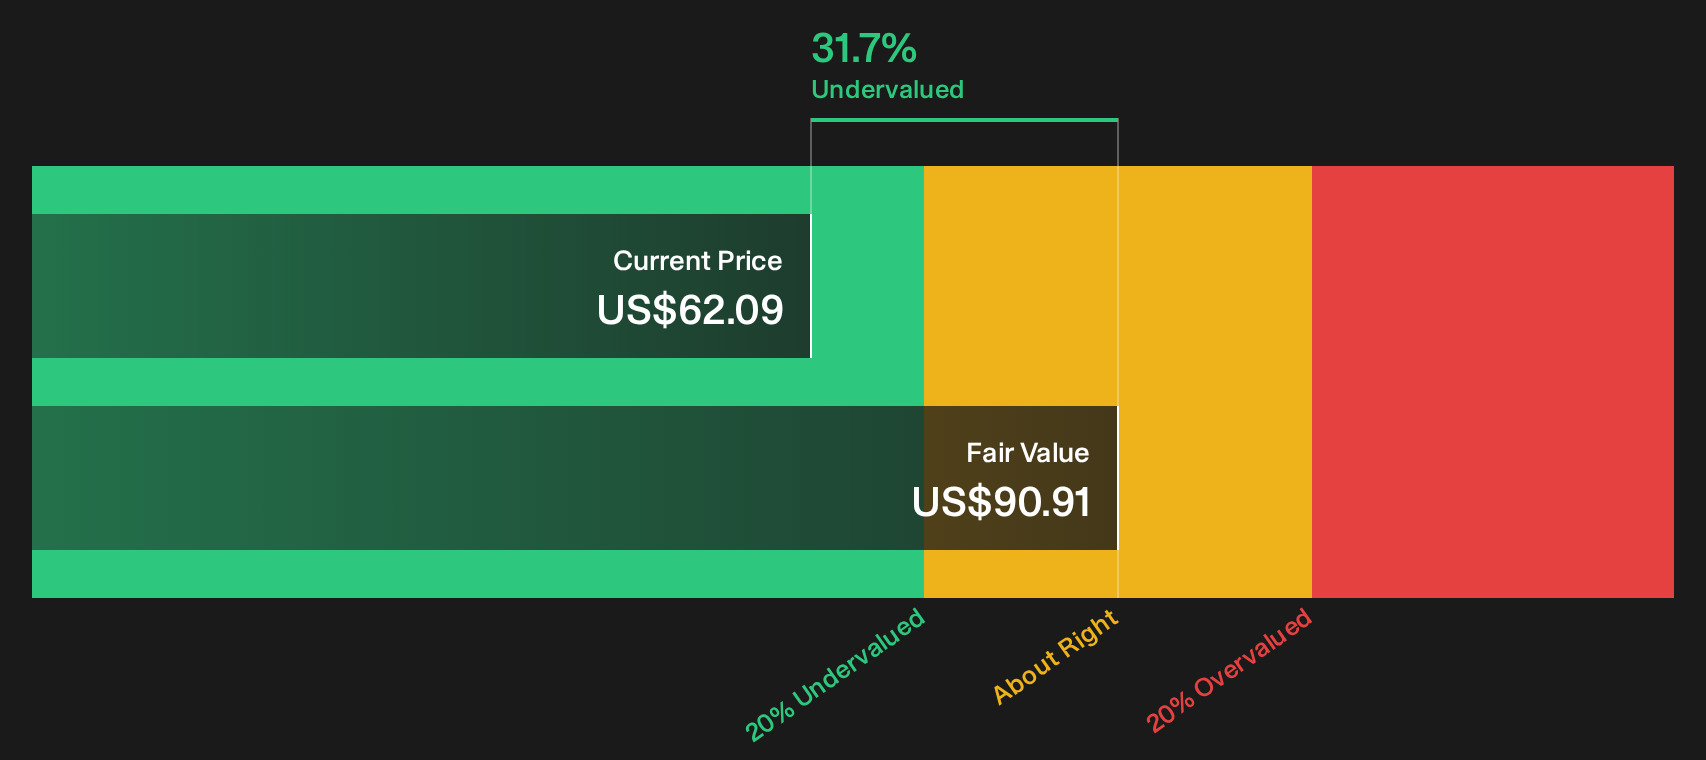
- The Discounted Cash Flow (DCF) intrinsic value estimate sits about 31.7% above the recent share price and most checks screen the stock as cheap, yet the broader picture is still mixed rather than a clear bargain, with a value score of 4 out of 6.
For investors, the debate is whether Hewlett Packard Enterprise stock still offers enough valuation support after such a strong multi year performance.
Scan Hewlett Packard Enterprise's AI fueled run against hand picked peers by reviewing 89 AI infrastructure stocks before you decide where the stronger momentum and valuation support may lie.
Is Hewlett Packard Enterprise Still Cheap on Cash Flow?
The Discounted Cash Flow (DCF) model values Hewlett Packard Enterprise by projecting future free cash generation and discounting it back to today. On this measure, the business is generating solid cash, with the latest twelve month free cash flow around $3.8b and the long term assumptions implying that cash flows grow rather than shrink over time.
Those projections feed into an estimated intrinsic value of about $90.91 per share, which compares with a recent share price that implies roughly a 31.7% gap. Recent guidance that points to at least $5b of free cash flow in fiscal 2027 helps explain why the cash flow model supports a higher value than the market is currently willing to pay. On this DCF view, Hewlett Packard Enterprise stock appears undervalued, with the market price lagging the cash flow based estimate of worth.
Our Discounted Cash Flow (DCF) analysis suggests Hewlett Packard Enterprise is undervalued by 31.7%. Track this in your watchlist or portfolio, or discover 31 more high quality undervalued stocks.
Does Hewlett Packard Enterprise Look Undervalued on Earnings?
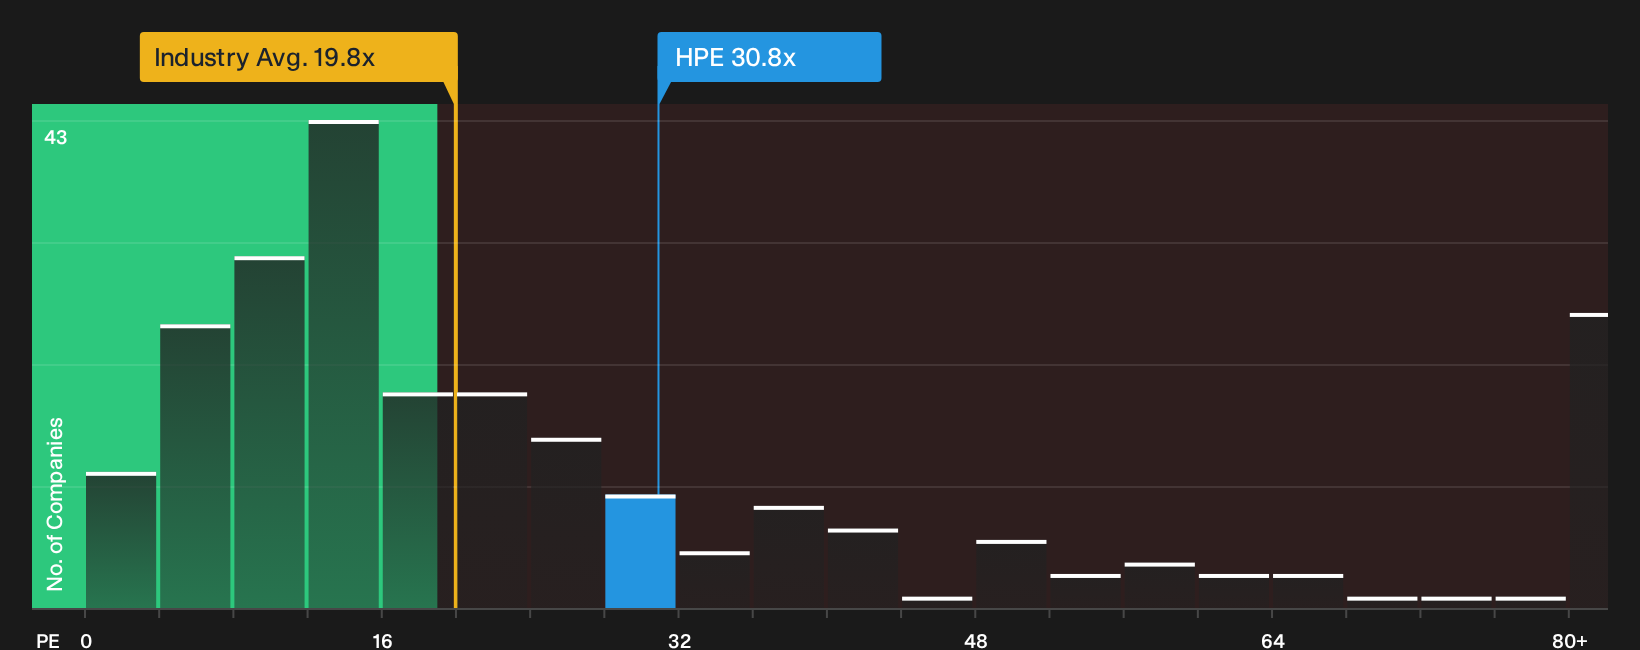
P/E works well for Hewlett Packard Enterprise because earnings are a key focus for how investors frame AI infrastructure plays. On this yardstick, the stock trades on about 30.8x earnings. That is above the broader Tech sector average of roughly 19.8x, yet it comes in below both the peer group average of about 58.4x and a more tailored fair P/E of around 37.3x that factors in the company’s size, profitability profile and risk.
Put simply, Hewlett Packard Enterprise changes hands at a premium to the typical tech listing but at a discount to what similar businesses and the fair ratio imply. The gap between the current 30.8x P/E and the 37.3x fair multiple indicates that investors are not paying fully for the earnings power the model assumes.
On the P/E multiple, Hewlett Packard Enterprise stock appears undervalued relative to its estimated fair earnings-based valuation.
See what the numbers say about this price — find out in our valuation breakdown.
The Hewlett Packard Enterprise Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Hewlett Packard Enterprise valuation puzzle leaves off. They explain which expectations about Hewlett Packard Enterprise's future growth, margins and earnings would need to hold for the stock to be worth materially more or materially less than today's price. These Narratives are available on Simply Wall St's Community page. Each one is framed as a thesis you can revisit over time, rather than a single frozen fair value line.
Community views on Hewlett Packard Enterprise now split sharply between an AI flywheel that keeps working and a cycle that already looks crowded.
Bull case: 5% undervalued
"HPE's transition to an as-a-service model continues to succeed, annualized recurring revenue (ARR) and software/services ARR both rose sharply, leading to a greater mix of recurring, higher-margin revenue..."
Read the full Bull Case to see why Hewlett Packard Enterprise could be undervalued
Bear case: 45% overvalued
"HPE's margins have been compressed due to inventory valuation issues and aggressive pricing competition in the server market, exacerbated by transitions in AI systems..."
Read the full Bear Case to see why Hewlett Packard Enterprise could be overvalued
Do you think there's more to the story for Hewlett Packard Enterprise? Head over to our Community to see what others are saying!
The Bottom Line
Hewlett Packard Enterprise screens as undervalued on both the Discounted Cash Flow (DCF) intrinsic value view and the earnings multiple check, even after a very strong five year stretch. That combination points to a market that is still cautious about how durable AI driven demand and the higher recurring revenue mix will be. The key issue from here is whether cash generation and margins from AI infrastructure and services hold up well enough for that DCF upside and P/E discount to stay intact, rather than reflect a value trap built on overly optimistic assumptions.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com