
Is XPeng (XPEV) Undervalued Following Its August Delivery Update?
XPeng (NYSE:XPEV) reported August 2026 vehicle deliveries of 39,107 units, a 4% year over year increase, giving investors fresh data on how the physical AI focused automaker is converting interest into actual sales.
The fresh delivery update comes amid a weak price backdrop for XPeng, with the share price down 10.3% over the past 30 days and 48.4% year to date, while the 1-year total shareholder return has declined 49.5%. This signals that recent momentum has been fading despite improving operational headlines.
Compare XPeng's delivery trend with other physical AI and EV players by scanning the curated list of 89 AI infrastructure stocks that could be setting up their next big move.
XPeng is reporting higher deliveries while the share price has dropped sharply this year, which raises a simple tension: Are investors reacting to the business, or has sentiment swung too far as the valuation resets?
Most Popular Narrative: 52.9% Undervalued
XPeng's most followed valuation storyline pegs fair value at $22.36, compared with the recent $10.54 close, which puts a spotlight on how aggressively future cash flows are being priced in.
XPeng's rapid in-house development and deployment of proprietary AI hardware (Turing AI SoC) and vision-based ADAS are expected to significantly advance its vehicle autonomy and smart cockpit solutions, aligning with surging consumer demand for intelligent, software-centric vehicles, setting the stage for higher-margin software revenue and enhanced gross/net margins.
Curious what justifies that kind of gap between fair value and the screen price. The narrative leans heavily on faster revenue expansion, rising margins and a richer earnings multiple built around those AI and software ambitions.
Result: Fair Value of $22.36 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, XPeng investors need to weigh persistent net losses and intense price competition in China, either of which could undermine the bullish margin story.
Find out about the key risks to this XPeng narrative.
Another View On XPeng's Valuation
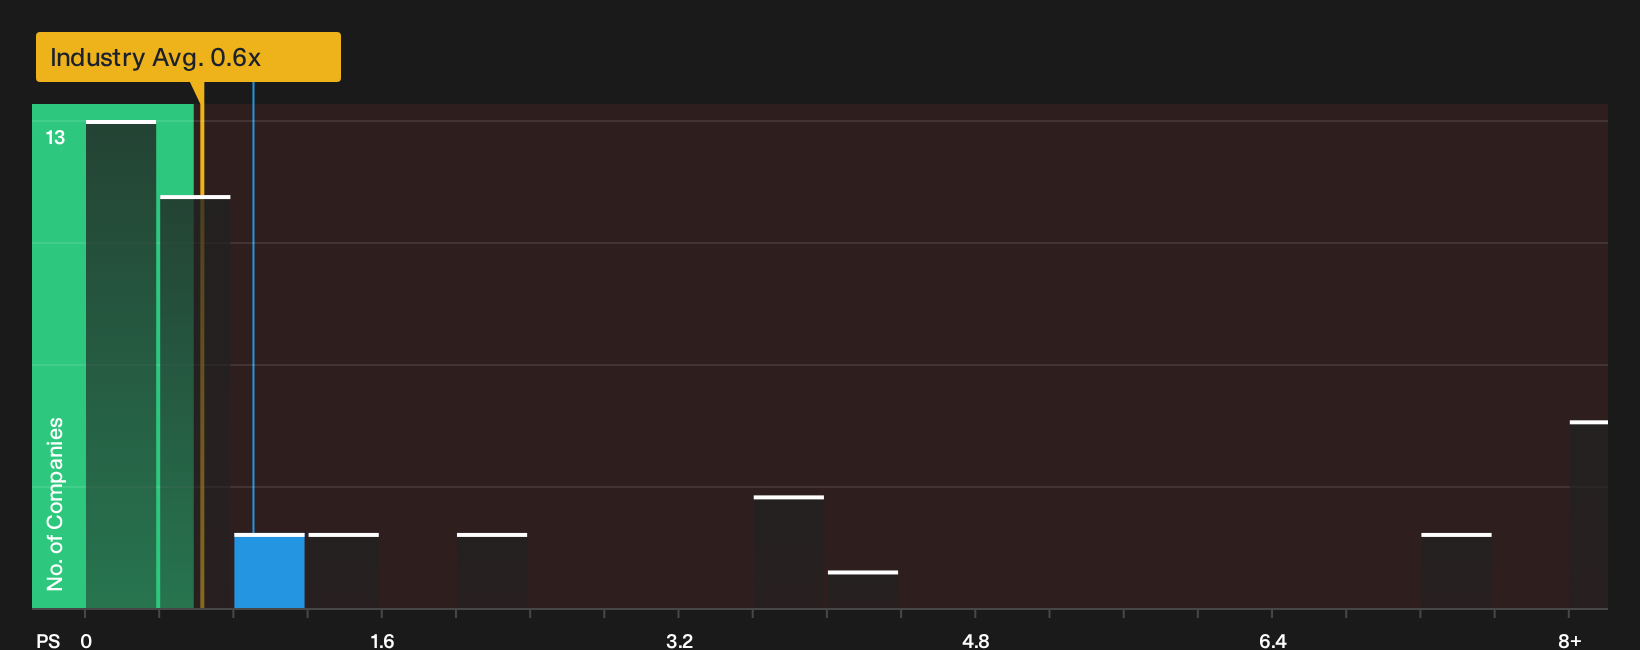
The story looks different when you switch from analyst fair value to what the market is paying for XPeng's revenue today. The stock trades on a P/S of 0.9x, above the US Auto industry at 0.6x, yet below a fair ratio of 1.3x and peer average of 1.8x. That mix of slight premium to the sector but discount to peers and fair ratio suggests investors are paying up a little for growth and AI potential, while still pricing in execution risk. The real question is whether you see that gap as a safety margin or a warning sign.
For a closer look at how the current P/S lines up with the wider market and where the fair ratio might pull it over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Optimistic or cautious about XPeng after all this, the quickest way to sharpen your own view is to work through the full set of data. To see what investors are excited about in the current setup, review the 3 key rewards
Looking for more XPeng investment ideas?
If XPeng has sharpened your thinking, do not stop here. Some of the most useful opportunities often sit just outside your current watchlist.
- Spot potential mispricings early and stress test your XPeng thesis against a broader opportunity set by scanning 31 high quality undervalued stocks
- Prioritize resilience and focus on capital preservation by weighing XPeng alongside a curated pool of 11 resilient stocks with low risk scores
- Hunt for under-the-radar potential and see how XPeng compares with a focused group of 16 high quality undiscovered gems
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com