
Star Bulk Carriers (SBLK) Stock Could Be Undervalued On Its Athens Listing
Star Bulk Carriers has delivered strong share price gains over the past few years, yet the valuation picture today is more nuanced than a simple "cheap" or "expensive" label. The stock screens as undervalued on market multiples, while a mixed overall value score suggests investors need to look closely at what is really priced in.
- Over the past 5 years, Star Bulk Carriers has returned about 141%, which puts extra weight on whether recent enthusiasm has already captured much of the easy upside.
- The recent oversubscribed €112.2 million equity raise and parallel listing on Euronext Athens can support balance sheet flexibility and fleet plans, but the added share count may pressure per share metrics if returns on that new capital disappoint.
- With a value score of 4 out of 6, the broader checks point to a mixed picture rather than a clear bargain or clear overvaluation.
The stock's next move may depend on whether Star Bulk Carriers' current market price fairly reflects these competing signals from recent performance and valuation checks.
Capitalize on the re-rating story around Star Bulk Carriers by comparing it against hand picked peers screened for 31 high quality undervalued stocks with similar valuation signals and recent share price strength.Does Star Bulk Carriers Look Undervalued on Earnings?
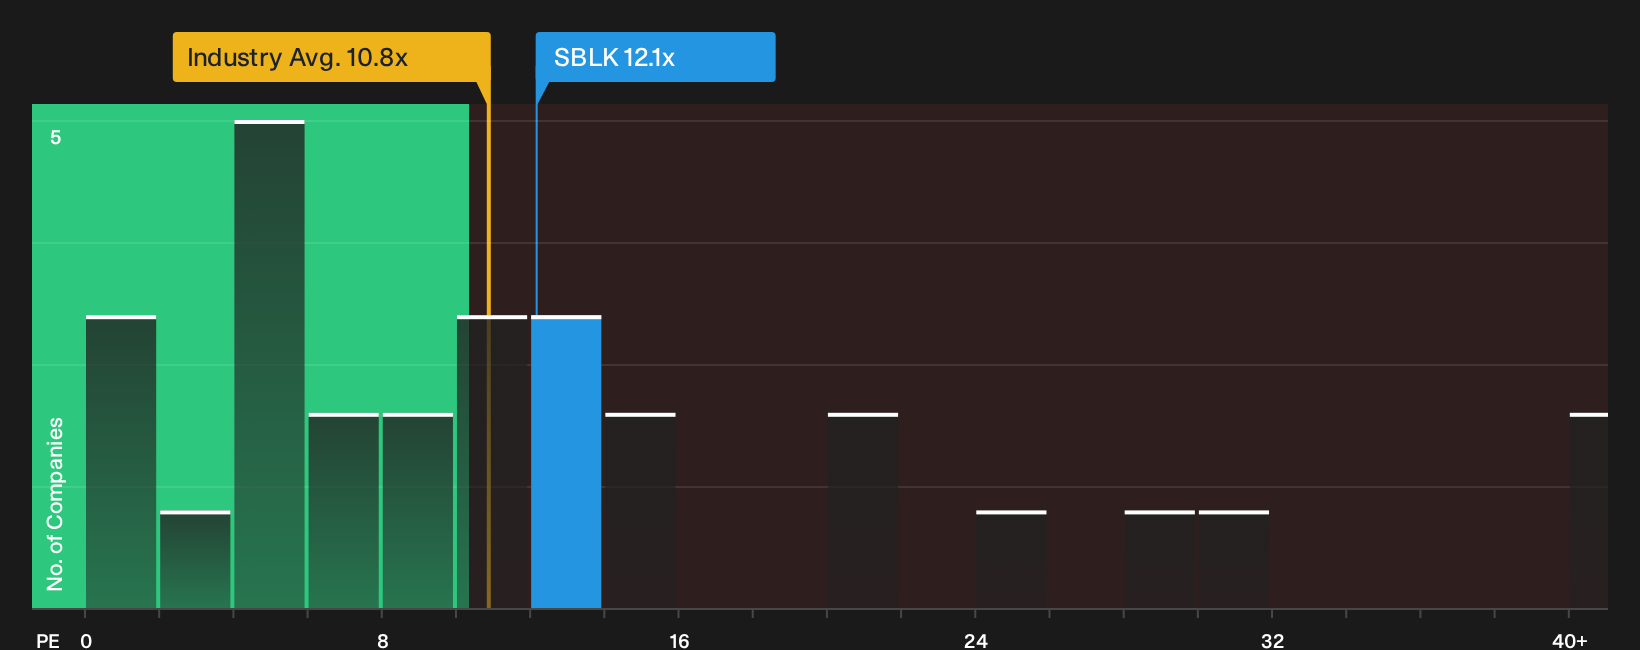
The P/E ratio suits Star Bulk Carriers because earnings are a key driver for how investors usually look at shipping stocks. On this metric, the company trades at about 12.1x earnings, which sits slightly below the peer average of 13.0x and modestly above the broader shipping sector on 10.8x.
Compared with the fair P/E of 16.4x implied by its own profile, Star Bulk Carriers changes hands at a sizeable discount. That gap suggests the market is not fully matching the valuation level indicated by the company’s earnings power and risk mix. Despite the recent oversubscribed equity raise and parallel Euronext Athens listing, which may give the stock more visibility, the current P/E still places it below what this framework points to as a more typical level.
On the P/E multiple alone, Star Bulk Carriers appears undervalued relative to both its tailored fair ratio and its closest peers.
See what the numbers say about this price — find out in our valuation breakdown.
The Star Bulk Carriers Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the valuation puzzle for Star Bulk Carriers leaves off by spelling out which combinations of future growth, profitability and earnings would need to play out for the stock to be worth materially more or materially less than today’s price. Instead of only giving a single output from a ratio or model, they set out the underlying future those numbers assume, so you can watch how reality lines up with that story over time on Star Bulk Carriers' Community page.
Community views on Star Bulk Carriers split sharply between a fleet-and-dividends upside story and a longer term demand and regulation overhang.
Bull case: roughly fairly valued
"Limited new vessel supply, caused by a historically low orderbook, strong shipyard constraints, and uncertainty around future green technologies, should maintain a tight tonnage market through 2027, allowing Star Bulk to benefit from stronger utilization and higher time charter revenues…"
Read the full Bull Case to see why Star Bulk Carriers could be undervalued
Bear case: 20% overvalued
"The accelerating global shift toward decarbonization and energy transition is set to steadily erode long-term demand for seaborne transportation of coal, iron ore, and other fossil fuel-related cargoes, which represent a significant portion of Star Bulk Carriers' revenues…"
Read the full Bear Case to see why Star Bulk Carriers could be overvalued
Do you think there's more to the story for Star Bulk Carriers? Head over to our Community to see what others are saying!
The Bottom Line
Star Bulk Carriers screens as undervalued on earnings multiples, yet the broader checks point to a more balanced verdict that hinges on execution. The crux is whether the fleet, capital raise and listing momentum translate into sustained earnings that persuade investors to close that P/E gap. If shipping demand and regulatory shifts align more closely with the bear narrative, the current discount could prove to be a value trap. The key question from here is whether the market eventually assigns Star Bulk Carriers a higher multiple, or continues to price in long term demand and decarbonization risks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com