
Has Talen Energy (TLN) Fallen Far Enough To Look Cheap?
Talen Energy has delivered a very large gain over the past three years, yet the share price has recently pulled back and the valuation checks now point to a mixed picture rather than a clear bargain or clear overpricing.
- Over the past three years, Talen Energy is up very sharply, which puts the current weakness into the context of a powerful earlier recovery.
- Future valuation can depend on how reliably the business converts its asset base into cash flow. Any setback in execution or higher required capital spending may weigh on what investors are willing to pay.
- The broader checks suggest a mixed profile, with Talen Energy screening as undervalued on several market multiples but earning a 4 out of 6 value score that does not clearly label it as either cheap or expensive.
The issue now is whether the recent pullback in Talen Energy leaves enough potential upside relative to current fundamentals to interest long term investors.
Pressure test Talen Energy's mixed valuation story against other potential ideas by scanning 31 high quality undervalued stocks that also pair cheaper market multiples with underlying business quality.
Is Talen Energy a Bargain on Sales?
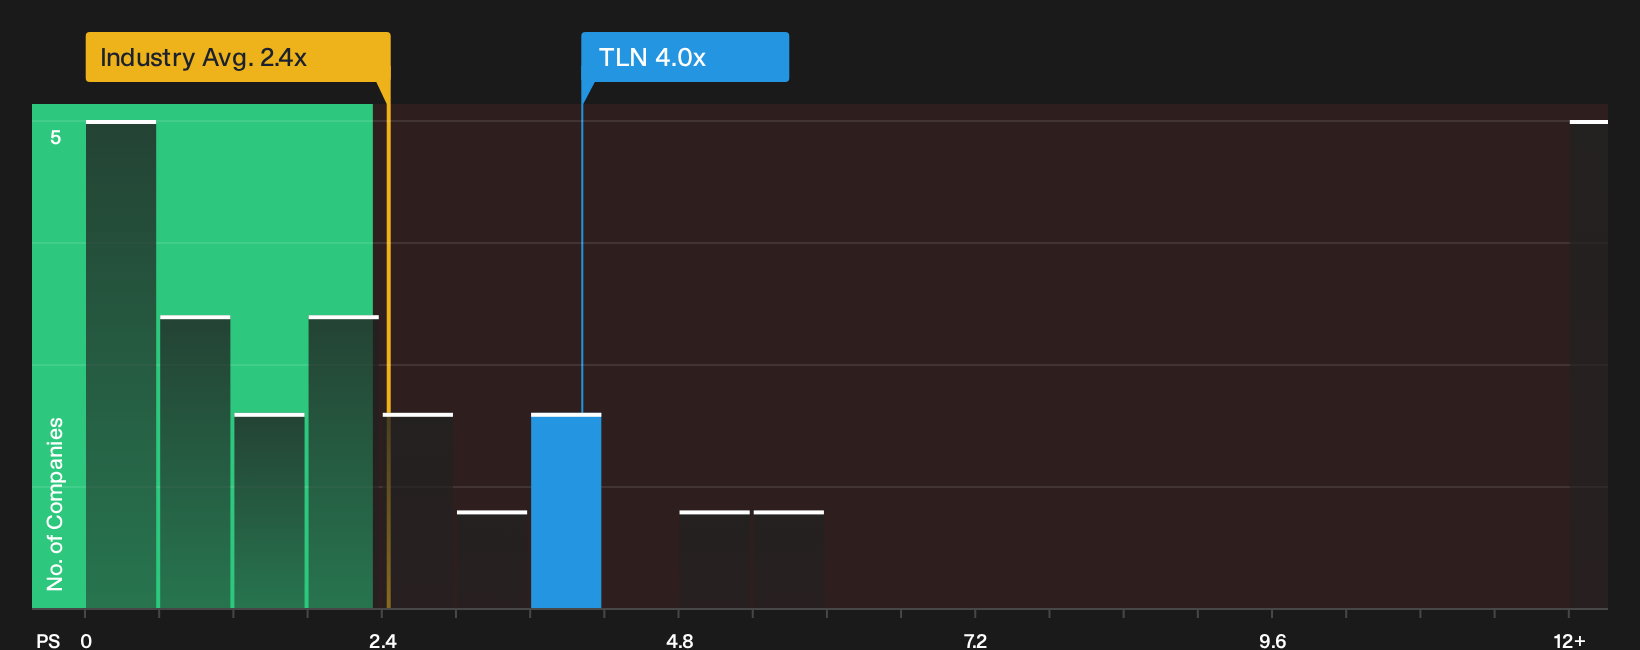
The P/S ratio suits Talen Energy because revenue is a core reference point for many power and infrastructure assets. On this metric, the stock trades on about 4.0x sales, which is well above the renewable energy industry average of roughly 2.5x and also ahead of the peer group average near 1.9x. On a simple comparison, that kind of premium often signals that investors are already paying up for the current business footprint.
The fair P/S ratio from the model sits higher, at about 4.5x. That is above both the sector and peer benchmarks and still comes out slightly above Talen Energy's present multiple. In other words, the stock looks inexpensive relative to what this more tailored yardstick suggests would be a neutral P/S level, even though it does not look cheap against the raw industry numbers.
On the preferred P/S framework, Talen Energy screens as undervalued despite carrying a clear premium to basic sector and peer averages.
See what the numbers say about this price — find out in our valuation breakdown.
The Talen Energy Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Talen Energy's valuation puzzle leaves off by spelling out the cash flow, earnings and margin paths that would need to hold for the stock to be worth materially more or materially less than the current price, and they live on Simply Wall St's Community page. Rather than relying on a single multiple or model result, each narrative lays out the assumptions behind its estimate of fair value so you can line those expectations up against the actual numbers as they are reported.
One of the top community narratives on Talen Energy: 32% undervalued
"Major expansion and long-term extension of carbon-free nuclear power supply to AWS provide Talen with stable, inflation-protected contracted revenue streams from a blue-chip hyperscaler customer..."
Read one of the top narratives on Talen Energy
Do you think there's more to the story for Talen Energy? Head over to our Community to see what others are saying!
The Bottom Line
Talen Energy screens as undervalued on its preferred market multiples, yet the broader checks are mixed enough that the current price does not look like a one way bet. The sharp move in the share price over recent years makes it harder to know whether that discount reflects genuine mispricing or a market that is already baking in execution and capital spending risks. The real divide between bulls and bears now is whether Talen Energy can turn its asset base into steady, cash rich operations without needing materially heavier investment than investors currently expect.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com