
IBEX (IBEX) Stock Rallies As Revenue Strength Meets Profit Friction
IBEX just jumped 6.8% to about $39.80, which indicates that traders reacted positively to the headline. The company reported record full year revenue of $644.1m and adjusted earnings per share of $3.52, while holding a net cash position of roughly $30.9m.
In the short term, this reflects a relief pop after a stronger than usual quarter. For anyone with a longer time horizon measured in years rather than days, the combination of rising revenue and improving profitability is an important part of the ongoing IBEX equity story.
Is IBEX a genuine compounder trading at a discount, or is the low P/E simply compensation for slower revenue growth and mixed peer comparisons? Compare the share price to the full DCF and multiples view in our valuation analysis for IBEX.Q4 2026 Earnings Summary
- Revenue, Q4 2026 vs. Q4 2025: US$164.3m vs. US$147.1m (up about 12%)
- Net Income, Q4 2026 vs. Q4 2025: US$8.7m vs. US$9.6m (down about 9%)
- Basic EPS, Q4 2026 vs. Q4 2025: US$0.65 vs. US$0.72 (down about 9%)
- Trailing 12-Month Net Profit Margin, FY 2026 vs. FY 2025: 7.2% vs. 6.6% (margin improved)
Prefer clean visuals over slogging through another wall of text and raw figures on IBEX? View a complete picture of the business in charts, including how analysts frame its outlook in our company report for IBEX.
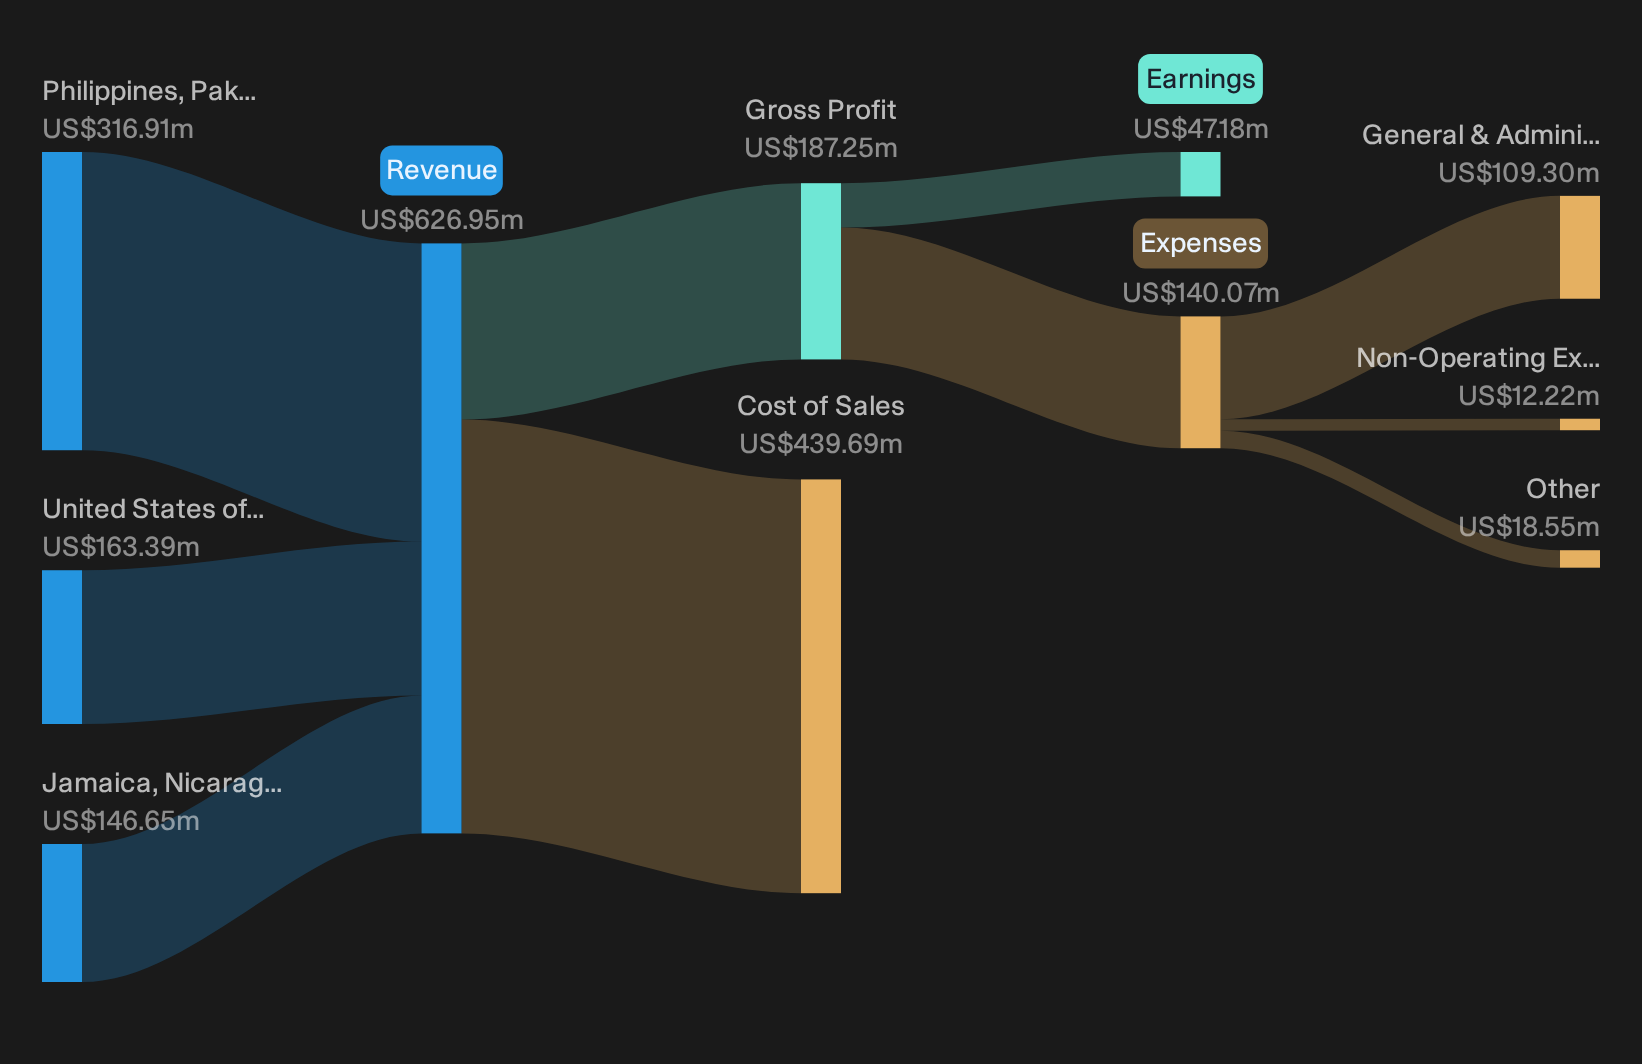
IBEX bullish story meets improving fundamentals
For IBEX bulls who see an AI enabled CX platform riding a healthy outsourcing cycle, the latest print broadly lines up. Revenue rose to US$164.3m in Q4 and US$644.1m for FY 2026, while adjusted EPS reached US$3.52 and margins ticked higher on a full year basis. Record operating cash flow of US$59m and a US$30.9m net cash position support the idea of a resilient balance sheet. The 6.8% post earnings move suggests investors treated these numbers as confirmation rather than a surprise pivot.
Bearish concerns focus on growth mix and execution
Risks around IBEX are not erased. Q4 net income and EPS both slipped about 9% year on year, which shows the growth and margin story is not a straight line. Management linked softer Q4 profitability to onboarding, delivery shifts and higher utilities. This implies execution and cost control remain key watchpoints. Client concentration is easing but top 25 accounts still account for 75% of revenue. Bears worried about contract or AI rollout missteps still have real pressure points to monitor in the next few quarters.
Reveal where the surface looks calm, but the street models start to disagree on IBEX's next few years. Access the full earnings per share, revenue and margin analyst estimates for IBEX.Stay Ahead With Simply Wall St
If IBEX's record full year revenue and post earnings share price reaction have your attention, register for free with Simply Wall St and add it to a Watchlist to track price against fair value and watch for a cleaner entry point. Once you own IBEX or any other holding, use the Portfolio Command Center to quiet the noise and focus only on material events that affect your investment thesis. Over time, compare your thinking with thousands of other investors through the Community and see how sentiment and debates evolve around key catalysts. Spot potential upside and emerging risks early so you can move faster and stay a step ahead of the market.
Seeking Alternatives Beyond IBEX?
Fresh ideas can move fast when momentum builds. Do not get caught chasing breakouts after the crowd. Scan under the radar picks while it matters and get in early.
- Hunt for resilient compounding stories with strong cash generation and sturdy balance sheets using the curated 31 high quality undervalued stocks.
- Zero in on cash generative AI opportunities that are not just burning runway by reviewing the curated group of 74 profitable AI stocks that aren't just burning cash.
- Target steadier income ideas with staying power by checking companies in the curated 6 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com