
Laureate Education (LAUR) Following Latin America Growth Narrative Is It A Buying Opportunity
Laureate Education (LAUR) most recently closed at $36.14, drawing fresh attention from investors reviewing education stocks after a period of mixed short term returns and a stronger performance over the past year.
The recent 1-day share price gain of 1.02% comes after softer 7-day and 30-day share price returns. Laureate Education’s 1-year total shareholder return of 22.97% and very large 5-year total shareholder return of about 3.4x suggest longer term momentum has been much stronger than the short term picture implies.
Compare Laureate Education’s momentum with other education stocks by scanning a curated list of solid balance sheet and fundamentals (23 results) that also show resilient recent performance and multi year returns.
Short term softness and a fresh uptick put Laureate Education in an interesting spot. Is this latest move about fundamentals quietly doing the work, or sentiment finally catching up with what has already been built?
Most Popular Narrative: 10.2% Undervalued
Against the latest Laureate Education close at $36.14, the most followed narrative sees fair value at $40.25, anchored on specific earnings and margin forecasts.
Ongoing expansion into high-growth Latin American markets (Mexico, Peru) through new campus openings and targeted capacity investments leverages rising demand for private tertiary education, which is likely to drive sustained enrollment and revenue growth over the next several years.
Read the complete narrative. Read the complete narrative.
Curious what kind of enrollment uplift, pricing power and profit margin profile needs to line up to support that valuation gap and discount rate assumption.
The narrative behind Laureate Education rests on a detailed set of projections for revenue growth, profitability and capital allocation, not just a simple headline multiple. It combines expectations for Latin American enrollment trends, online program uptake and margin discipline into a single fair value estimate that currently sits above the market price. Result: Fair Value of $40.25 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, the Laureate Education story can shift quickly if heavy campus spending in Mexico and Peru meets weaker enrollment, or if currency swings undercut those US$1.83b in annual revenues.
Find out about the key risks to this Laureate Education narrative.
Another View: What Laureate Education’s P/E Is Telling You
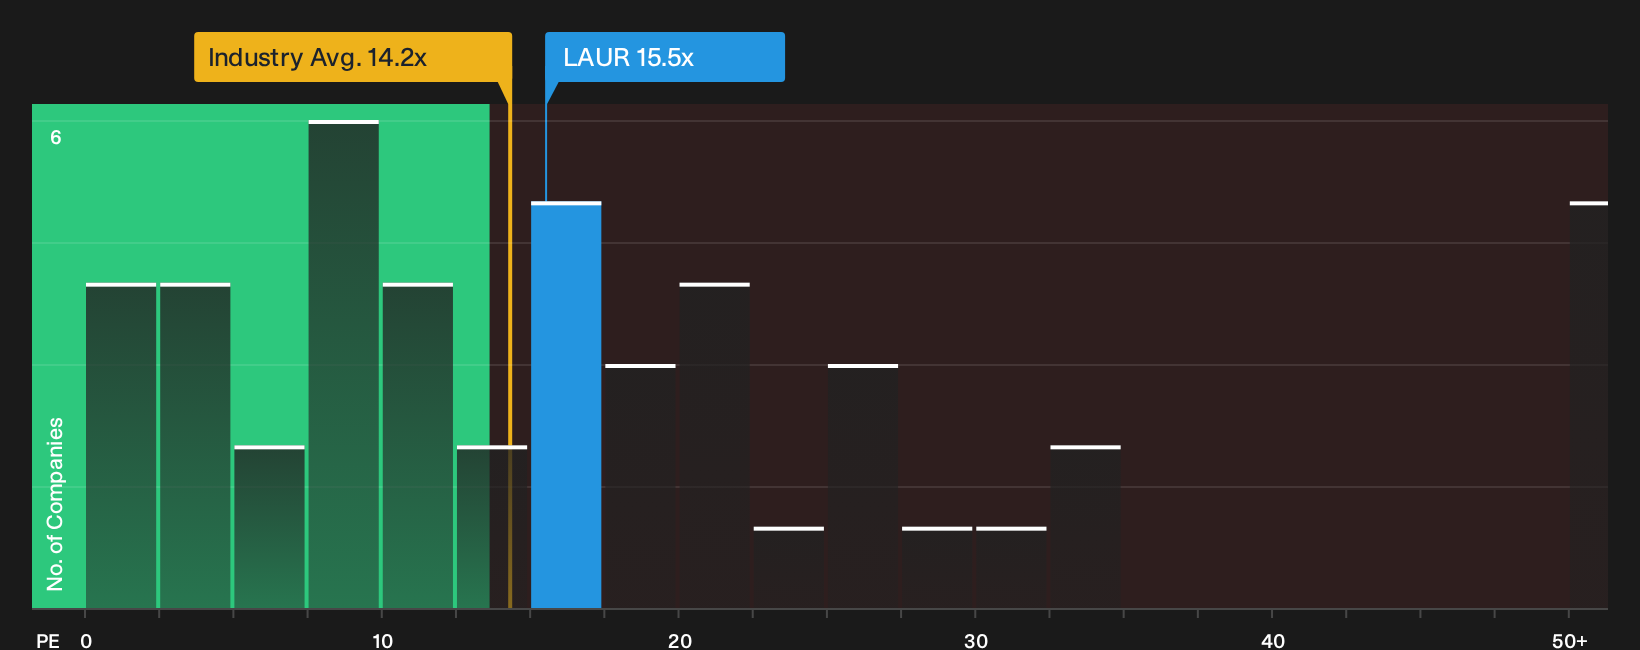
On a simple earnings multiple, Laureate Education looks less clear cut. The stock trades on a P/E of 15.5x, which is a bit higher than the US Consumer Services sector on 14.2x and also above its peer group at 15.1x, yet below a fair ratio estimate of 18.5x that the market could move toward in time. That mix of slight premium and apparent headroom raises a basic question for investors: Is this a reasonable price for quality today, or are expectations quietly getting ahead of themselves?
See what the numbers say about this price, find out in our valuation breakdown. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment in this piece tilts cautiously optimistic, yet the real test is how you interpret the underlying facts and ratios for yourself. Move quickly, review the positives investors are already focused on, and weigh those against your own risk tolerance with 3 key rewards
Looking for more Laureate Education sized investment ideas?
If Laureate Education has your attention, do not stop here. Broaden your watchlist now so you are not chasing opportunities after everyone else moves.
- Target resilient performers by scanning a 11 resilient stocks with low risk scores that can help you focus on businesses with lower risk scores before volatility hits.
- Hunt for value by reviewing a 31 high quality undervalued stocks that groups companies combining stronger fundamentals with prices that may sit below their estimated worth.
- Prioritize financial strength by checking a list of solid balance sheet and fundamentals (23 results) that highlights firms with healthier balance sheets and more robust financial footing.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com