
FactSet Research Systems (FDS) Looks 2% Overvalued On Its Credit Agreement Update
FactSet Research Systems (FDS) recently revised its debt structure through an amendment to its existing credit agreement, extending key maturities and expanding revolving commitments to support future funding flexibility.
Recent trading has been rough for FactSet Research Systems, with the share price down 14% over the past week and 6.6% over the last month, even though the 90-day share price return is still up 7.7% and the 1-year total shareholder return is lower by 26.9%. This points to fading momentum as investors reassess risk and growth expectations around moves like the amended credit agreement.
Compare how FactSet Research Systems stacks up against other financial data and analytics players under pressure by scanning our curated list of list of solid balance sheet and fundamentals (23 results)
FactSet Research Systems now has a lower share price and a more flexible credit line after the amendment. Does that create an early entry opportunity today, or does it argue for patience while the valuation case is tested next?
Most Popular Narrative: 1.8% Overvalued
Analysts following the most popular FactSet Research Systems narrative see fair value at $255.06, slightly below the last close of $259.71. This frames the amended credit facility against an only modest valuation gap.
FactSet is integrating new acquisitions like Irwin and LiquidityBook, adding immediate cross-sell opportunities and expanding services across buy-side and banking workflows, which will support revenue growth. The launch of new GenAI products, including Pitch Creator and conversational API, is expected to provide additional services that drive adoption and increase ASV growth, positively impacting future revenue.
It is worth examining what kind of revenue run-rate and margin profile that narrative implies. The fair value depends on a specific growth cadence and a lower future earnings multiple, each linked to AI usage trends and subscription depth.
Result: Fair Value of $255.06 (OVERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, the narrative can unravel if higher technology and cloud expenses squeeze margins further, or if asset managers keep tightening budgets and slow subscription decisions.
Find out about the key risks to this FactSet Research Systems narrative.
Another View: FactSet Research Systems Through The P/E Lens
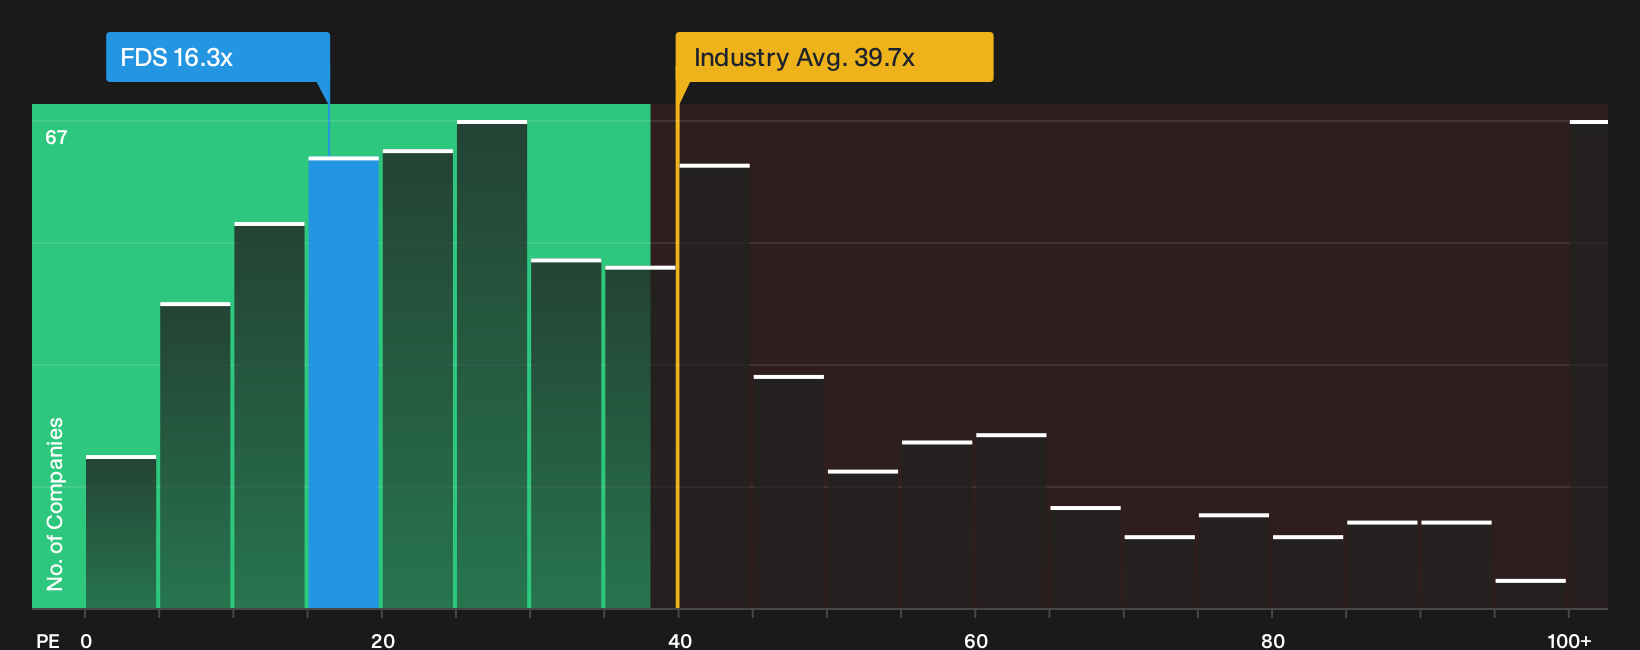
There is a different story when you look at FactSet Research Systems through its P/E ratio instead of the SWS DCF model that flags the stock as good value. The current P/E sits at 16.3x, above a fair ratio of 15.5x, which hints at some valuation stretch.
That same 16.3x multiple is lower than the peer average of 20.3x and well below the wider US Capital Markets group at 39.7x. So the stock screens cheaper than many rivals, yet still a touch rich versus its own fair ratio. The question for you is which anchor matters more when sizing up risk and opportunity.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment in this FactSet Research Systems story cuts both ways, so move quickly, review the full data, and weigh the 4 key rewards and 1 important warning sign.
Looking For More Investment Ideas Beyond FactSet Research Systems?
If this FactSet Research Systems story has you thinking about valuation, risk, and upside, broaden your watchlist with a few focused stock ideas built from data driven screeners.
- Target steadier opportunities by scanning companies that score well on resilience and financial risk using our 11 resilient stocks with low risk scores.
- Hunt for potential value by checking businesses that pair quality fundamentals with attractive pricing through the curated 31 high quality undervalued stocks.
- Spot potential income plays by reviewing companies offering higher yields and strong payout support inside the focused 6 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com