
Mettler Toledo (MTD) Stock Looks Fair On Cash Flow Yet Rich On Earnings
Mettler-Toledo International stock has delivered a loss of 16.3% over the past five years, while current checks suggest the shares now sit close to an intrinsic value estimate from a Discounted Cash Flow (DCF) model, yet still screen expensive on traditional market multiples. That mix leaves Mettler-Toledo trading in a zone where the intrinsic value work points to roughly fair pricing, but the earnings and revenue ratios point to a premium.
- The 5 year return is down 16.3%, which indicates long term holders have not been rewarded enough to clearly justify a rich valuation.
- Future cash flow growth from precision instruments and lab equipment can support the current price. However, any pressure on pricing power or profit margins may weigh heavily on that case.
- The broader valuation checks give a mixed picture rather than a clear bargain or clear overvaluation, with a value score of 3 out of 6.
The issue now is whether Mettler-Toledo offers enough fundamental support at this level to offset the premium signaled by its market multiples.
Broaden your watchlist beyond Mettler-Toledo International by comparing its premium multiples and mixed value score against 31 high quality undervalued stocks, which currently screen as closer fits on fundamentals.
Does Mettler-Toledo International Look Fairly Valued on Cash Flow?
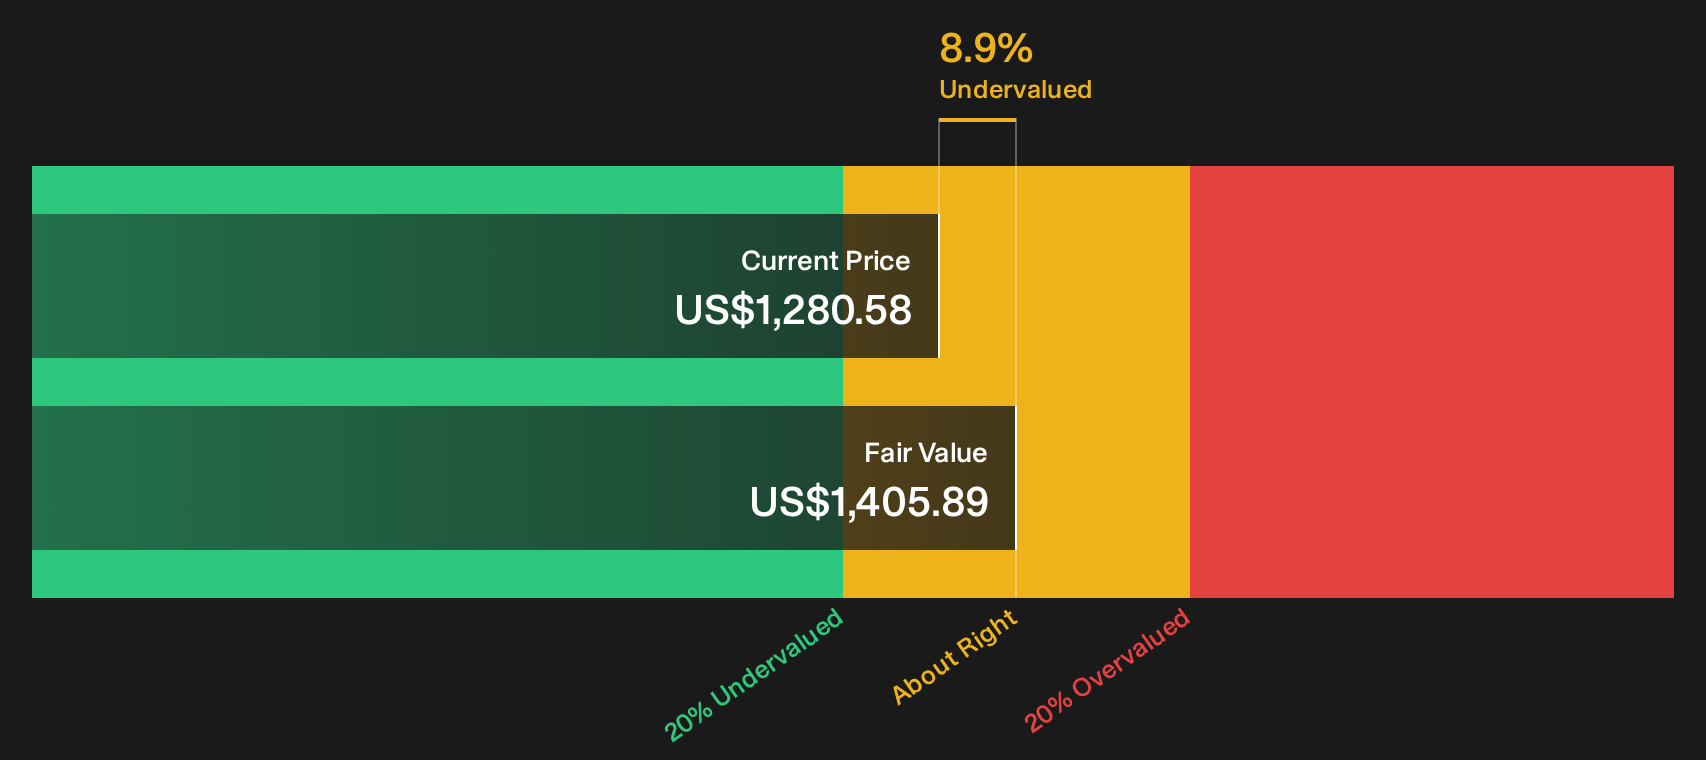
The Discounted Cash Flow model estimates what Mettler-Toledo International is worth based on the cash it can return to shareholders over time. The company produced roughly $866.2 million in free cash flow over the latest twelve months, with the model assuming that these cash flows keep growing rather than shrinking. Feeding those projections into a 2 Stage Free Cash Flow to Equity approach gives an estimated intrinsic value of about $1,408 per share.
That intrinsic value sits around 8.1% above the current share price, which points to the stock trading at a modest discount to the DCF outcome rather than at a glaring mispricing. For someone weighing Mettler-Toledo against cheaper looking peers on simple P/E or P/S ratios, the key takeaway is that its cash generation profile still broadly supports today’s price even if the headline multiples look rich.
On the DCF numbers alone, Mettler-Toledo stock appears roughly fairly valued with only a small tilt toward being undervalued.
Mettler-Toledo International is fairly valued according to our Discounted Cash Flow (DCF), but this can change at a moment's notice. Track the value in your watchlist or portfolio and be alerted on when to act.
Has Mettler-Toledo International Run Too Far on Earnings?
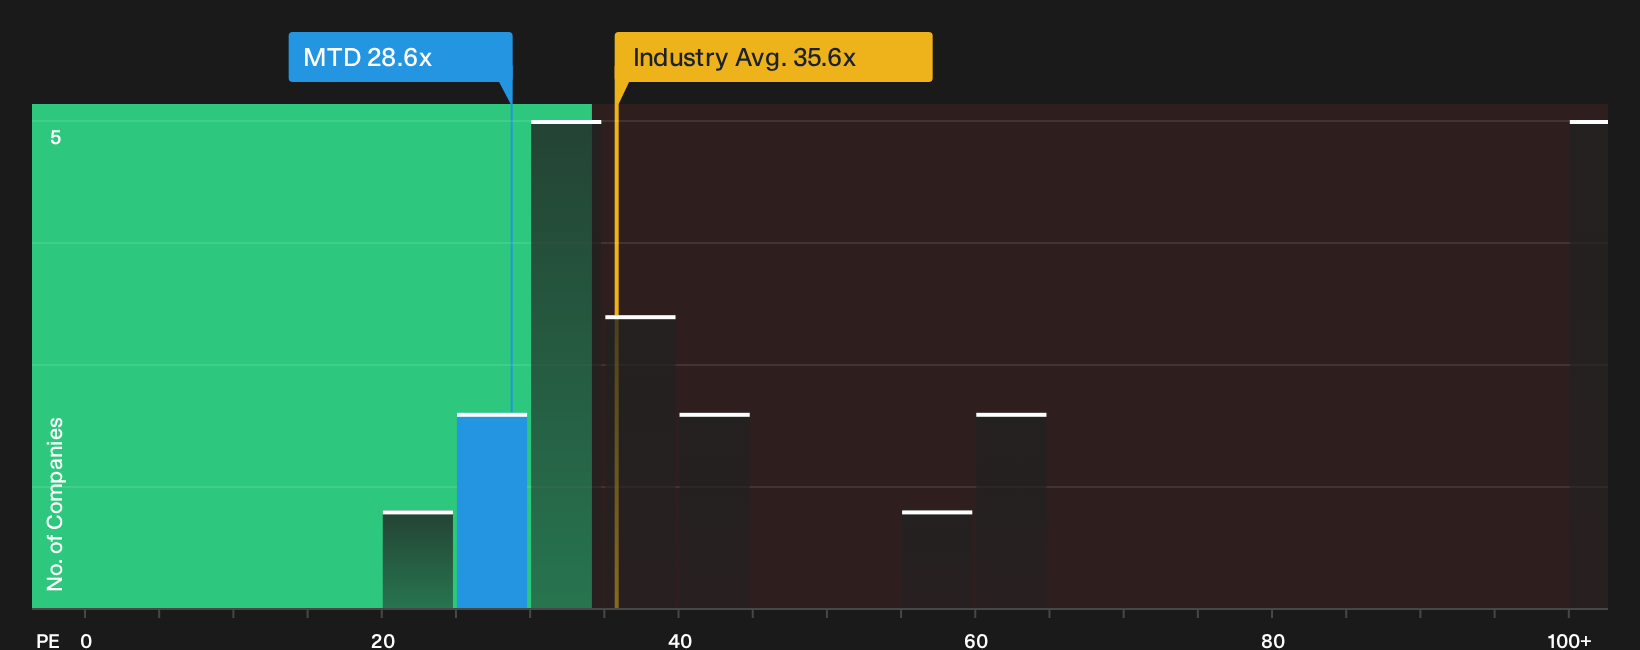
P/E is a useful lens for Mettler-Toledo International because earnings power is a central part of the story investors are paying for. On this metric, the stock trades on about 28.6x earnings, which is below the Life Sciences industry average of roughly 35.6x and also below the peer average of about 35.3x.
The tailored fair P/E ratio from the model is 21.9x, which reflects what might be reasonable given Mettler-Toledo International’s sector, profitability profile, size and risk. The current 28.6x is meaningfully higher than that fair level. Even with a discount to the broader group, the shares still price in a richer earnings tag than the model suggests is justified.
On earnings, Mettler-Toledo International stock screens as overvalued because its current P/E sits well above the model’s fair multiple.
See what the numbers say about this price — find out in our valuation breakdown.
The Mettler-Toledo International Narrative: What Would Justify Today's Price?
Mettler-Toledo International’s valuation story now branches into a set of “what if” paths that live inside Simply Wall St’s Community page as Narratives. These outline the earnings, margin and growth assumptions that would need to hold for the stock to be worth meaningfully more or less than it is today. Each one links a specific fair value to a particular mix of potential catalysts and risks so you can track which version of the story is actually unfolding over time.
You can add your own narrative on Mettler-Toledo International’s valuation case, present the numbers driving your view on where its growth, margins and execution go from here, and then compare that thesis as fresh results arrive.
Do you think there's more to the story for Mettler-Toledo International? Head over to our Community to see what others are saying!
The Bottom Line
Mettler-Toledo International looks roughly fairly valued on Discounted Cash Flow, yet screens overvalued on earnings multiples, so the verdict is not cleanly cheap or expensive. The gap between those views comes from cash generation supporting today’s level, while the current P/E still leans on confident expectations for the business. For potential investors, the real swing factor is whether pricing power and margins in its precision instruments franchise prove strong enough to keep justifying that richer earnings tag over time.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com