
Magnolia Oil And Gas (MGY) Stock Looks Fairly Valued Following Its 79% Five Year Run
Magnolia Oil & Gas has delivered a strong 79.2% return over the past 5 years, yet the valuation checks send a mixed message that keeps the stock from looking like a straightforward bargain or a clear excess.
- A 79.2% gain over 5 years suggests Magnolia Oil & Gas has already rewarded patient holders, so fresh capital now needs a clear view on what is priced in.
- Future value can hinge on how consistently Magnolia Oil & Gas converts its production into free cash flow. Sensitivity to commodity prices remains a key risk for earnings and asset values.
- The broader checks point to a mixed picture rather than an obvious bargain. The 3 out of 6 value score sits alongside multiples that screen as undervalued.
For investors, the debate is whether Magnolia Oil & Gas still offers enough valuation upside after that 5 year run to justify new money at around US$27.70 a share.
Scan beyond Magnolia Oil & Gas and compare its mixed value score with other hand picked opportunities in the 33 high quality undervalued stocks list.
Is Magnolia Oil & Gas a Bargain on Earnings?
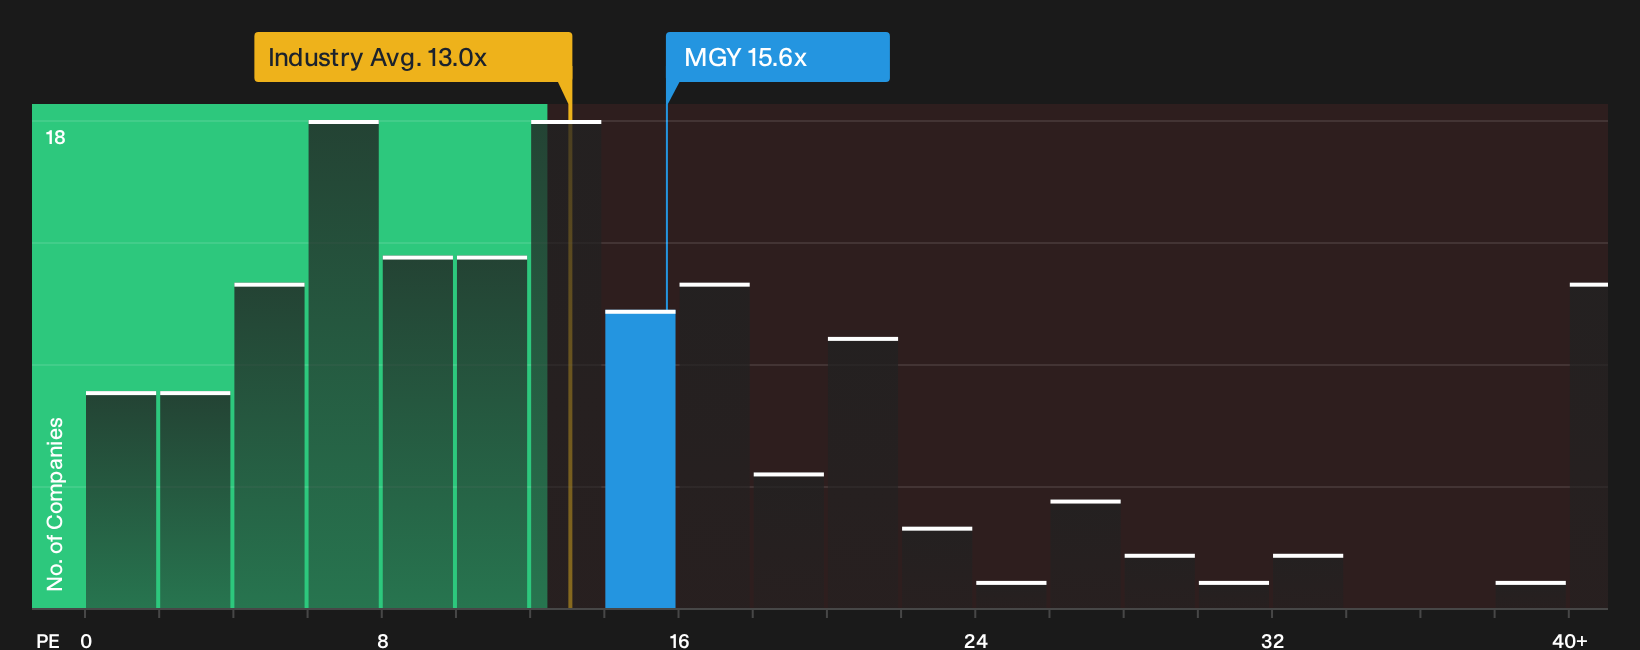
The P/E ratio is a useful measure for Magnolia Oil & Gas because earnings are a key yardstick for a producer that is already free cash flow positive. On this metric, the stock trades on about 15.6x earnings. That is above the Oil and Gas sector average of roughly 13.0x and above the peer sample on about 11.6x, so the headline comparison points to a premium valuation versus many listed rivals.
A more tailored yardstick that weighs Magnolia Oil & Gas against factors such as profitability, size and risk suggests a fair P/E closer to 20.5x. The current 15.6x level is well below that reference point. For investors who focus on earnings multiples, that gap indicates the market is not fully crediting the business on this framework even after the share price move.
Using the P/E lens, Magnolia Oil & Gas appears undervalued relative to the multiple implied by its own fundamentals.
See what the numbers say about this price — find out in our valuation breakdown.
The Magnolia Oil & Gas Narrative: What Would Justify Today's Price?
Narratives for Magnolia Oil & Gas give you a clear bridge from the valuation puzzle to the underlying assumptions, by spelling out what would need to happen to Magnolia Oil & Gas' growth, profitability and earnings for the shares to be worth materially more or materially less than today. Rather than relying on a single multiple or model result, each scenario lays out the key inputs behind its fair value so you can later compare them with actual reported numbers as they come through. These Narratives sit on Simply Wall St's Community page and are intended as a structured way to think through what the current share price already reflects.
Magnolia Oil & Gas splits opinion sharply, with one camp focused on unhedged cash generation and deal upside and the other leaning into energy transition and execution risk.
Bull case: 15% undervalued
"Ongoing bolt-on acquisitions and successful appraisal programs are expanding Magnolia's core Giddings acreage at low cost, increasing the duration and scale of its high-return inventory..."
Read the full Bull Case to see why Magnolia Oil & Gas could be undervalued
Bear case: 7% overvalued
"With the global energy transition accelerating and increasing adoption of electric vehicles and advanced battery technologies, oil demand growth is at significant risk of structural decline over the coming decade..."
Read the full Bear Case to see why Magnolia Oil & Gas could be overvalued
Do you think there's more to the story for Magnolia Oil & Gas? Head over to our Community to see what others are saying!
The Bottom Line
Magnolia Oil & Gas screens as undervalued on earnings-based multiples, yet the broader checks only point to a mixed overall picture rather than a clean green light. The tension is whether that discount signals mispricing or simply reflects exposure to commodity prices and execution risk that the market is reluctant to overlook. The real swing factor from here is how consistently Magnolia Oil & Gas can turn its asset base into durable free cash flow without needing a richer multiple to do the heavy lifting.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com