
Will Grid Compliance Filings Change Portland General Electric Stock Narrative
- Portland General Electric has recently filed multiple documents with the Federal Energy Regulatory Commission, covering hydroelectric incident reporting, River Mill powerhouse roof remediation, cost reimbursement for PacifiCorp line upgrades, and tariff procedures linked to its planned Extended Day-Ahead Market participation.
- These filings highlight Portland General Electric’s operational focus on grid reliability, wildfire and infrastructure risk management, and cost recovery structures that directly affect future capital spending and project execution.
- The article next examines how Portland General Electric’s emergency wildfire response and roof remediation plans relate to its broader investment narrative.
Portland General Electric Investment Narrative Recap
Owning Portland General Electric means believing that regulated Oregon power demand and grid investment can support steady earnings over time despite rising costs. The current focus sits on clean energy buildout, wildfire readiness, and execution of large capital projects. This latest cluster of FERC filings looks more operational than transformational. The River Mill roof remediation, wildfire driven operating adjustments, and PacifiCorp reimbursement deal all feed into routine reliability work. The key near term swing factor still looks like delivering grid upgrades and market participation on schedule, while wildfires and cost control remain the biggest operational stress points.
The final incident report on the August ramp rate deviation at Oak Grove Powerhouse ties directly into Portland General Electric’s wildfire and grid resilience story. Operations reduced generation ahead of a potential de energization, then took the plant offline as the Narrows Fire approached, triggering a short term ramp rate breach. Biologists reported no stranded fish, and regulators received timely notice. For investors watching catalysts, this update matters less for financial impact and more for how emergency procedures, environmental obligations, and wildfire safety intersect with future capital and regulatory decisions.
That said, there is a quieter issue in the background that could matter far more for long term holders...
Read the full Portland General Electric narrative to see the case behind these numbers.
Portland General Electric’s analyst narrative points to revenues of $4.3b and earnings of $515.2m by 2029, based on a 6.9% yearly revenue growth assumption and an earnings increase of about $264m from $251.0m today.
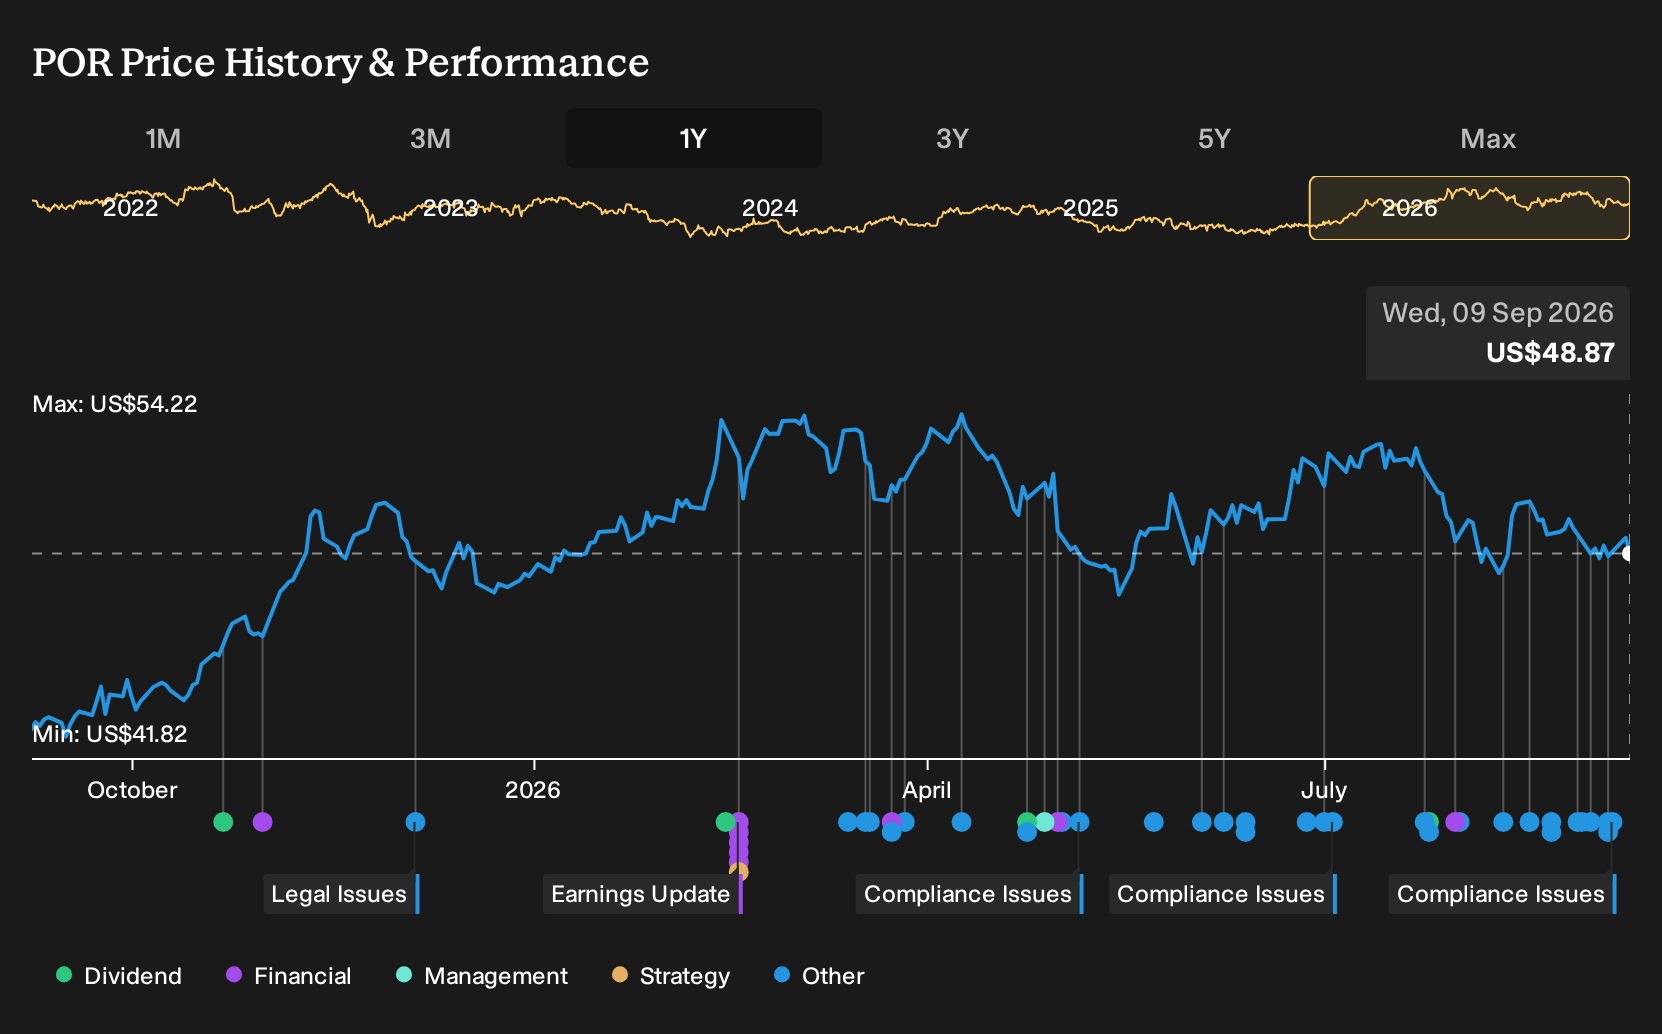
Portland General Electric's forecasts show a fair value of $52.55 versus a $48.87 share price, representing an 8% upside to its current price that could narrow quickly.
Exploring Other Perspectives
Four fair value estimates from the Simply Wall St Community span roughly US$39 to US$54 per share, with one retail view implying Portland General Electric is priced closer to the bottom of that range. Set those opinions against wildfire, regulatory, and grid upgrade risks, then weigh how market entry into EDAM could reshape future earnings quality.
To see how your view lines up with the crowd, check out the 3 other fair value estimates for Portland General Electric from the Simply Wall St Community.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis and research.
- A great starting point for your Portland General Electric research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Portland General Electric. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Portland General Electric's overall financial health at a glance.
Looking For More Investment Ideas Beyond Portland General Electric?
If Portland General Electric has you thinking about grid reliability, wildfire risk and long term capital plans, it can be useful to line that story up against other opportunities that share similar or contrasting traits. A focused stock screener helps you filter quickly by quality, balance sheet strength, income profile or valuation, so you can build a watchlist that actually reflects your priorities instead of a random collection of tickers.
- For investors who want potential mispricing backed by decent fundamentals, scan a curated set of 31 high quality undervalued stocks and see which businesses might offer more attractive entry points than Portland General Electric.
- If capital preservation and stability sit at the top of your checklist, narrow the field to 10 resilient stocks with low risk scores that score well on resilience and downside protection.
- Those looking for sturdier finances to support future projects can review a targeted list of solid balance sheet and fundamentals (24 results) and compare how these companies manage debt and liquidity against Portland General Electric.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com