
Do New 64 Bit MPUs Change The Bull Case For Renesas (TSE:6723)?
- Renesas Electronics recently expanded its RZ/G Series with RZ/G3L and RZ/G3SE 64 bit MPUs for HMI and IoT edge devices, joined the Autoware Foundation’s top tier to bring open source autonomous driving AI to R Car platforms, and opened a Physical AI & Robotics Lab in Beijing.
- The combination of low power MPUs with rich ecosystem support, open source automotive AI software on R Car, and a dedicated physical AI robotics lab tightens Renesas Electronics’ link to real world AI, industrial HMI and autonomous driving workloads. These developments can influence how customers commit future design wins.
- With Renesas Electronics pushing low power HMI MPUs and open source autonomous driving AI on R Car, we will assess how this reshapes its investment narrative.
Scan beyond Renesas Electronics and size up other plays building the hardware behind AI and robotics workloads with our curated list of 89 AI infrastructure stocks.
Renesas Electronics Investment Narrative Recap
To own Renesas Electronics, you need to believe its heavy spending on automotive, industrial and physical AI chips turns into steadier earnings over time. The recent HMI and IoT MPU launches lean into that thesis by targeting connected devices and energy efficiency. The most immediate swing factor still looks operational. Demand visibility in automotive and parts of industrial remains patchy, so order trends and inventory levels matter far more near term than any single product. High R&D and SG&A also sit in the foreground. If revenue timing slips, profitability can come under pressure quickly.
The RZ/G3L and RZ/G3SE announcement is closest to the core catalysts around industrial IoT and edge computing. These MPUs target always on equipment that cares about power draw, security and connectivity, which lines up with tighter energy rules and factory digitalisation themes. The ecosystem support, from GUI tools to operating systems and SoMs, reduces friction for customers looking to ramp designs on Renesas silicon. Execution risk stays real. The business still needs customers to adopt these platforms at scale and at acceptable pricing, while fending off fierce competition and managing any trade barriers.
Yet before treating the physical AI and edge story as a straight line upward, it is worth focusing on ...
Read the full Renesas Electronics narrative to see the case behind these numbers.
Renesas Electronics' current loss of ¥9.6 billion and analysts' expected earnings of ¥398.3 billion by 2029 imply an earnings increase of about ¥408 billion. That forecast is tied to an 11.7% yearly revenue growth rate and a projected top line of ¥1,939.0 billion in the same year.
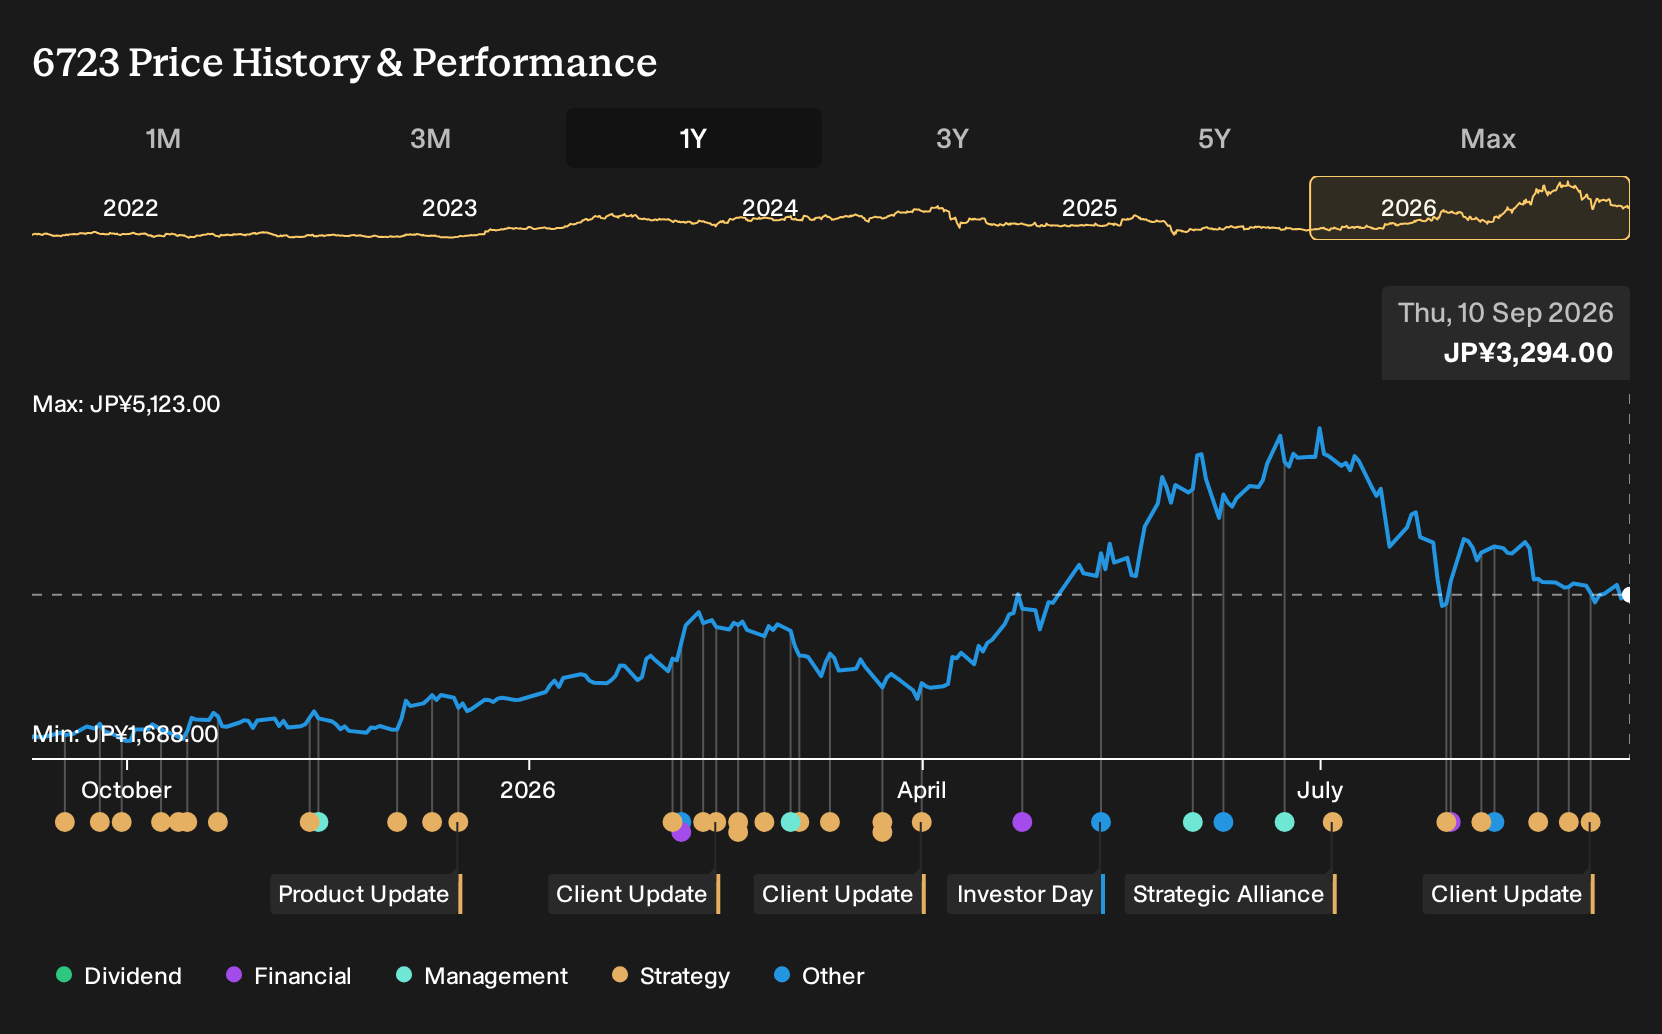
Renesas Electronics' forecasts show a fair value of ¥4858 against a ¥3294 share price, a 47% upside to its current price.
Exploring Other Perspectives
One alternate view sees Renesas Electronics’ heavy automotive exposure as the real swing factor, not its HMI and edge launches. Those bearish analysts were modelling slower revenue growth to ¥1,663.3b and earnings of ¥319.2b by 2029. That is far below consensus, and it shows how sharply opinions can split before today’s AI and robotics news is fully reflected.
To see how your view compares with the crowd, check out 2 other fair value estimates for Renesas Electronics.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Renesas Electronics research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Renesas Electronics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Renesas Electronics' overall financial health at a glance.
Looking For More Investment Ideas Beyond Renesas Electronics?
If Renesas Electronics has sharpened your focus on where real-world AI and hardware intersect, it can be useful to widen the lens and see how other companies stack up on quality, income potential and balance sheet strength.
- For investors who want income with fewer surprises, consider companies in our list of 18 dividend fortresses that pair higher yields with more resilient cash flows.
- If the goal is to find quality at a sensible entry point, scan the 17 high quality undervalued stocks that combine solid fundamentals with prices that screen as below their fair value estimates.
- For a focus on financial resilience, filter for businesses in the list of solid balance sheet and fundamentals (19 results) to see which operators carry lower debt and stronger liquidity backstops.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com