
WESCO International (WCC) Could Be 42% Below Fair Value As Dividend Lands
WESCO International (WCC) is back on income investors’ radar after its board approved a quarterly cash dividend of US$0.50 per share, payable on September 30, 2026, to shareholders of record on September 11.
The dividend decision comes as WESCO International trades at US$355.51, following a 7 day share price return of 6.8% and a year-to-date share price gain of 41.01%. The 1 year total shareholder return of 66.69% and 5 year total shareholder return of 216.94% provide context that income focused investors may consider alongside the new payout.
Scan 39 power grid technology and infrastructure stocks that, like WESCO International, are tied to power infrastructure and may react quickly when dividend decisions and capital allocation plans hit the market.
After a 41.0% year to date run and a dividend now in play, WESCO International trades well below some analyst targets yet above certain intrinsic estimates. Where does fair value really land in that spread?
Most Popular Narrative: 13.5% Overvalued
WESCO International closed at $355.51, while the most widely followed fair value narrative lands at $313.25, which implies a meaningful valuation gap that hinges on a specific set of growth and margin assumptions.
Heavy reliance on AI driven data center projects, which now represent about 24% of quarterly sales and roughly US$4.8b of trailing 12 month revenue, leaves the company exposed to any slowdown or reprioritisation in hyperscaler and colocation build plans. This could pressure revenue growth and limit operating leverage.
Curious what kind of future revenue mix and profitability profile need to hold for WESCO International to justify that fair value math. The narrative leans heavily on compounded top line expansion, firmer margins and a lower future earnings multiple all working together in a tight range of outcomes. The puzzle is how those moving parts balance against each other over time.
Result: Fair Value of $313.25 (OVERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, if WESCO International keeps converting its record backlog and if data center demand remains resilient, that could challenge the bearish fair value story.
Find out about the key risks to this WESCO International narrative.
Another View on WESCO International’s Value
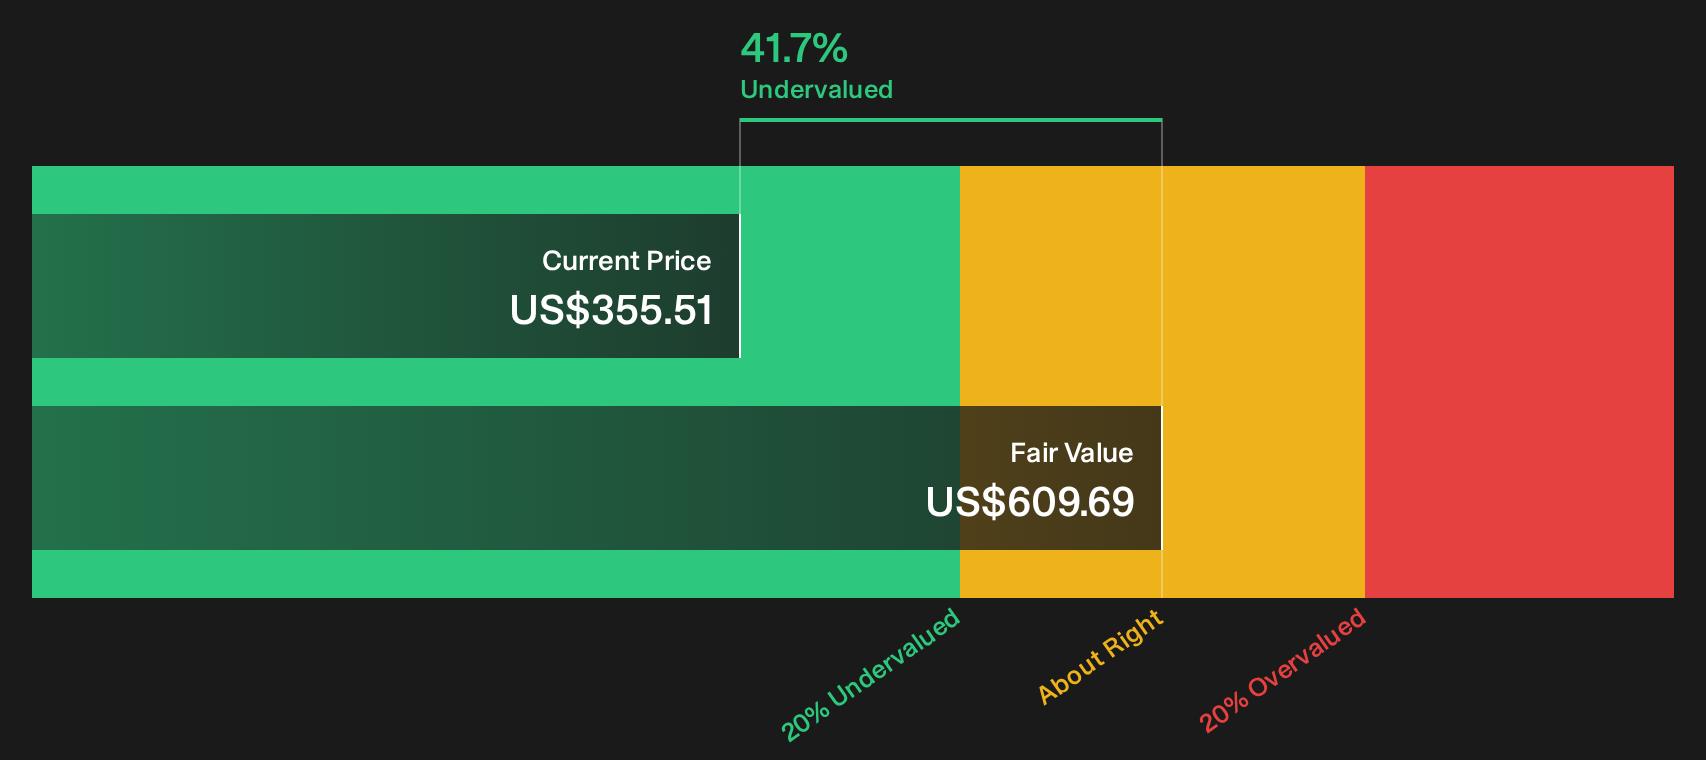
A different lens tells a very different story. Our DCF model puts WESCO International’s fair value at $609.69, compared with the current $355.51 share price. That is a wide gap in the other direction, which raises a simple question: Are analysts too cautious or is the DCF too generous?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed messages on WESCO International’s value story. If you want to move fast and build your own stance, start by weighing its 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond WESCO International?
Do not stop your research with WESCO International. Fresh opportunities often show up where fewer investors are looking, and that is where careful screening really pays off.
- Target resilient balance sheets and steady fundamentals by running the list of solid balance sheet and fundamentals (24 results) before capital shifts toward higher risk ideas.
- Hunt for mispriced quality and let the 31 high quality undervalued stocks surface stocks where business strength and current pricing sit out of sync.
- Prioritise income potential and stability by scanning the 6 dividend fortresses so reliable cash payouts do not slip past your watchlist.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com