Qunzhi Consulting: The smartphone panel market continued to be structured in the fourth quarter, and overall prices continued to weaken
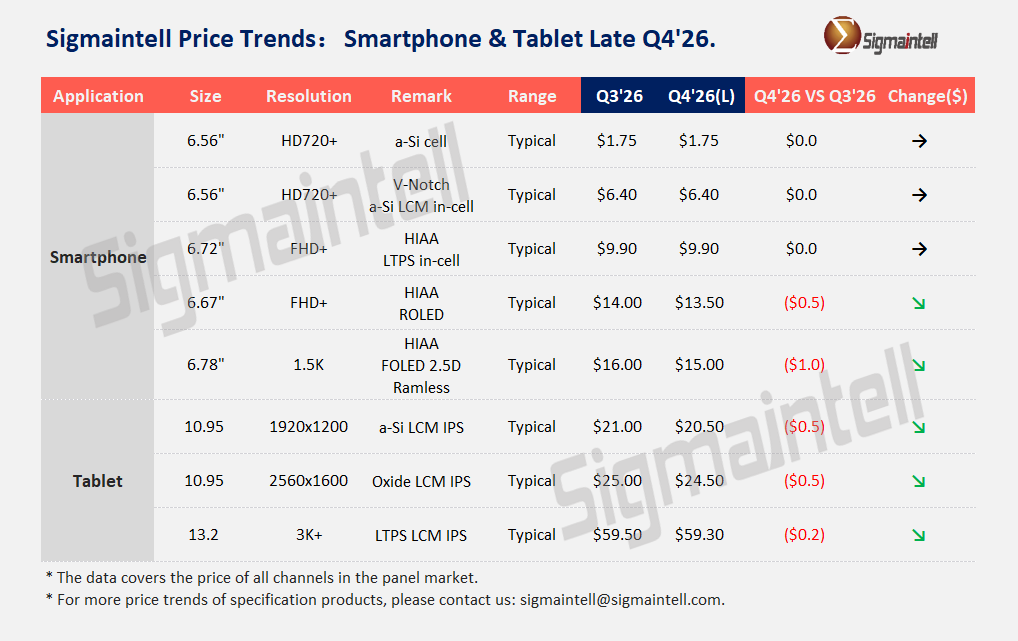
The Zhitong Finance App learned that on November 20, Qunzhi Consulting released the smartphone & tablet panel price trend vane for the fourth quarter of 2026. The smartphone panel market continued to be structured in the fourth quarter of 2026, but the original demand support weakened marginally: as channel inventory continued to accumulate, the incremental support momentum of the maintenance market weakened. At the same time, due to the rise in the price of complete machines, the consumer switching cycle has been extended, the traditional peak season effect has weakened, and the brand's willingness to pull goods has not improved significantly. Under the double pressure of weakening demand and rising costs, the transmission of panel factory costs to the downstream was blocked, and the overall price trend continued to be weak.
Price trends for each technology route:
a-Si LCD: Maintenance market support weakens, prices remain
In the fourth quarter, the demand support momentum of the a-Si LCD repair market weakened, channel inventory continued to accumulate, and the sustainability of demand was tested. At the same time, the cost control of low-end models by brands has become more strict. Module procurement has paid more attention to cost control and price in exchange for volume. Competition for new projects has intensified, and prices for some projects have declined.
On the other hand, due to the continued rise in the prices of raw materials such as Driver IC, the cost pressure on module manufacturers continues to increase, but due to weak brand demand and overall machine cost control, it is difficult for the time being to effectively transmit the cost increase downstream. Qunzhi Consulting expects the overall module price to be maintained in the fourth quarter.
Looking ahead to Q1 2027, if the prices of raw materials such as Driver ICs continue to rise, the cost pressure on module manufacturers will accumulate, and there is a risk that module prices will rise.
LTPS LCD: Demand is coming to an end, and the bottom of the price is stabilizing
With the bidirectional replacement of Foled and a-Si LCDs, market demand for LTPS LCDs is shrinking at an accelerated pace as a transition technology. Orders for the fourth quarter were further concentrated on stock projects and final orders. Both supply and demand lacked obvious momentum for price adjustments. Qunzhi Consulting expects prices to remain stable at the bottom.
ROLED (rigid OLED): demand sources are narrowing, and prices are stable to weak
As mid-range models are upgraded to FOLED at an accelerated pace, ROLED's application space in the new machine market continues to shrink, stock maintenance requirements are also gradually migrating to FOLED, and the source of demand is further reduced. With insufficient support for new projects, it is expected that ROLED prices will continue to be steady, moderate, or weak in the fourth quarter.
FOLED (flexible OLED): competition in the low-end market intensifies, prices continue to decline
Demand for Apple's high-end models has remained relatively stable, and related supply chain production lines have maintained a high level of operation, which supports the FOLED market.
However, at the same time, demand from domestic terminal brands is expected to weaken, and the flexibility of low-end models has become an important breakthrough for panel manufacturers to expand shipments. In order to compete for middle- and low-end market projects, domestic panel manufacturers continue to adopt active price competition strategies, and market competition has further intensified. FOLED prices are expected to continue their overall downward trend in the fourth quarter
Tablet:
Whole machine brands have raised product prices in multiple rounds. The increase in terminal prices has suppressed consumer and education market demand to a certain extent, and procurement momentum has weakened.
However, at the same time, the cost pressure on panel manufacturers is also prominent. Prices of some products are gradually bottoming out, further limited room for price concessions, and market price reduction expectations have weakened accordingly. Taken together, the price of tablet panels showed a slight downward trend in the fourth quarter.
Price trends for each technology route:
a-Si LCD: The basic market position in the middle and low end has not changed. Oxide replacement continues, but the cost poses a hard constraint, and the room for price reduction is narrow.
Oxide LCD: As more panel manufacturers participate in the Oxide LCD market, supply competition continues to intensify. At the same time, the demand for cost control and price reduction for mid-range products by machine brands has increased. Affected by this, the prices of existing old projects only declined slightly, while the price drop for new projects was relatively large due to more intense competition.
LTPS LCD: Supply is concentrated in the high-end specification segment with large size and high resolution, and demand has declined moderately. However, the operating rate of the production line is mainly maintained by in-vehicle orders, so the overall price drop is relatively limited.