
What Equity Group Doubters Missed
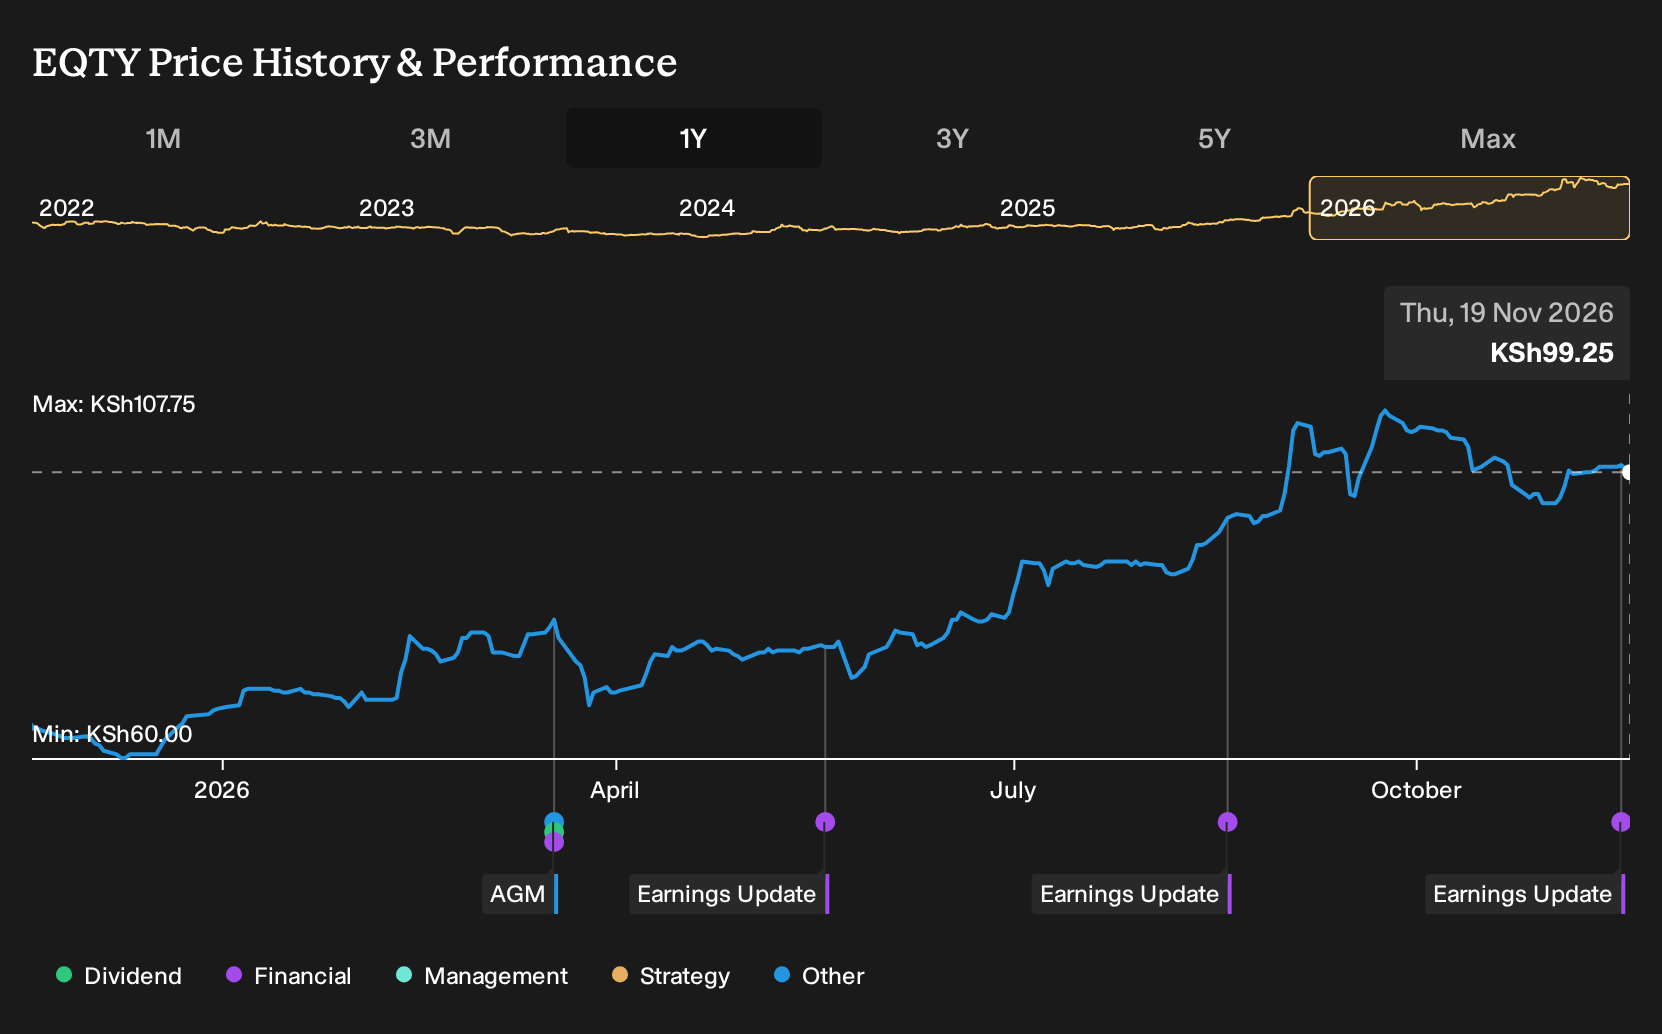
Investors who held Equity Group over the past year are up 67.8%, including dividends. That kind of payoff turns a dry November 2025 debate into a very personal what if. If you had been weighing the promise of higher-yield lending and digital expansion against worries about fintech pressure and riskier credit, which side of that argument would have felt strong enough to back with real money?
If the move has made Equity Group harder to judge, start where the gap is still open and scan 217 high quality undervalued stocks.
The Two Equity Group Stories Investors Were Arguing About
The shares cost KES64 at the start of the period, and the live question was which Equity Group story you believed.
On the optimistic side, one Narrative saw a Fair Value of KES70.32, a notional price implied by its assumptions, built on a shift of over KES450b from lower yielding government paper into higher yielding SME and customer loans.
The more cautious view was anchored on a Fair Value of KES53.5, again an assumption-driven figure. This view focused on rising fintech competition and the risk that more payments, deposits, and lending would bypass traditional banking altogether.
What The Results Changed For The Equity Group Argument
The clearest new fact was Equity Group’s Q3 2026 report. Total revenue was KES63,435.243m against KES51,322.782m a year earlier, while net income moved from KES18,812.192m to KES24,969.137m and net margin went from 36.7% to 39.4%. Those numbers leaned toward the optimistic case that higher yielding lending and digital scale could support higher profitability, although fintech and credit risks were not disproved.
The lesson travels well. When a bank describes a shift into richer loans and digital channels, track total revenue, net profit and especially net margin over a few reporting dates. You are testing whether the promised mix change shows up as stronger profitability rather than just a larger balance sheet.
What Equity Group’s Price Already Bakes In
Today Equity Group trades at KES99.25. The analyst consensus Narrative on Simply Wall St sees a Fair Value above that level, tied to how effectively the bank turns its balance sheet, regional reach and digital usage into earnings power rather than idle scale.
As a buyer now, you would be judging whether Equity Group can keep shifting liquid assets into higher yielding loans while holding credit costs in check as older problem exposures are worked through.
"The main thing that has to go right is that Equity Group Holdings converts its very liquid balance sheet and regional deposit base into higher yielding, well provisioned lending while keeping credit costs under control as legacy non-performing loans are worked down."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Looking One Step Beyond Equity Group
Equity Group invites one question. Where else are banks chasing similar prize pools in payments, wealth and digital everyday banking?
Some lenders are pouring heavy resources into card platforms, mobile wallets and online portals so each new client interaction can carry more fee potential.
That same push reaches into asset and wealth management, where rising client balances and more complex portfolios can support richer service menus.
To make it all work, another large institution is leaning on big technology and AI budgets, higher running costs and stricter capital rules.
The interesting part is how that tradeoff between heavier investment and tighter regulation could reshape what long term earnings power looks like.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 17% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com