
Is CSX (CSX) Undervalued As Its New $1.2b Credit Line Keeps Liquidity Steady?
CSX (CSX) refreshed its liquidity setup on 17 November 2026 by entering a new US$1.2b five year senior unsecured revolving credit agreement, while terminating an identically sized facility from February 2023.
CSX shares have eased in the short term, with the share price down 2.63% over the last day and 4.62% over the past week, while the stock shows a year to date share price return of 37.80% and a 1 year total shareholder return of 50.30%. This indicates strong long term momentum despite the recent pullback around this new credit facility.
Compare CSX's renewed credit firepower with other businesses that combine balance sheet strength and earnings quality in our curated list of solid balance sheet and fundamentals (25 results) for additional ideas beyond the rails.
After a 50.30% 1 year total return and a fresh US$1.2b credit line untouched, CSX now sits at a crossroads. Is most of the rerating done, or is there still clear upside ahead on valuation?
Most Popular Narrative: 5.9% Undervalued
On the analyst consensus Narrative on Simply Wall St, CSX is valued at $53.10 per share using an 8.62% discount rate, compared with the latest close of $49.98. That gap frames the stock as modestly undervalued and puts the focus on whether the business can deliver on its efficiency and intermodal ambitions.
Ongoing structural productivity efforts under the current leadership team, including headcount reductions, PS&O cuts, capital efficiency work and a long dated cost pipeline, point to further reductions in non fuel expenses and support for wider net margins and earnings.
See why 28 investors see CSX as 6% undervalued.
Result: Fair Value of $53.10 (UNDERVALUED)
Still, the CSX story can break if service quality weakens again, or if tougher safety and staffing rules push costs higher and squeeze margins.
Find out about the key risks to this CSX narrative.
Another View: CSX Through A Cash Flow Lens
There is a different read on CSX when switching from the analyst fair value of $53.10 to the Simply Wall St DCF model. On that framework, the stock at $49.98 trades above an estimated future cash flow value of $41.72, which points to an overvalued signal instead of a 5.9% discount.
This gap between a cash flow based estimate and a narrative led target leaves investors with a clear judgment call. Should more weight sit on modeled cash generation, or on earnings and margin assumptions that support the higher fair value thesis for CSX, and which risk matters more for your own time horizon?
Look into how the SWS DCF model arrives at its fair value.
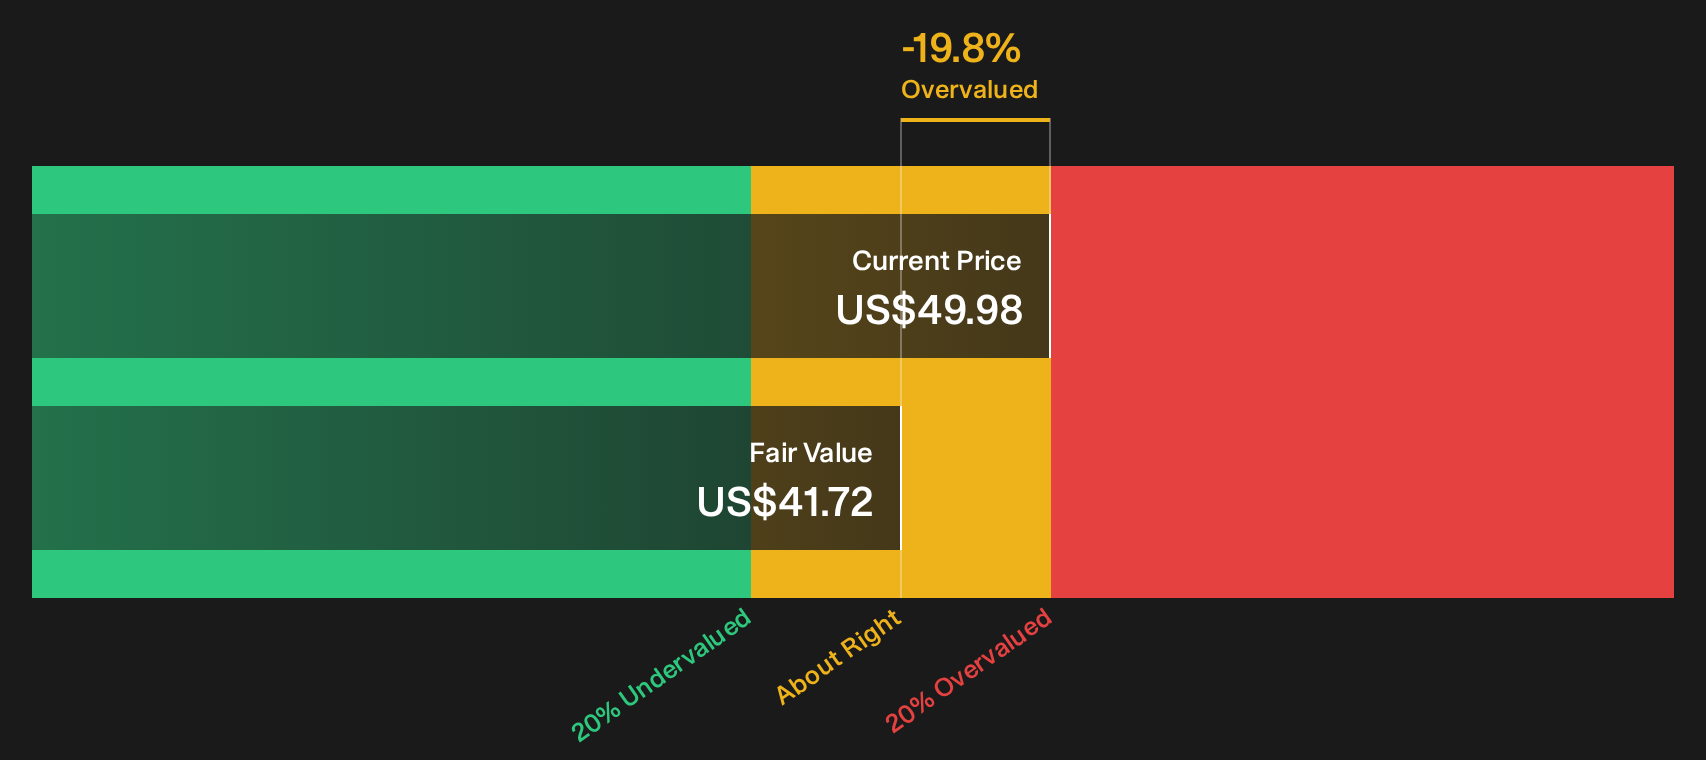
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out CSX for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 36 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on CSX so far, with valuation, cash flow and sentiment all pulling in different directions, mean the next move sits with you. Act while the data is fresh and weigh both sides of the debate by checking 3 key rewards and 1 important warning sign.
Looking for more CSX style investment ideas?
If CSX has sharpened your thinking, do not stop here. Use the Simply Wall St screener to uncover other opportunities before they race away from you.
- Target resilience first and check companies that aim to keep risk scores low through the 30 resilient stocks with low risk scores.
- Hunt for value gaps and scan for quality businesses that still trade below their estimated worth using the 36 high quality undervalued stocks.
- Prioritize steady income potential and review companies with higher yield profiles through the 8 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com