
Does FireCuda Forge Launch Change The Bull Case For Seagate Stock (STX)?
- Seagate Technology Holdings introduced the FireCuda Forge hard drive powered by its Alkemi intelligent storage platform, combining SSD-like responsiveness with HDD capacity for gamers and creators, with 8 TB and 20 TB options starting at US$699 and US$899.
- The Alkemi platform brings enterprise-style intelligent data tiering into consumer systems by dynamically caching frequently accessed content on a user-supplied NVMe SSD while using high-capacity HDD storage for larger libraries, with the aim of simplifying fast access to growing data workloads.
- We will now see how Seagate’s Alkemi powered FireCuda Forge launch could shape the broader investment narrative built around AI storage.
Seagate Technology Holdings Investment Narrative Recap
To own Seagate Technology Holdings, you need to believe hyperscale and AI storage demand remains strong enough for nearline HDDs and HAMR technology to stay central to data-center architectures. According to isidrohg, an investor in the Simply Wall St Community, the key thesis is a tight duopoly, limited new capacity, and Seagate’s cost curve driven by HAMR areal density. The short term swing factor remains how pricing and volumes hold up as supply agreements roll through 2027, while the main near term worry is a classic hardware down-cycle that erodes that pricing power.
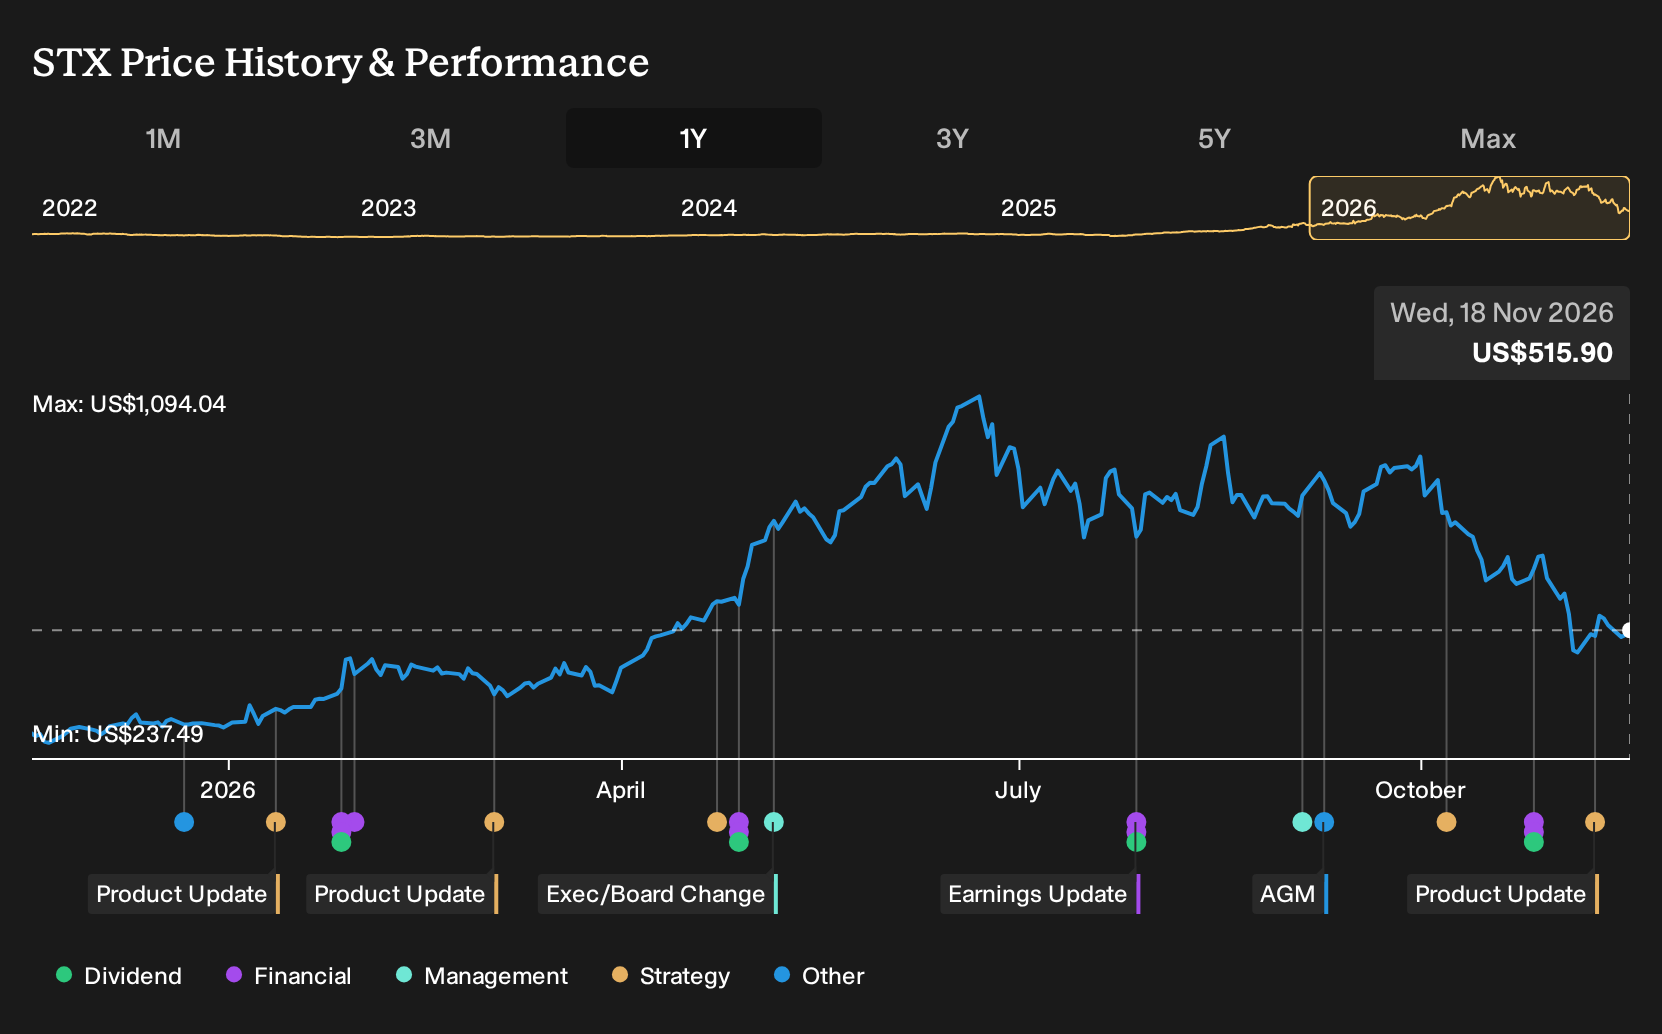
The FireCuda Forge launch with Alkemi does not change that core nearline story. However, it does show Seagate trying to extend its AI storage narrative onto the desktop. The firm is already seeing strong revenue and margin performance tied to data-center demand and HAMR adoption, with investors watching HAMR penetration milestones and contract duration closely. Recent share price volatility and significant insider selling underline how quickly sentiment could turn if orders, pricing, or HAMR execution slip.
The Anthropic IPO read-through is probably the most relevant recent event for this FireCuda Forge discussion. Anthropic disclosed nearly US$901b of committed spend tied largely to compute and mass storage, and Seagate stock jumped more than 8% alongside other storage peers on that AI infrastructure enthusiasm. That reaction underlines how tightly Seagate is now linked to AI data growth in investors’ minds, even when the news is not about the company directly.
For you as a shareholder, the operational hinge points remain clear. Management is ramping HAMR based Mozaic drives, reporting higher margins, and has long term supply visibility into 2028, while also planning to allocate 75% of free cash flow to share repurchases. At the same time, risks flagged by isidrohg around a cycle turn, Western Digital closing the HAMR gap, and potential capacity additions are still in play regardless of how quickly Alkemi or AI themed demand gain traction.
On those figures, the narrative from isidrohg lands at a fair value of US$1,159 per share by applying 22.5% annual revenue growth and a 26.1% future profit margin to Seagate’s current run-rate, then capitalising those earnings on a P/E multiple in line with historic HDD sector ranges.
Uncover why Seagate Technology Holdings' fair value indicates a 125% potential upside to its current price that may not be available for long.
Exploring Other Perspectives
Some of the most optimistic analysts on Seagate Technology Holdings frame the real catalyst as structurally higher profitability. Before the FireCuda Forge news, the most bullish forecasts already pointed to revenue growth of 49.7% a year and earnings of about US$26.3b by 2029. That is a far more optimistic path than the baseline cycle focused view you just read, so it is worth treating this launch as a fresh reason to compare several competing narratives rather than assume any one of them is settled.
Explore 6 other Seagate Technology Holdings fair value estimates, including one that suggests a potential 191% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own research and judgment.
- A great starting point for your Seagate Technology Holdings research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Seagate Technology Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to review Seagate Technology Holdings' overall financial position at a glance.
Looking for more investment ideas beyond Seagate Technology Holdings?
If the Seagate Technology Holdings story has sharpened your thinking on AI infrastructure, broaden the search and stress test your thesis across a wider watchlist using the Simply Wall St Screener.
- For investors hunting mispriced quality, scan a curated pool of potential value opportunities through the 35 high quality undervalued stocks to see which businesses match your return hurdles.
- If resilience matters more than excitement, focus on balance sheet strength and funding flexibility by starting with the list of solid balance sheet and fundamentals (24 results) and filtering for companies that fit your risk comfort zone.
- When income is the priority, anchor your watchlist around reliable cash distributions by screening for 8 dividend fortresses that may suit a more yield focused approach.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com