
How to Play OKLO Stock as Oklo Secures Key Fuel Supply for Its Ohio Plant
Advanced nuclear technology company Oklo (OKLO) recently signed multiple definitive, multi-year contracts with Centrus Energy (LEU), securing a supply of high-assay low-enriched uranium (HALEU). This deal formalizes the letter of intent the companies had signed back in June and includes enough HALEU to support up to five Aurora powerhouses for multiple years.
The company’s HALEU purchase is supported by a prepayment from Meta Platforms (META) for future Oklo power production and secures fuel for the first phase of Oklo’s planned 1.2 GW power campus in Ohio. Oklo believes that these fuel supply agreements would help scale its power business beyond its first reactor and other Aurora deployments.
In addition, the company signed a strategic manufacturing agreement with U.S. Forged Rings (USFR) to secure future domestic production of large components for its Aurora powerhouses. This helps address a bottleneck for future deployments as reserved domestic capacity comes online for large components within the Aurora reactor module system.
Oklo also updated investors on its Groves Isotope Test Reactor (Groves-1), which received clearance for the final operations hold point from the U.S. Department of Energy (DOE) through the Reactor Pilot Program (RPP). With this, the facility can move into its research, testing, and training phase.
As the company looks toward expansion, it may be wise to explore it. However, markets have turned a bit sour on Oklo’s growth prospects, leading to a selloff in its stock over the past year. Therefore, it might be wise to wait for a better trigger point.
About OKLO Stock
Oklo is a nuclear energy company headquartered in Santa Clara, California. It develops small, fast-fission power plants called Aurora powerhouses. These plants are designed to produce clean, reliable electricity and heat for data centers, factories, remote communities, and military sites. Oklo also recycles used nuclear fuel into new fuel and produces important isotopes. Its goal is to make clean nuclear energy more affordable and available at a larger scale. The company has a market capitalization of $4.67 billion.
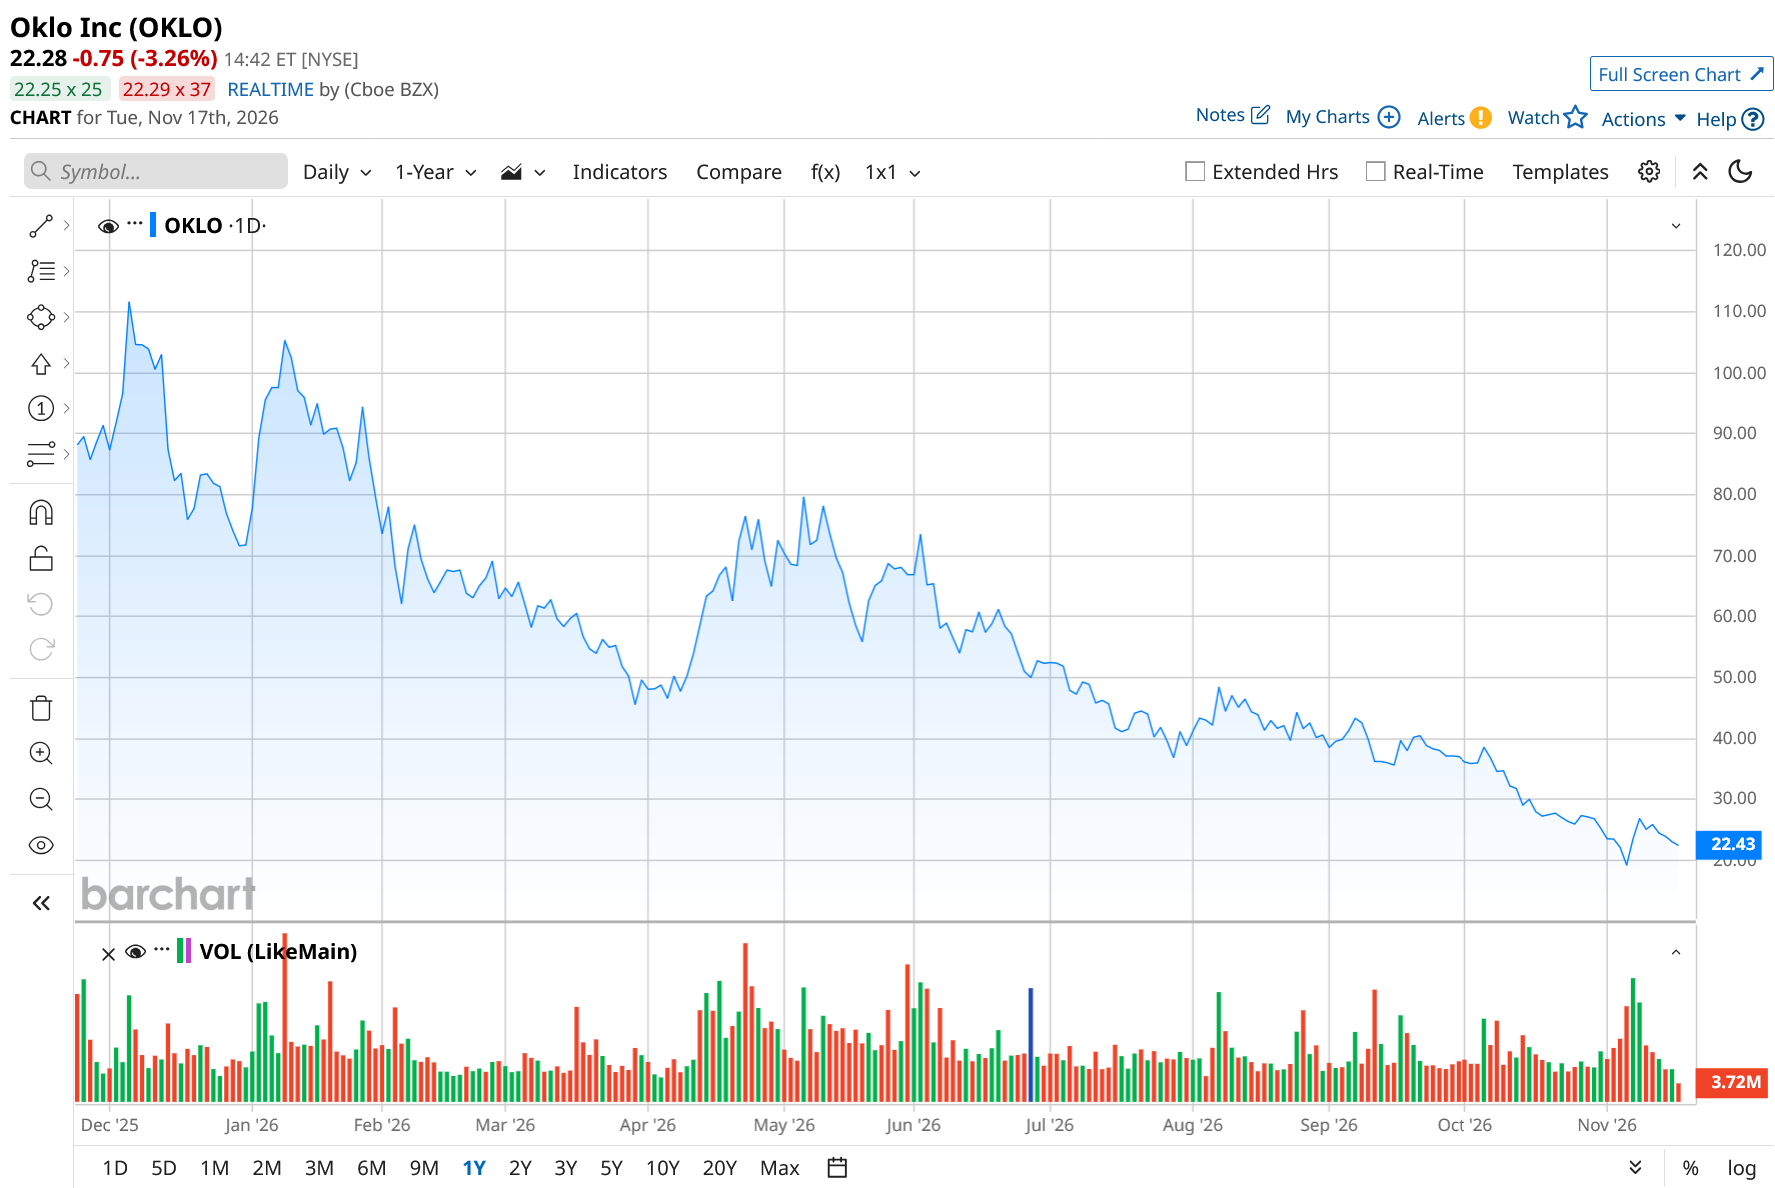
Oklo’s stock has fallen about 76% over the past 52 weeks because investors have become less excited about its high-growth plans. The company’s shares rose sharply when people expected AI data centers to need large amounts of clean nuclear power. But as confidence in AI infrastructure spending weakened, investors lowered their expectations for Oklo’s future growth. Over the past six months, OKLO stock has dropped 70%. It reached a 52-week low of $18.53 on Nov. 5, but is up 20% from that level. Despite the steep selloff, the stock’s valuation remains sky-high.
Oklo Reported Q3 Results as It Advances Reactor Development
For the third quarter, Oklo generated $1.86 million in revenue. However, losses also climbed in tandem. Its net loss per share climbed from $0.20 in Q3 2025 to $0.22 in Q3 2026. For the nine months ended Sept. 30, Oklo exited the period with $1.63 billion in cash, cash equivalents, and restricted cash. This was mainly due to financing activities, including $2.30 billion raised in the first three quarters through successful ATM offerings.
Wall Street analysts are pessimistic about Oklo’s bottom-line trajectory. For fiscal 2026, the company’s loss per share is expected to widen 37.5% year-over-year (YoY) to $0.99, followed by another 24.2% increase to $1.23 in fiscal 2027. For the fourth quarter, loss per share is expected to increase 3.7% YoY to $0.28.
What Do Analysts Think About OKLO Stock?
This month, Truist Securities analyst Christopher Souther maintained a “Hold” rating on OKLO stock and cut the price target from $31 to $28. Canaccord Genuity analysts also maintained a “Buy” rating on the stock but reduced the price target from $100 to $66. HC Wainwright & Co. reiterated its rating, with analyst Sameer Joshi maintaining a “Buy” rating. The price target remains steady at $90. Based on recent analyst stances, there is cautious optimism around Oklo.
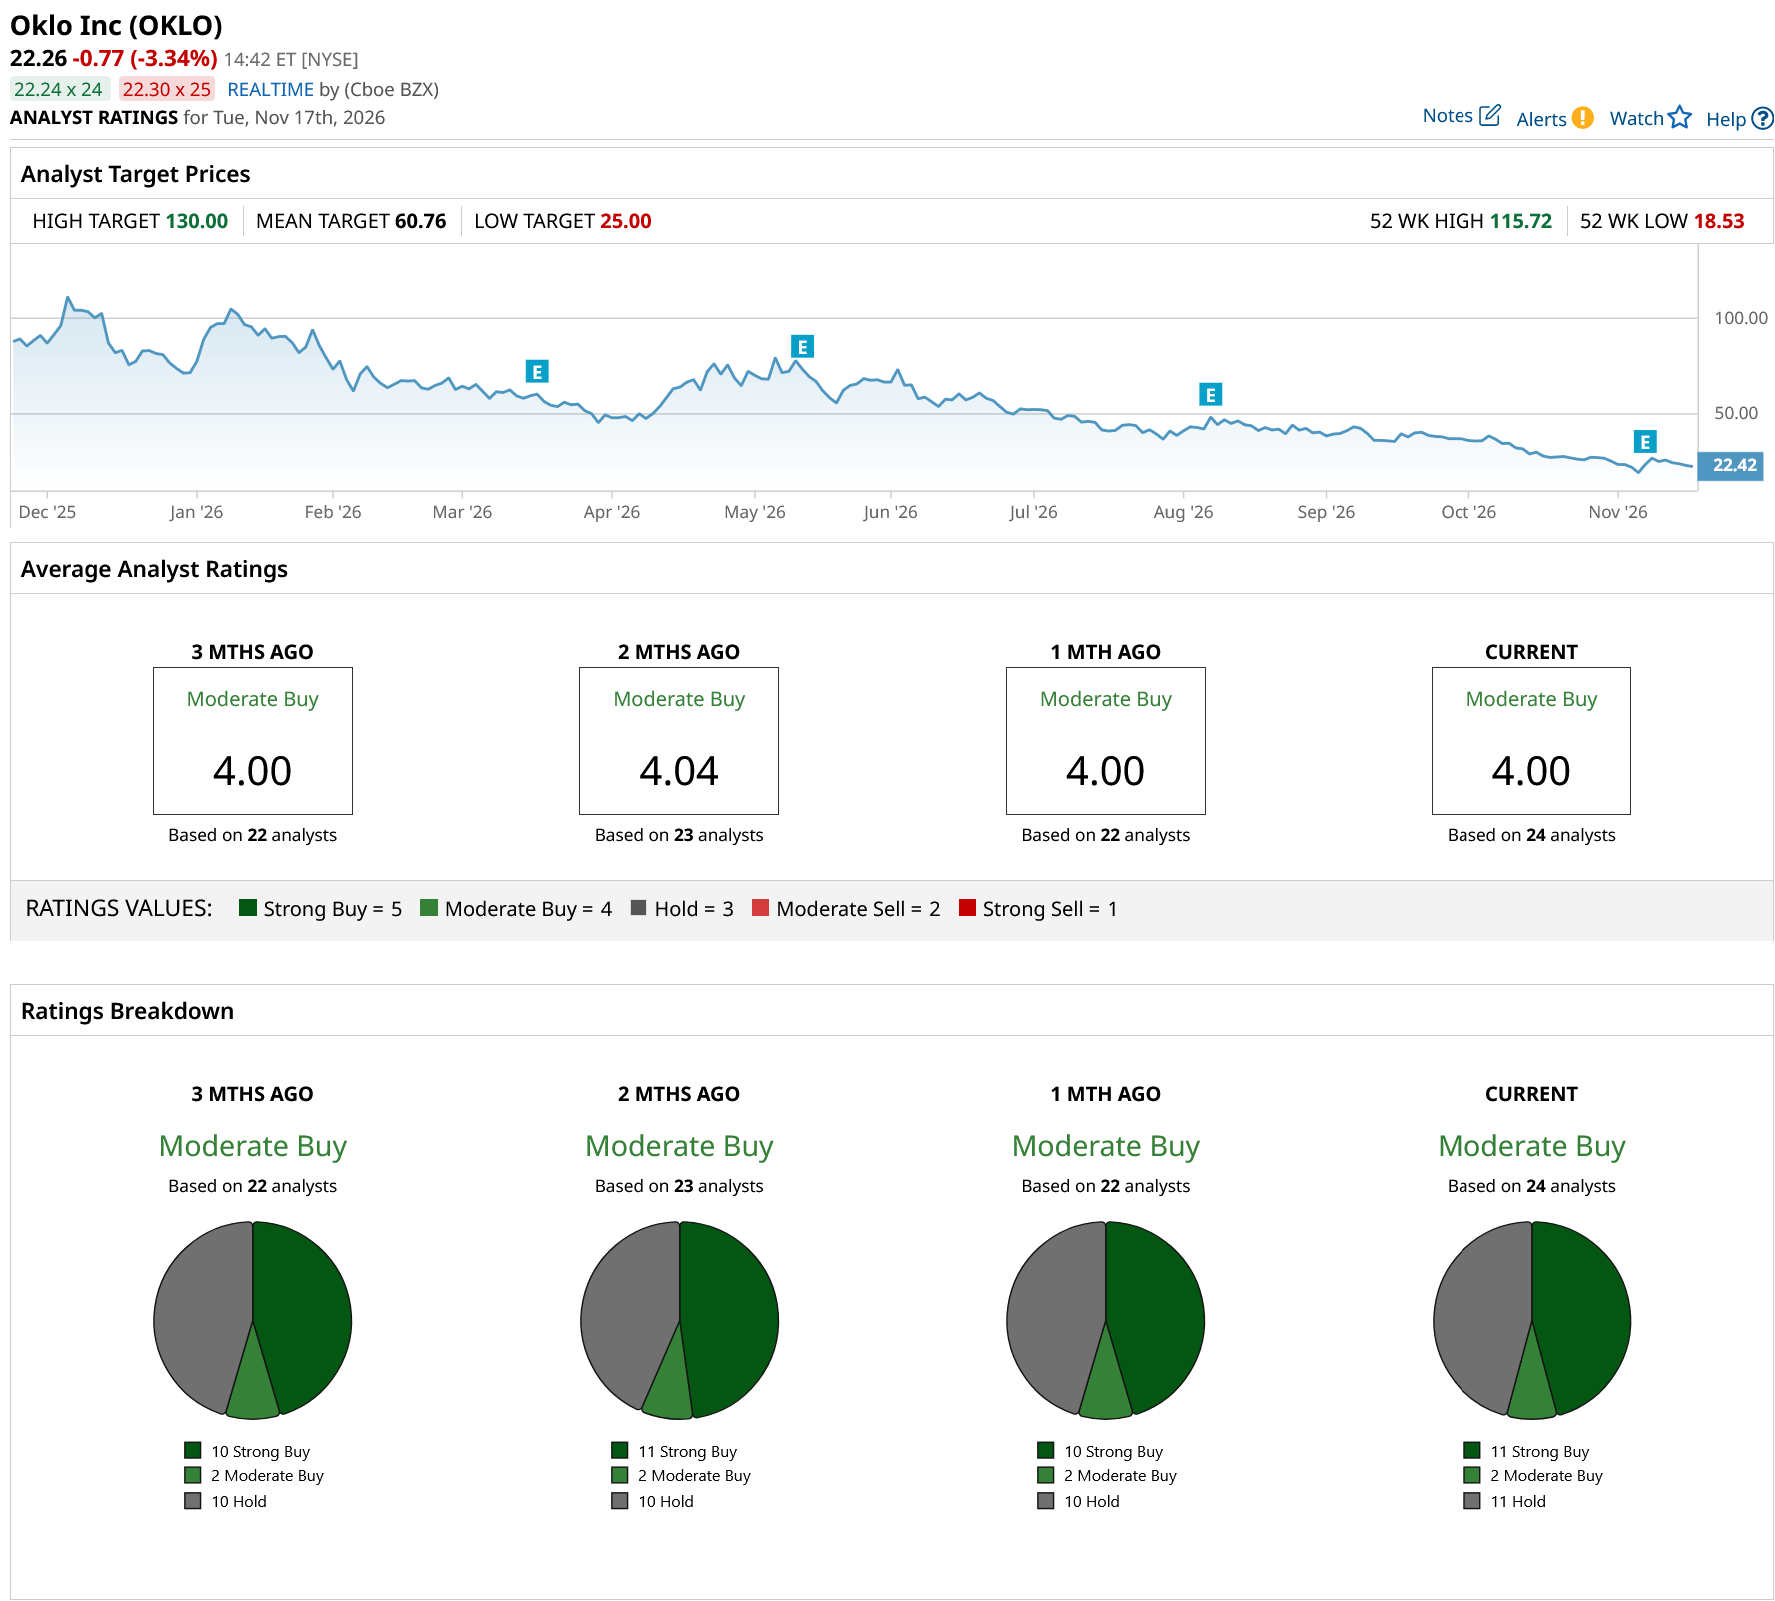
OKLO stock remains well liked on Wall Street, with analysts awarding it a consensus “Moderate Buy” rating. Of the 24 analysts rating the stock, 11 have given it a “Strong Buy” rating, two have suggested a “Moderate Buy,” and 11 have taken a middle-of-the-road approach with a “Hold” rating. The consensus price target of $60.76 represents a 173% upside from current levels. Moreover, the Street-high price target of $130 implies a 484% upside.
On the date of publication, Anushka Dutta did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.