
Energizer reports sales below analyst estimates in Q3 CY2026 earnings
Battery and lighting company Energizer (NYSE:ENR) fell short of the market’s revenue expectations in calendar Q3 2026 [fiscal Q4 2026], with revenue falling 4.8% year on year to $793.2 million. Its non-GAAP profit of $1.37 per share was 5.7% above analysts’ consensus estimates.
For more on Energizer, read our full research report, available free.
Energizer Q3 CY2026 highlights:
- Revenue $793.2 million vs S&P analysts’ consensus estimates of $807.6 million (4.8% year-on-year decline, 1.8% miss)
- Adjusted EPS $1.37 vs S&P analysts’ consensus estimates of $1.30 (5.7% beat)
- Adjusted EBITDA $193.1 million vs analysts’ consensus estimates of $187.6 million (24.3% margin, 2.9% beat)
- EBITDA guidance $570 million at the midpoint for fiscal 2027, below analysts’ consensus estimates of $593.3 million
- Free cash flow margin 15.6%, up from 5.6% in the same quarter last year
- Organic revenue was flat year on year (miss)
- Market capitalization $1.67 billion
"Energizer delivered a strong finish to fiscal 2026, with improved margins, higher earnings and substantial free cash flow generation in the fourth quarter," said Mark LaVigne, Chief Executive Officer. "The work completed through Project Momentum has strengthened our operating model and created a solid foundation for the future. We expect to leverage that foundation to drive a meaningful step-up in free cash flow, providing greater capacity to invest behind our brands, reduce debt and return capital to shareholders."
Revenue growth
A company’s long-term performance is an indicator of its overall quality. Any business can deliver a good quarter or two, but the best consistently grow over the long term.
With $2.95 billion in revenue over the past 12 months, Energizer carries some recognizable products but is a mid-sized consumer staples company. Its size could bring disadvantages compared to larger competitors benefiting from better brand awareness and economies of scale.
Energizer struggled to increase demand as its $2.95 billion in revenue for the trailing 12 months was close to its revenue three years ago. This shows demand was soft.
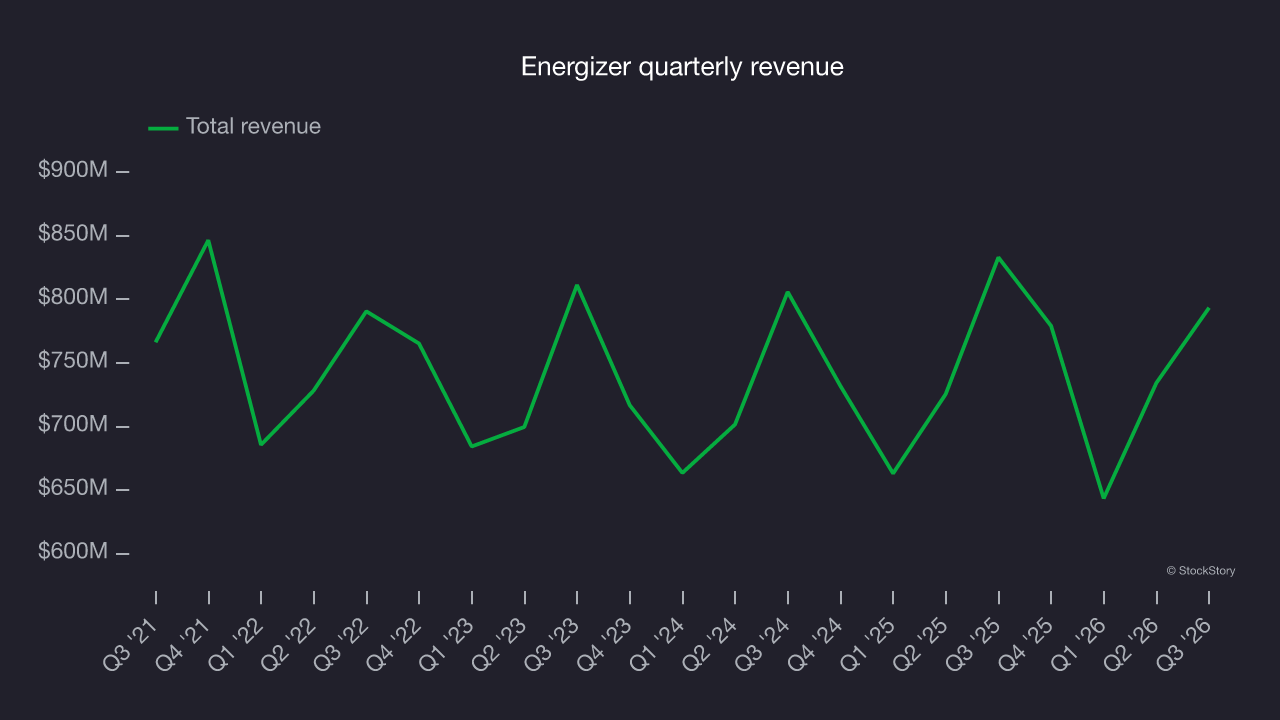
This quarter, Energizer missed Wall Street’s consensus estimates and reported an uninspiring 4.8% year-on-year revenue decline, generating $793.2 million in revenue.
Looking ahead, sell-side analysts expect revenue to remain flat over the next 12 months, according to S&P. This projection is underwhelming and indicates its newer products will not lead to better top-line performance yet.
Organic revenue growth
When analyzing revenue growth, the key metric is organic revenue growth. This metric captures a business’s performance excluding one-time events such as mergers, acquisitions and divestitures as well as foreign currency fluctuations.
The demand for Energizer’s products has barely risen over the last eight quarters. On average, the company’s organic revenue has been flat.
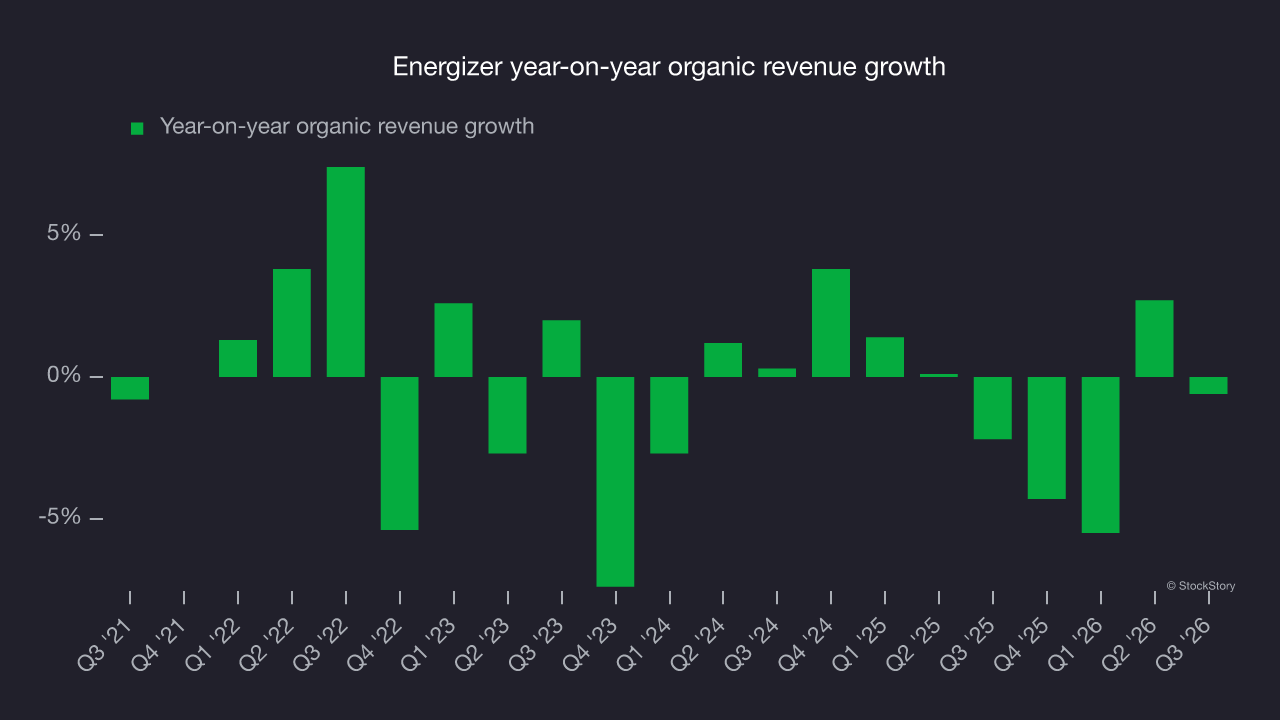
In the latest quarter, Energizer’s organic revenue was flat year over year. This performance was more or less in line with its historical levels.
Key takeaways from Energizer’s Q3 results
Energizer’s revenue fell short of Wall Street’s consensus estimates and gross margin missed expectations. The earnings results offered some positives, with EBITDA and EPS both beating analysts’ consensus estimates. Overall the quarter was mixed. Shares rose 4.8% to $25.51 immediately after the report.
When deciding whether to buy Energizer shares, consider its valuation, business quality and latest quarterly results. For more, read our free full research report here.