
Home Depot’s Q3 2026 sales beat estimates
Home improvement retailer Home Depot (NYSE:HD) reported revenue ahead of Wall Street’s expectations in Q3 2026, with revenue rising 4.9% year on year to $43.4 billion. Its non-GAAP profit of $3.86 per share was 0.6% above analysts’ consensus estimates.
For more on Home Depot, read the full research report for free.
Home Depot Q3 2026 highlights:
- Revenue $43.4 billion vs S&P analysts’ consensus estimates of $42.72 billion (4.9% year-on-year growth, 1.6% beat)
- Adjusted EPS $3.86 vs S&P analysts’ consensus estimates of $3.84 (0.6% beat)
- Adjusted operating income $5.66 billion vs analysts’ consensus estimates of $5.59 billion (13% margin, 1.3% beat)
- Operating margin 12.6%, in line with the same quarter last year
- Free cash flow margin 7.2%, similar to the same quarter last year
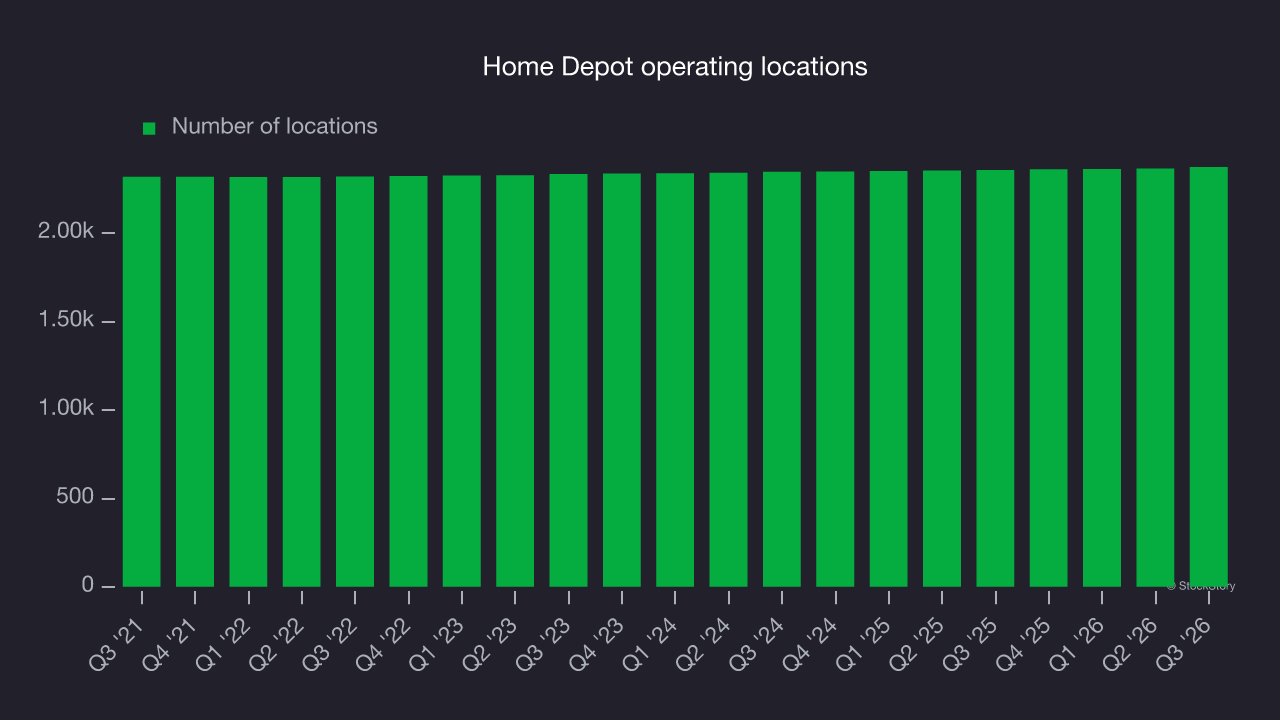
- Locations 2,372 at quarter end, up from 2,356 in the same quarter last year
- Same-store sales rose 2.2% year on year (0.2% in the same quarter last year)
- Market capitalization $346.7 billion
"Results in the third quarter exceeded our expectations. Our associates' strong engagement and exceptional execution, combined with our continued investments across the business, enabled us to grow market share in a dynamic environment," said Richard McPhail, incoming chief executive officer.
Revenue growth
A company’s long-term performance is an indicator of its overall quality. Even a bad business can perform well for one or two quarters, but a top-tier one grows for years.
With $171.2 billion in revenue over the past 12 months, Home Depot is a major player in the consumer retail sector and benefits from economies of scale, giving it an edge in distribution. This also enables it to gain more leverage on its fixed costs than smaller competitors and gives it the flexibility to offer lower prices. However, its scale is a double-edged sword because there is only so much real estate to build new stores, placing a ceiling on its growth. To expand meaningfully, Home Depot likely needs to adjust its prices or enter new markets.
Home Depot’s 3.7% annualized revenue growth over the last three years was sluggish as it didn’t open many new stores.
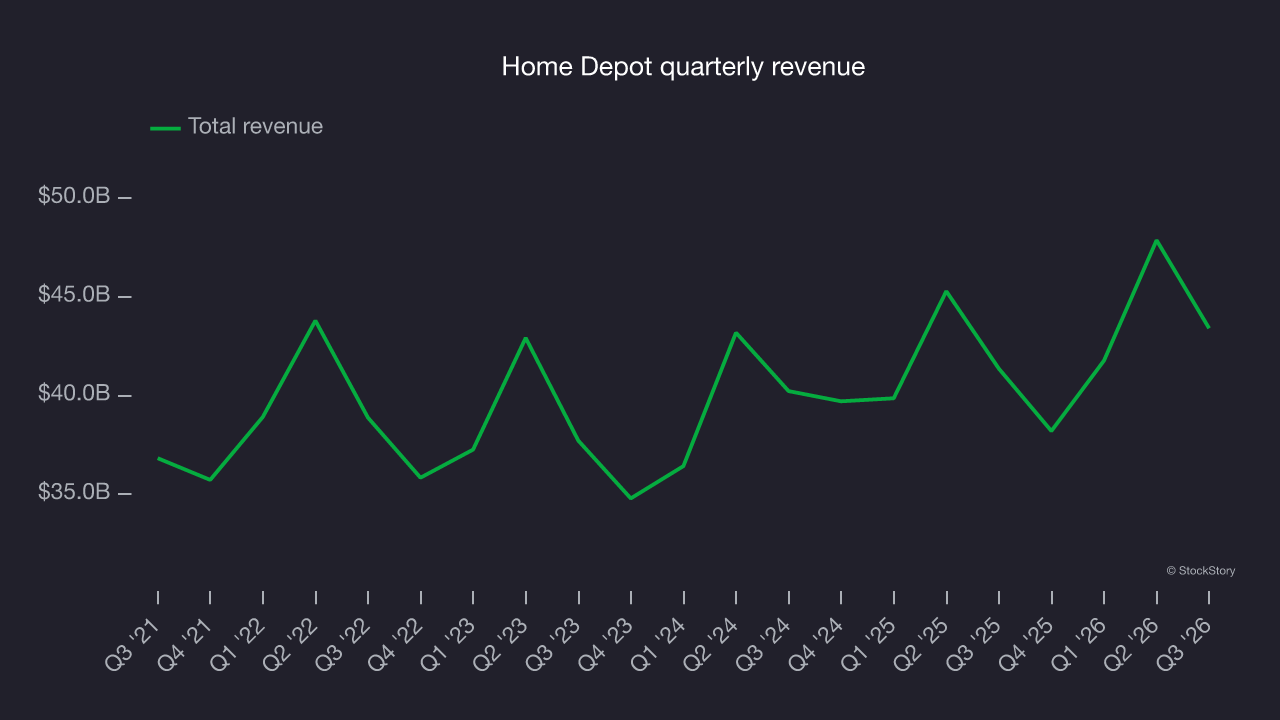
This quarter, Home Depot reported modest year-on-year revenue growth of 4.9% but beat Wall Street’s consensus estimates by 1.6%.
Looking ahead, sell-side analysts expect revenue to grow 2.5% over the next 12 months, according to S&P, similar to its three-year rate. This underwhelming projection implies its products will face some demand challenges.
Store performance
Number of stores
Home Depot operated 2,372 locations in the latest quarter and has kept its store count flat over the last two years while other consumer retail businesses have opted for growth.
When a retailer keeps its store footprint steady, it usually means demand is stable and it’s focusing on operational efficiency to increase profitability.
Same-store sales
The change in a company’s store base only tells one side of the story. The other is the performance of its existing locations and e-commerce sales, which informs management teams whether they should expand or downsize their physical footprints. The same-store sales metric provides insight into this question because it measures organic growth for a retailer’s e-commerce platform and brick-and-mortar shops that have existed for at least a year.
Home Depot’s demand within its existing locations has barely increased over the last two years as its same-store sales were flat. This performance isn’t ideal, and any move by Home Depot to open new stores to artificially boost revenue growth would warrant skepticism.
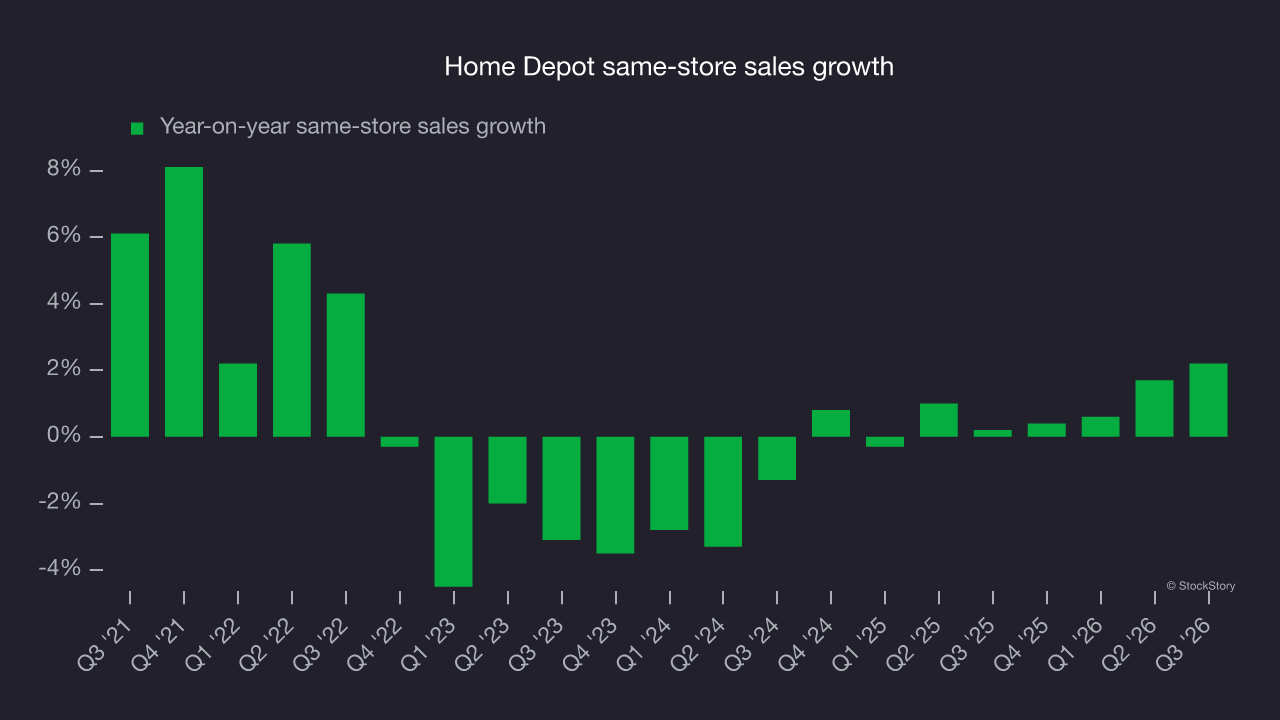
In the latest quarter, Home Depot’s same-store sales rose 2.2% year on year. This growth marked an acceleration from its historical levels, a positive sign.
Key takeaways from Home Depot’s Q3 results
Home Depot’s quarter was mixed, with revenue topping analysts’ consensus estimates, but gross margin came in slightly below expectations. Shares remained flat at $345.90 immediately after the report.
To assess Home Depot at its current price, consider the bigger picture of valuation and business quality alongside the latest earnings. Read our full research report here (it’s free).