
What WEBTOON Entertainment (WBTN)'s Narrower Loss And Revenue Outlook Means For Shareholders
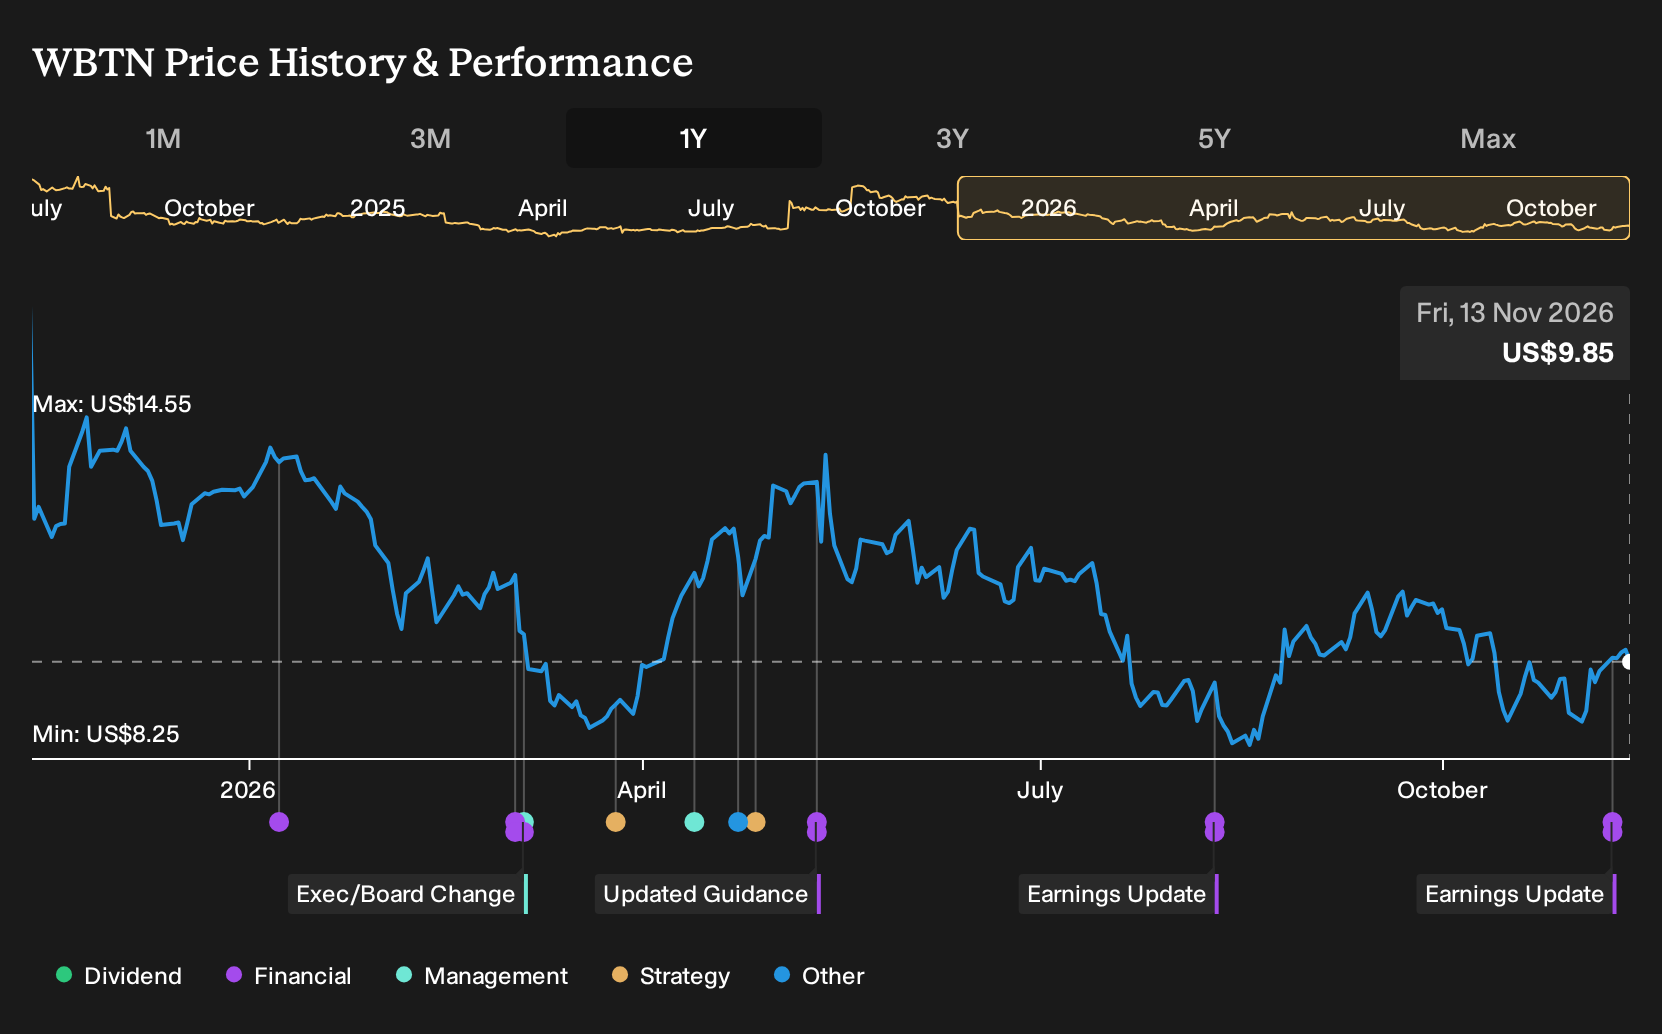
- WEBTOON Entertainment reported third quarter 2026 sales of US$362.78 million and a net loss of US$8.37 million, with both third quarter and year to date losses narrower than a year earlier despite slightly lower sales.
- Management paired these results with fourth quarter 2026 guidance for 9% to 12% constant currency revenue growth to an expected US$371 million to US$381 million, including planned contributions from RI Games Holdings Inc.
- This section examines how WEBTOON Entertainment's narrowed quarterly loss and fourth quarter revenue outlook could influence the broader investment narrative.
Scan WEBTOON Entertainment's earnings story against a curated 19 high quality undiscovered gems that may also be narrowing losses while working to grow their top line.
WEBTOON Entertainment Investment Narrative Recap
To own WEBTOON Entertainment, you generally need to believe the platform can turn a still growing global storytelling audience into sustainable profits, even with current losses. The latest quarter keeps that debate open. Sales dipped to US$362.78 million, yet the loss narrowed to US$8.37 million, suggesting cost control is at least moving in the right direction.
The key near term catalyst is whether user monetization improves in underpenetrated regions such as Japan and the Rest of World, as framed in the analyst consensus Narrative on Simply Wall St. The biggest risk is that higher marketing and operating spend fails to convert into paying users, leaving losses and weak margins lingering despite the fourth quarter revenue outlook.
The fourth quarter 2026 guidance is the news that really matters here. Management is calling for 9% to 12% constant currency revenue growth, or US$371 million to US$381 million, including RI Games Holdings contributions. For an investor, that sets a clear near term bar for execution after year to date sales of US$1,022.11 million and a net loss of US$33.07 million.
How WEBTOON Entertainment performs against this guidance ties directly into the catalysts outlined in the analyst consensus Narrative on Simply Wall St. Stronger revenue in the guided range would support the idea that content, partnerships, and product tweaks are feeding through to the top line. Falling short would raise questions about persistent Japan softness, legal overhangs, and whether the path to profitability is being pushed further out.
WEBTOON Entertainment's narrative projects US$1.8b revenue and US$43.0 million earnings by 2029. This assumes 8.9% yearly revenue growth and an earnings increase of about US$387 million from the current earnings loss of US$344.1 million.
Uncover how WEBTOON Entertainment's fair value indicates a 15% potential upside to its current price, before the market closes that gap.
Exploring Other Perspectives
Some of the most optimistic analysts were leaning hard into WEBTOON Entertainment’s AI features and RI Games tie up, expecting around 11.9% yearly revenue expansion and roughly US$148.4 million in earnings by 2029. You can now weigh those upbeat pre news assumptions against the fresh guidance and decide which story feels closer to your own view.
Explore 2 other WEBTOON Entertainment fair value estimates, including one that suggests as much as 135% potential upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your WEBTOON Entertainment research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for WEBTOON Entertainment. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate WEBTOON Entertainment's overall financial health at a glance.
Looking for more investment ideas beyond WEBTOON Entertainment?
Once you have a view on WEBTOON Entertainment, it can help to compare that story against other businesses with very different risk and income profiles using the Simply Wall St Screener.
- If you care about resilience first, scan a 29 resilient stocks with low risk scores that screens for businesses prioritizing stability over excitement.
- If income is the priority, review a 6 dividend fortresses that focuses on companies offering higher yields with the potential for steadier cash returns.
- If valuation discipline is non negotiable for you, line WEBTOON up against a 34 high quality undervalued stocks. This screener filters for financially stronger stocks that are priced below their estimated worth.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com