
What Mapfre (BME:MAP)'s €1 Billion Bond Sale Means For Shareholders
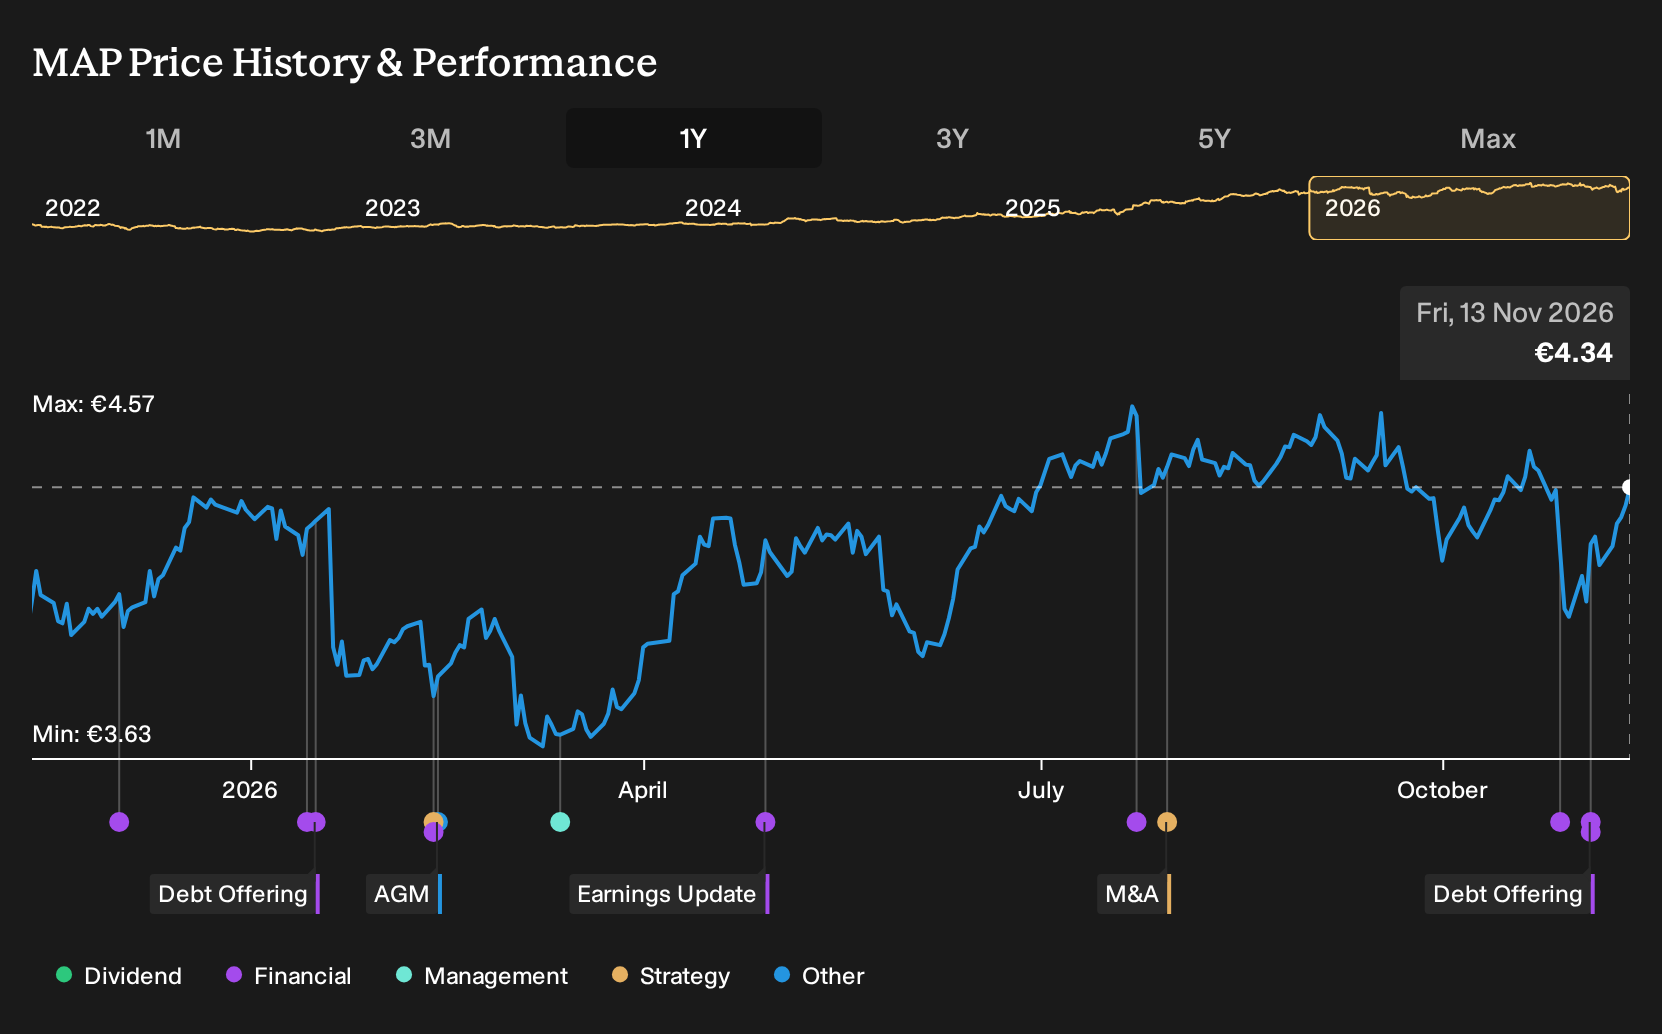
- Mapfre completed two euro medium term note offerings in early November 2026, issuing €500 million of 3.875% senior unsecured notes due 2029 and €500 million of fixed to floating rate subordinated notes due 2041, both priced slightly below par.
- This twin issue adds €1 billion of fixed income funding that reshapes Mapfre’s capital structure, blending senior and subordinated debt with different maturities and interest profiles.
- We will examine how Mapfre's investment narrative is influenced by this €1 billion debt raise, particularly the new subordinated callable notes.
Scan how Mapfre’s fresh €1 billion in bond funding compares with other insurers leaning on credit markets by reviewing our hand picked 211 resilient stocks with low risk scores built around balance sheet resilience.
Mapfre Investment Narrative Recap
To own Mapfre, you need to be comfortable with a slow top line, where revenue is expected to edge down about 0.03% a year, and a story built around earnings quality, underwriting discipline and capital strength. The analyst consensus Narrative on Simply Wall St leans heavily on consistent Non Life profitability, Latin America as a profit engine and a reliable 4.15% dividend.
The main near term swing factor is execution in core markets such as Iberia, Brazil and the U.S., including the Safety Insurance integration and pricing in reinsurance. The biggest risk remains external, with currency swings and fresh tax or regulatory hits in markets like Mexico or Colombia potentially chipping away at group profit.
The new €500 million 3.875% senior notes due 2029 and €500 million fixed to floating subordinated notes due 2041 slot directly into that capital story. This extra €1 billion of funding interacts with a solvency ratio previously guided around 205% to 210% and low leverage of roughly 21% to 26%, giving Mapfre more flexibility in how it supports operations.
For catalysts, the debt raise matters most where it intersects with investment needs in Latin America, ongoing digital projects in claims and underwriting, and the Safety Insurance build out in New England. If management keeps technical performance tight while absorbing any pricing pressure in reinsurance and currency moves, this fresh funding could simply sit in the background of the equity case.
Mapfre's current investment story is anchored on analysts expecting revenue of €29.0b and earnings of €1.4b by 2029, from earnings today of about €1.2b. That path assumes revenue declines by 2.4% each year and implies an earnings increase of roughly €200m by the 2029 forecast year.
Uncover why Mapfre's fair value indicates it is roughly in line with its current price.
Exploring Other Perspectives
One alternate view focuses squarely on balance sheet strain. The most cautious analysts already expected Mapfre's revenue to trend toward about €24.7b by 2029, with earnings of roughly €1.4b, before this €1b bond issue. That group worries extra leverage could tighten flexibility. You can use this contrast to test your own view and explore how opinions might shift once the new funding is fully reflected in forecasts.
Explore 2 other Mapfre fair value estimates, including one that suggests it could be worth just €4.24.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your Mapfre research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Mapfre. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Mapfre's overall financial health at a glance.
Looking for more investment ideas beyond Mapfre?
If Mapfre is just one piece of your watchlist, it can help to compare it with other businesses that share some of the qualities you care most about, whether that is value, balance sheet strength, or income.
- If you want to focus on companies that combine quality fundamentals with what the model views as attractive pricing, take a look at the 199 high quality undervalued stocks.
- For investors who care most about financial resilience and capital strength, filter for businesses with sturdier finances using the list of solid balance sheet and fundamentals (200 results).
- If income is a priority and you are hunting for higher yield opportunities, start with our screen of potential dividend heavyweights via the 219 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com